Author: Sophie Davis

  • The Quiet Rise of Revenue-Based Financing for UK Digital Businesses: What Founders Need to Know

    The Quiet Rise of Revenue-Based Financing for UK Digital Businesses: What Founders Need to Know

    There is a version of growth funding that does not ask you to give away equity, does not require a personal guarantee on your family home, and does not saddle you with fixed monthly repayments when your revenue dips in January. Revenue based financing has been doing quiet but serious work in the UK for several years now, and in 2026 it has become a genuinely mainstream option for digital founders who know where to look. I have spoken with a number of SaaS operators and e-commerce founders over the past year who used it, and the honest answer is: it suits some businesses very well and suits others poorly. Understanding which side of that line you are on is worth your time before you sign anything.
    Founder reviewing revenue based financing options for UK digital businesses on a laptop
    Photo by Yan Krukau on Pexels

    What revenue based financing actually is

    Revenue based financing (RBF) is a funding model where a lender advances a lump sum and recovers it as a fixed percentage of your monthly revenue until a pre-agreed total is repaid. That total is typically the original advance multiplied by a factor somewhere between 1.2 and 1.6, depending on the provider and the risk profile of your business. There is no equity transferred, no interest rate in the conventional sense, and repayment naturally slows when your revenue slows, which is the feature that makes it genuinely different from a term loan.

    The mechanics matter. If a lender advances £150,000 with a 1.35 factor, you repay £202,500 in total. If they take 8% of monthly revenue, and your average monthly revenue is £80,000, the repayment runs for roughly 32 months under steady conditions. In a strong month you pay more; in a weak month you pay less. That flexibility is the product’s core appeal for digital businesses with variable but recurring income.

    Why it fits digital businesses particularly well

    Revenue based financing UK digital businesses have accessed in meaningful volume tends to cluster around a particular profile: SaaS platforms with monthly recurring revenue between £30,000 and £500,000, e-commerce brands with clean Shopify or WooCommerce data, and app developers with verifiable app store revenue. The reason is simple. RBF underwriting is largely data-driven. Providers connect directly to your Stripe, Xero, QuickBooks or bank feed, run their models, and can return a decision in 48 to 72 hours. No three-year projections, no pitch deck, no waiting for a credit committee that meets fortnightly.

    Traditional bank lending remains slow and relationship-dependent for most SMEs. Equity funding asks you to share your upside permanently. RBF sits between the two, and for a founder who is confident their revenue will grow but does not want to dilute, it is often the more rational choice. I would also point out that the lack of a fixed monthly repayment is not just operationally convenient; it can genuinely preserve working capital during seasonal troughs, which for many UK digital businesses means getting through February without cutting headcount.

    Who the key UK providers are

    The UK market has matured considerably. Uncapped and Capchase both operate here and are well established in the SaaS and subscription revenue space. Clearco (formerly Clearbanc) focuses heavily on e-commerce and takes a data-led approach to underwriting that leans on advertising spend efficiency as well as revenue. Pipe connects businesses with investors by treating contracted recurring revenue as a tradeable asset, effectively letting you advance future subscription income at a discount. YouLend, which is backed by Goldman Sachs and operates through partnerships with the likes of eBay and Shopify UK, is another significant player for merchants embedded in those platforms.

    It is worth checking the British Business Bank’s Finance Hub guidance on revenue based financing for an independent overview of the landscape, as they maintain reasonably current information on the options available to UK SMEs and how to compare them.

    None of these providers is a bank, and none is regulated by the FCA in the way a lender offering consumer credit would be. That has implications. You have fewer statutory protections in a dispute, and the contracts can contain clauses that catch founders off guard, including covenants that restrict you from taking on additional debt or paying shareholder dividends above a threshold while the advance is outstanding.

    What the true cost of capital looks like

    This is where founders often make mistakes, and I want to be direct about it. RBF providers do not quote APR because their product is not technically a loan. They quote a factor rate. A 1.3 factor on a £100,000 advance means you repay £130,000. That sounds manageable until you work out how quickly you repay it. If you clear the advance in eight months, the effective APR is significantly higher than 30%. If it takes 24 months, the effective APR looks much more reasonable.

    The speed of repayment depends on your revenue percentage and how fast your business grows. Faster growth means faster repayment means a higher effective cost. There is a certain irony there: the better your business performs, the more expensive the financing turns out to be in annualised terms. That is a structural feature of the product, not a bug, and it is why some high-growth founders find equity cheaper in total over a five-year horizon despite the dilution.

    For a business planning to use the capital for performance marketing with a clear return on ad spend metric, or for a product release that generates a measurable revenue uplift, the maths often still works. The key is modelling the repayment under realistic revenue scenarios before committing. If you are already using a cloud-native finance platform, as many UK SMEs now are, running those scenarios is straightforward. The shift towards cloud-native ERP platforms has made this kind of forward cash flow modelling accessible to businesses that would previously have needed a finance director to run it.

    What to watch out for before you sign

    The revenue percentage matters more than the factor rate in terms of your day-to-day experience. A 10% sweep on monthly revenue will be felt differently in a month where you do £40,000 versus one where you do £120,000. Check whether the percentage is applied to gross revenue or net revenue after refunds and chargebacks, because for some e-commerce businesses those two numbers differ substantially.

    Check the minimum payment clause. Some providers include a floor, meaning that even if your revenue collapses, you owe a minimum monthly amount. That turns a flexible product into something closer to a fixed obligation, and it is worth knowing about before you are in that situation. If you already carry some credit risk across your supplier base, a thorough read of the contract terms sits alongside the same diligence you would apply to vetting UK suppliers using Companies House and credit reference data: the details are in the document, not in the pitch.

    Also worth checking: does the provider require exclusivity? Some insist that any new funding during the repayment period runs through them. For a business that might need additional capital quickly, that restriction can be more constraining than it appears at the outset.

    Is it right for your business?

    Revenue based financing UK digital businesses should consider when they have strong recurring or predictable revenue, a clear use of funds with a measurable return, and a founder who does not want to dilute equity at an early stage. It is a poor fit for pre-revenue businesses, for businesses with highly irregular income, or for situations where the capital need is long-term and structural rather than tied to a specific growth lever.

    My honest take is that the product has been slightly oversold in some circles as a frictionless alternative to everything. It is not. It is a specific instrument with a specific use case, and the founders who use it well are the ones who modelled their repayment before they signed and knew exactly what the advance was going to fund. Used that way, it is a genuinely useful addition to the UK financing toolkit, and one that has earned its place alongside equity and debt rather than replacing either.

    Frequently Asked Questions

    What revenue do I need to qualify for revenue based financing in the UK?

    Most UK RBF providers require a minimum of £10,000 to £30,000 in monthly recurring revenue, though some platforms set their threshold higher. Providers will typically want to see at least six months of consistent revenue data before making an offer.

    How quickly can I access funds through revenue based financing?

    Because underwriting is data-driven rather than relationship-based, most UK providers can return a decision within 48 to 72 hours once you have connected your payment processor or accounting software. Funds typically land within a week of approval.

    Does revenue based financing affect my credit score or credit rating?

    Most RBF providers do not carry out a hard credit search on the individual founder, so your personal credit file is generally unaffected. However, the advance may appear on your business credit record depending on how the provider reports to credit reference agencies.
  • How to Use Companies House Data Alongside Credit Reference Agency Reports to Vet UK Suppliers

    How to Use Companies House Data Alongside Credit Reference Agency Reports to Vet UK Suppliers

    Supplier due diligence is one of those disciplines that finance and procurement teams know they should be doing thoroughly, but often compress under time pressure. A supplier comes recommended, the price is right, the samples look good, and before long someone has signed a contract without ever checking whether the company filing those professional-looking invoices has actually filed its accounts on time, or whether the director behind it has a history of dissolved entities. I’ve seen this go wrong at every level, from start-ups to FTSE-listed procurement teams, and the pattern is almost always the same: the early warning signs were there in the public data; nobody looked.

    This guide is for procurement managers, finance directors, and anyone in a UK business who is responsible for onboarding new suppliers or managing ongoing supply chain risk. The approach here combines free public registry data with commercial credit intelligence to build a picture that is both rigorous and proportionate to what you’re actually buying.

    Finance professionals reviewing supplier documents as part of vetting UK suppliers using Companies House data
    Photo by RDNE Stock project on Pexels

    Why public registry data is your starting point, not your finishing line

    Companies House is the obvious first stop when vetting UK suppliers using Companies House data, and it is genuinely powerful if you know what you’re looking for. Every UK limited company is required to file confirmation statements and accounts. The filing history alone tells you a great deal: a company that consistently files late, or has had its accounts overdue notices appear, is already showing signs of poor administration at minimum, and potential cash flow strain at worst.

    When you pull a company record on Companies House, go beyond the headline registration date. Look at the following in sequence.

    Incorporation date and company type. A supplier claiming decades of experience but incorporated three years ago warrants a question. They may have restructured from a previous entity, which is fine, but you want to know why.

    Persons with significant control (PSC) register. Who actually owns this business? The PSC register has been mandatory since 2016 and reveals beneficial ownership. If the PSC entry lists an overseas holding company rather than an identifiable individual, that is not automatically a problem, but it does add a layer of opacity worth exploring.

    Director history. Look up the directors individually. The Companies House beta search lets you view all company appointments associated with a given individual. A director with five dissolved companies in five years is a material flag. This is different from an entrepreneur who has built and exited businesses cleanly; the filings will usually make that distinction obvious.

    Charges register. If a supplier has registered charges against their assets (essentially secured lending), you need to understand the scale of that relative to their trading activity. Significant fixed and floating charges held by lenders can affect your position as a creditor if things go sideways.

    What Companies House cannot tell you

    The public registry gives you legal structure, ownership, and historic filing behaviour. What it does not give you is a real-time view of financial health, payment behaviour, or how a supplier treats its own creditors. That is where commercial credit reference agencies come in.

    In the UK, the main providers for business credit intelligence are Experian Business, Creditsafe, and Dun & Bradstreet. Each has a slightly different methodology and different data sources, so if the supplier is material to your operations, I’d argue pulling reports from at least two of them is worth the cost. Credit scores vary between bureaux; a supplier scoring well on one and poorly on another is itself informative.

    The credit report will typically give you a payment performance score, derived from trade payment data shared by other creditors. This is the single most useful forward-looking indicator in the report. A company can look solvent on paper but be consistently paying invoices 60 to 90 days late, which is a reliable sign of cash flow pressure. You want to be on the right side of that payment queue.

    The report will also include a recommended credit limit, which is calculated based on assets, liabilities, and payment history. If you’re planning to extend your supplier 60-day payment terms while they have a recommended credit limit of £15,000, something does not add up. Either your trading volume is too large for them to handle without strain, or their financials are weaker than their sales pitch implies.

    County Court Judgements (CCJs) appear in credit reports too, and these are particularly telling for smaller suppliers. A CCJ means a court has formally ruled that a debt exists and has not been satisfied. One CCJ, satisfied promptly, is forgivable. Multiple unsatisfied CCJs are a serious concern, and any CCJ registered in the 12 months before you’re onboarding a new supplier should trigger a direct conversation.

    Building a proportionate due diligence framework

    Not every supplier needs the same level of scrutiny. A £3,000 annual spend on office supplies does not warrant the same process as a £500,000 contract with a sole-source software development partner. I tend to segment suppliers into three tiers based on spend and criticality, then apply a corresponding level of review.

    For tier one suppliers (high spend, operationally critical, or where failure would affect your customers), run the full Companies House review, pull reports from two credit bureaux, ask for audited accounts directly if the most recent Companies House filing is more than 12 months old, and consider a site visit or video call with their finance director. Given how much depends on these relationships, the time invested is entirely justified.

    For tier two suppliers, a Companies House check and a single credit report is usually sufficient, supplemented by trade references from two named customers you contact directly (not references the supplier selects and coaches).

    For tier three suppliers, a basic Companies House confirmation of existence, registration age, and clean officer history is proportionate. You’re largely checking that the company is real and registered.

    One thing worth building into your onboarding form is a requirement for suppliers to provide their Companies House number and registered address upfront. This sounds obvious, but I’ve seen procurement teams spend an afternoon trying to match a trading name to a legal entity because the supplier provided neither. Make it a mandatory field and the rest of the lookup takes minutes.

    Keeping supplier risk intelligence current

    Due diligence at onboarding is necessary but not sufficient. A supplier who passes every check in January can file a profit warning or accumulate CCJs by October. Most commercial credit platforms offer monitoring alerts, where you receive a notification if a supplier’s credit score drops significantly, if new charges are registered, or if director changes occur. For any supplier above your tier one threshold, turning these alerts on is straightforward and the cost is modest relative to the exposure you’re managing.

    Annual reviews for critical suppliers should pull a fresh credit report and cross-reference it against the previous year’s filing on Companies House. If accounts show deteriorating margins alongside a worsening payment score, that is the combination that tends to precede supplier insolvency. Catching it a year early gives you time to dual-source or renegotiate rather than managing an emergency.

    For UK businesses thinking about the broader operational risk dimension, the principles here dovetail with the kind of financial resilience planning covered in discussions around business interruption insurance and tech outage cover. Supplier failure is one of the most common triggers for operational disruption, and yet it rarely features in the scenarios businesses model in advance.

    It is also worth noting that finance teams increasingly have access to better tools for this kind of ongoing monitoring. The shift to cloud-native finance platforms means data from credit bureaux can often be integrated directly into approval workflows, rather than sitting in a separate spreadsheet nobody checks. If your team has been thinking about ERP modernisation, the move to cloud-native ERP for UK SMEs is making exactly this kind of integrated risk view more accessible at mid-market budget levels.

    A note on international suppliers

    Everything above applies cleanly to UK-registered limited companies. For overseas suppliers, the process gets more complex but the logic is identical: find the equivalent public registry (Germany has the Handelsregister, France has the Registre du Commerce et des Sociétés), use a credit bureau with international coverage (Dun & Bradstreet and Creditsafe both operate internationally), and apply additional scrutiny to any suppliers operating through jurisdictions with weak corporate transparency requirements.

    UK finance and procurement professionals working with overseas entities should also be aware of HMRC’s guidance on supply chain fraud, particularly in high-risk sectors, since the tax authority expects businesses to take reasonable steps to verify that their supply chain does not involve missing trader fraud. That is a separate but overlapping discipline from credit risk, and one worth understanding if your business reclaims significant VAT on purchases.

    Vetting UK suppliers using Companies House data is not glamorous work. But it is the kind of work that occasionally saves a business from a genuinely damaging situation. The data is there, most of it is free, and combining it with a credit report takes less than an hour per supplier. The cost of not doing it, as anyone who has dealt with a key supplier entering administration will tell you, is considerably higher.

  • How UK Manufacturers Are Using Fleet Telematics and IoT Data to Cut Costs and Meet ESG Obligations

    How UK Manufacturers Are Using Fleet Telematics and IoT Data to Cut Costs and Meet ESG Obligations

    There is a quiet transformation happening on the roads and factory floors of Britain. Over the past two years, I’ve spoken to logistics managers, fleet directors, and operations leads across UK manufacturing, and the same phrase keeps coming up: “the data finally pays for itself.” That shift is being driven by fleet telematics and IoT data platforms that have moved well beyond basic GPS tracking into something genuinely strategic.

    The business case has sharpened considerably in 2026. Fuel costs remain elevated, mandatory Scope 3 emissions reporting is bearing down on mid-sized manufacturers, and institutional investors are increasingly asking hard questions about operational carbon exposure. Connected vehicle telematics answers all three at once, which is why adoption among UK fleets has accelerated sharply.

    Fleet manager reviewing fleet telematics and IoT data dashboards in a UK distribution centre
    Photo by Robert So on Pexels

    What fleet telematics actually does in a modern UK operation

    A decade ago, telematics meant a black box that logged mileage and sent an alert if a driver went over 70 mph. Today, platforms like Microlise, Verizon Connect (operating heavily across UK logistics), and MiX Telematics are integrating real-time vehicle data with warehouse IoT sensors, driver behaviour scoring, route optimisation engines, and carbon accounting tools. The result is a continuous operational picture that would have required a small analytics team to assemble manually.

    For a typical UK haulier running 50 to 200 vehicles, a modern telematics platform will track engine idle time, harsh braking events, tyre pressure anomalies, and fuel draw per leg of a route. Cross that with IoT sensors on loading bay doors, refrigeration units, or pallet tracking systems, and you start to see where time and fuel are genuinely being wasted versus where the operation is genuinely efficient. The numbers are striking. According to BEIS and DESNZ data on fleet energy use, idle engine time alone can account for 15 to 20 per cent of HGV fuel consumption on regional distribution routes. Eliminating it is not a marginal gain.

    The Scope 3 reporting pressure that is making telematics non-negotiable

    UK manufacturers supplying large retailers, public sector bodies, or listed companies are now routinely asked to provide Scope 3 emissions data as part of supplier onboarding and annual reviews. Scope 3 covers indirect emissions across the value chain, including transport and distribution, which puts fleet activity squarely in the spotlight. Without granular telematics data, those figures have to be estimated using generic emission factors, and auditors and procurement teams are getting wise to the difference between real measurement and a spreadsheet approximation.

    This connects directly to the broader wave of mandatory climate-related financial disclosures that UK businesses are navigating. If you want a clearer picture of what those obligations look like in practice, the article on how UK businesses are preparing for mandatory climate-related financial disclosures sets out the regulatory timeline well. The short version: being able to demonstrate measured, not modelled, Scope 3 data from your transport operations is becoming a genuine differentiator, both for compliance and for tender submissions.

    Companies like Wincanton and DHL Supply Chain UK have published fleet carbon intensity figures down to individual route level, and the bar is rising across the industry. Smaller manufacturers supplying into those chains are expected to match the same reporting quality, even if they are running a tenth of the vehicle count.

    HGV equipped with fleet telematics and IoT sensors on a UK motorway
    Photo by David Brown on Pexels

    How insurers and investors are using fleet data

    This is where fleet telematics and IoT data moves from operational tool to financial asset. Commercial fleet insurers in the UK, including Zurich, Allianz Commercial, and several Lloyd’s syndicates, now offer meaningful premium reductions tied to telematics-verified driving behaviour and vehicle maintenance records. A documented reduction in harsh braking events, combined with clean tyre and brake inspection data pulled from IoT sensors, translates directly into a lower risk profile. Some fleet operators I’ve spoken with have negotiated reductions of 12 to 18 per cent on their annual premiums after two years of clean telematics data.

    The investor angle is less discussed but equally real. Private equity-backed logistics and manufacturing businesses going through due diligence in 2025 and 2026 are being asked to present operational data as part of ESG scoring. A fleet that can demonstrate a verified year-on-year reduction in fuel intensity per tonne-kilometre, backed by telematics records, is a materially different asset from one producing the same revenue with no data trail. It is the kind of thing that influences EBITDA adjustments and earnout valuations.

    The same data culture shaping how commercial operators think about their fleets is also influencing wider conversations about vehicle running costs. Fast & Furious News has been tracking how rising insurance and operating costs are affecting young UK drivers in 2026, and the underlying dynamic is similar: the more verifiable data you can produce about how a vehicle is being used, the more leverage you have in conversations with insurers.

    Route optimisation and the fuel savings that compound

    Beyond compliance and insurance, the operational payoff from fleet telematics is most visible in route optimisation. Platforms that combine real-time traffic data with historical route performance and vehicle-specific fuel consumption curves are consistently finding 8 to 14 per cent reductions in fuel spend on optimised routes, without reducing delivery capacity. For a manufacturer running a 100-vehicle mixed fleet, that is a material sum against an annual fuel budget that easily reaches seven figures.

    The compounding effect matters here. Better routes mean lower emissions data for Scope 3 reporting. Lower emissions data improves ESG scores. Better ESG scores reduce the cost of trade finance and insurance. The whole thing reinforces itself, which is why I’d argue telematics is one of the few infrastructure investments a UK manufacturer can make right now that pays dividends across the P&L, the balance sheet, and the compliance function simultaneously.

    There is also a workforce dimension worth mentioning. Driver behaviour data, when handled transparently and in line with ICO guidelines on employee monitoring, tends to improve safety records rather than simply creating a surveillance burden. Businesses that share telematics dashboards with drivers, framing the data as a tool for coaching rather than discipline, consistently report better safety outcomes and lower vehicle wear. The smart motorway environment is adding another layer of complexity here; anyone operating HGVs on managed motorways will want to understand how variable speed limits are affecting driving patterns on UK smart motorways, since the telematics picture looks quite different on those stretches compared to conventional A-roads.

    Getting the data infrastructure right from the start

    One mistake I see consistently among manufacturers new to serious telematics deployment is treating the platform as a standalone tool rather than integrating it with their broader operational systems. Fleet telematics and IoT data produces its real value when it feeds into the ERP, the carbon accounting tool, and the finance function simultaneously. Businesses that have made this connection, and there is a growing group of UK SMEs doing exactly this as they move finance functions to cloud-native ERP platforms, are the ones extracting the full return from their investment.

    The cost of entry has also dropped significantly. Basic connected telematics hardware for a commercial vehicle now runs at £150 to £300 per unit installed, with SaaS platform fees in the region of £15 to £40 per vehicle per month depending on the feature set. For a 50-vehicle fleet, the full annual cost sits somewhere between £18,000 and £36,000. Set that against verified fuel savings of 10 per cent on a six-figure fuel budget, plus insurance reductions and compliance time saved, and the payback period is typically under 18 months.

    The businesses that move on this now will have two to three years of clean, auditable emissions and operational data by the time reporting obligations become fully mandatory across their tier of supply chain. That head start is worth considerably more than the platform cost.

    Frequently Asked Questions

    What is fleet telematics and how does it differ from basic GPS tracking?

    Fleet telematics goes well beyond location tracking. Modern platforms collect data on engine performance, driver behaviour, fuel consumption, tyre pressure, braking patterns, and idle time, often integrating with IoT sensors on trailers and loading equipment. The result is a granular operational picture that GPS alone cannot provide.

    How does fleet telematics help UK businesses with Scope 3 emissions reporting?

    Scope 3 reporting requires businesses to account for indirect emissions, including transport and distribution. Telematics platforms generate measured fuel consumption and mileage data per route and vehicle, producing verified emissions figures rather than estimates based on generic factors. Auditors and procurement teams increasingly expect this level of detail.

    Can telematics data actually reduce commercial fleet insurance premiums in the UK?

    Yes. UK commercial insurers including Zurich and Allianz Commercial offer reduced premiums tied to verified driver behaviour scores and maintenance records from telematics systems. Fleets with two or more years of clean data have reported premium reductions of 12 to 18 per cent in recent renewals.

    What does fleet telematics and IoT integration typically cost for a mid-sized UK manufacturer?

    Hardware installation runs roughly £150 to £300 per vehicle, with platform subscription fees of £15 to £40 per vehicle per month. A 50-vehicle fleet should budget £18,000 to £36,000 annually in total. Given typical fuel savings and insurance reductions, most operators see payback within 12 to 18 months.

    Do UK data protection rules allow employers to monitor drivers using telematics?

    Yes, provided businesses comply with ICO guidelines on employee monitoring, which require workers to be informed about what data is collected, why it is collected, and how it will be used. Transparent policies and sharing data with drivers as a coaching tool are both recommended practice and tend to produce better safety outcomes.

  • How UK Charities and Community Organisations Are Using Event Microsites to Coordinate Volunteers and Supporters

    How UK Charities and Community Organisations Are Using Event Microsites to Coordinate Volunteers and Supporters

    Community events in the UK run on goodwill, volunteer hours, and a fair amount of scrambled last-minute communication. A WhatsApp thread with 47 members arguing about where to park the float. A PDF route map that nobody can open on their phone. A printed newsletter that arrived three days after the event. I’ve spoken to enough committee organisers to know this is the norm, not the exception. Event microsites for charities are changing that, not by replacing the handcrafted, community-feel elements people love, but by giving supporters a single digital address where the live details actually live.

    Volunteers reviewing printed materials and a laptop screen while building event microsites for charities
    Photo by RDNE Stock project on Pexels

    This guide is for the committee secretary who manages everything from a laptop on the kitchen table, the volunteer coordinator at a local hospice charity, and the PTA chair who also happens to be running the Christmas sleigh run. You don’t need a developer. You don’t need a budget that would embarrass a FTSE 100 marketing team. You need the right approach and a clear sense of what a microsite should actually do.

    What is an event microsite and why does it matter for non-profits?

    A microsite is a small, standalone website built around a single event or campaign. Think of it as a dedicated landing page with a few sections rather than a full website with a navigation menu, an about page, a history of the organisation going back to 1987, and a members-only area nobody uses. The microsite strips all of that out. One URL, shared on printed flyers, local Facebook groups, and the parish newsletter, points supporters directly to what they need: the date, the route, the schedule, how to donate, and any updates since the flyer went to print.

    For non-profits and community groups, this matters because printed materials, which most still rely on, go stale the moment they leave the printer. A microsite lets you publish the route map change at 9pm on a Friday without reprinting anything. The government’s own guidance on running a community event recommends keeping participants informed through multiple channels, and a lightweight microsite is one of the most practical ways to do that without needing a comms team.

    What should a charity event microsite actually contain?

    Keep it ruthlessly focused. I’d argue that most charity microsites fail because someone adds too much, the entire history of the organisation, three different donation platforms, an embedded social feed that takes six seconds to load on a 4G connection in a village hall car park. The sections that genuinely serve supporters are simpler than that.

    A countdown timer is more useful than it looks. When supporters can see that the sponsored walk is 11 days away, registration urgency becomes real. Tools like Carrd, Notion Sites, or even a basic Google Sites page can embed a countdown without any code. For groups with slightly more technical confidence, Webflow’s free tier or a WordPress.com plan gives you enough flexibility to add route maps from Google Maps, embedded directly into the page so visitors can check it on their phones the night before.

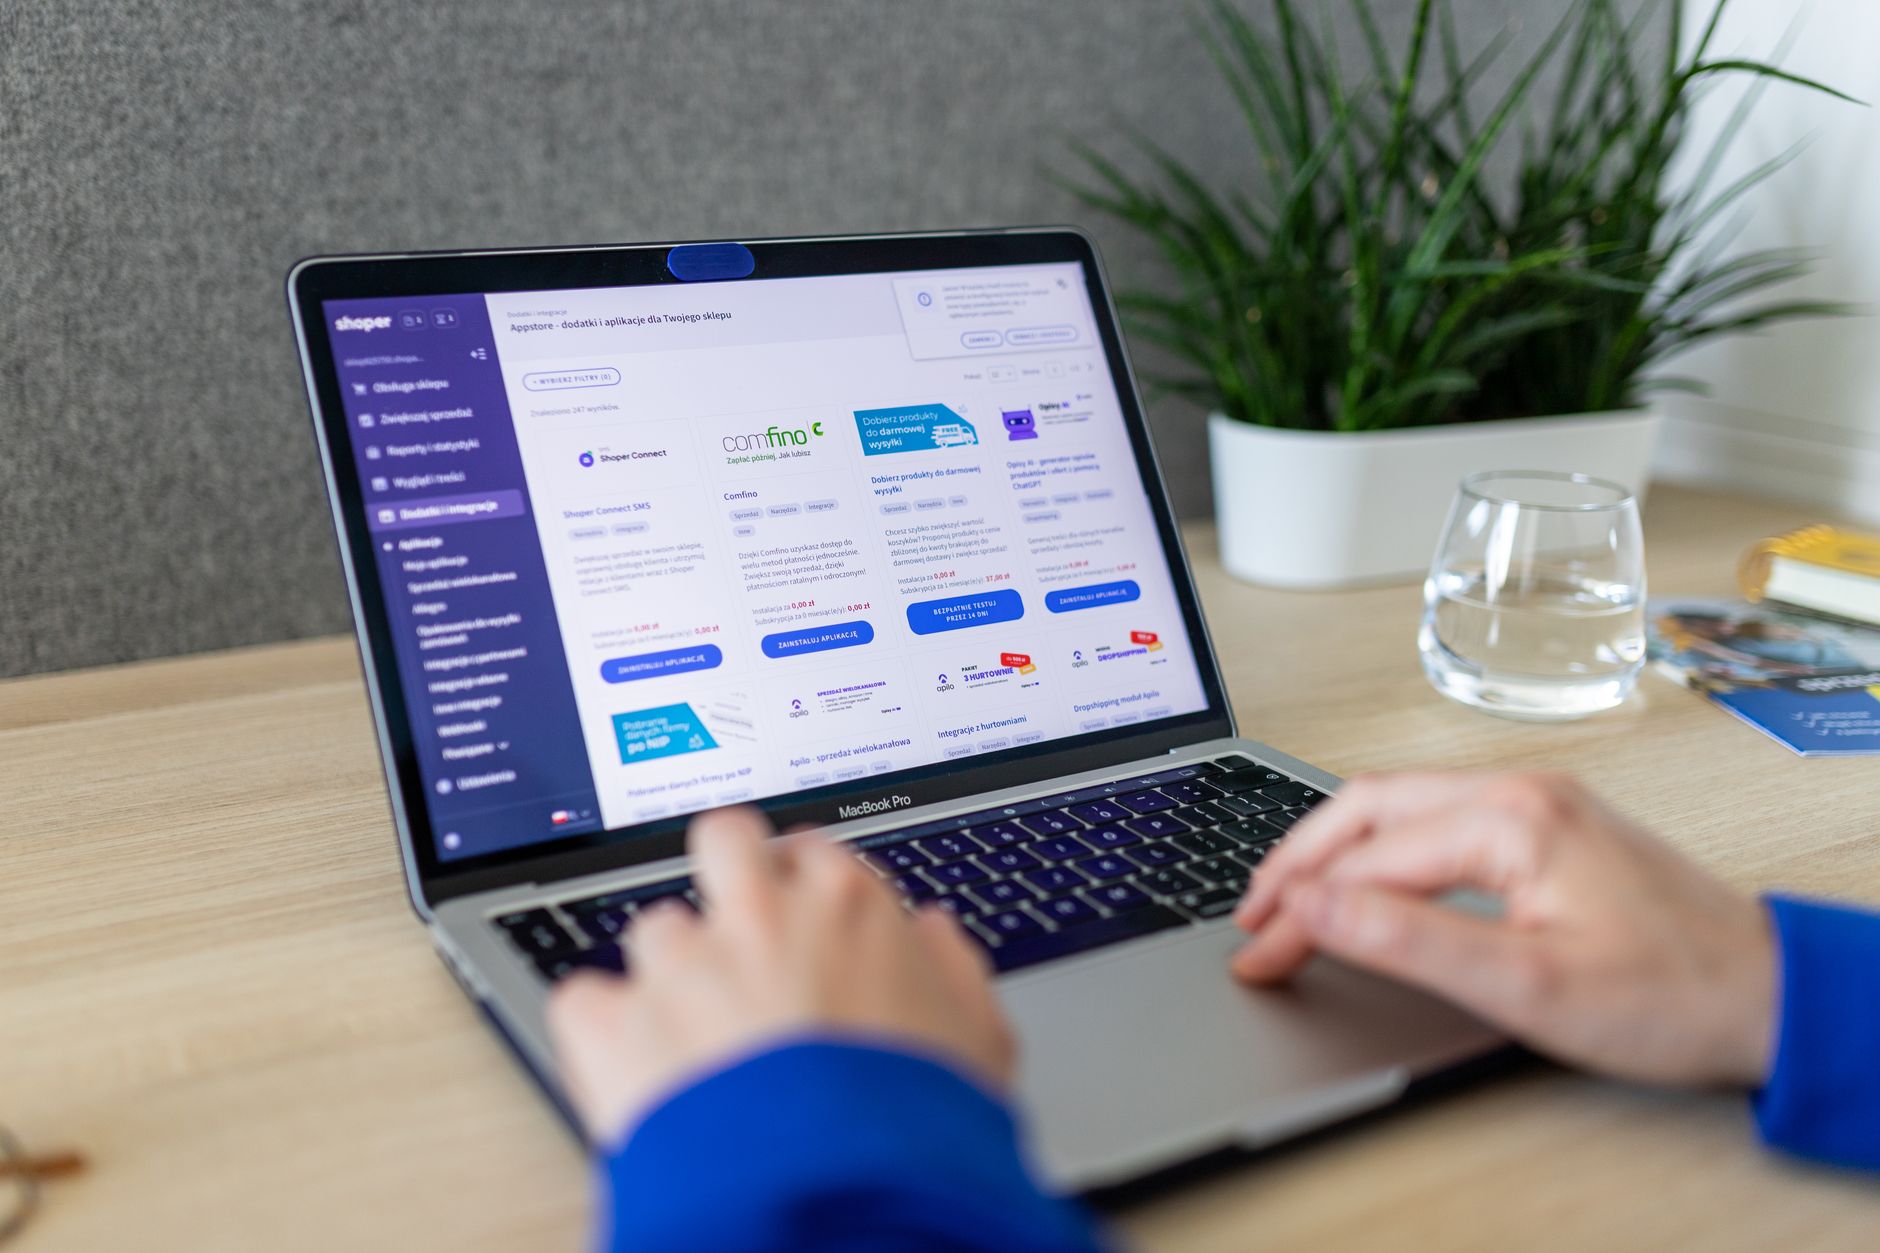
    Laptop screen showing an event microsite for charities with a countdown and route map
    Photo by Shoper .pl on Pexels

    Real-time updates deserve their own section on the page, clearly labelled. A simple reverse-chronological list, “Update 14 November: start time moved to 10:30am due to road closure on the High Street”, does more practical good than a polished news section updated monthly. Supporters want to know what’s changed. Give them that, plainly.

    Volunteer sign-up should connect to something that actually captures data. Embedding a Google Form or a Typeform (both free at basic tier) means you stop collecting names on scraps of paper. The form submissions go directly into a spreadsheet you can filter by role, shift, or location. For groups managing a sleigh run with helpers across multiple postcodes, this is genuinely transformative.

    Pairing digital tools with printed and handcrafted materials

    The microsite doesn’t replace the printed programme or the decorated collection tin. It works alongside them. The most effective community events I’ve seen treat digital and physical as two parts of the same communication plan. A QR code on the printed leaflet links directly to the microsite. The microsite references the printed map. Each medium does what it does best.

    For groups managing the creative side of community events, designing sleigh routes, festive artwork for collection materials, or advent-themed displays, the visual and the digital are genuinely complementary. If you’re working through the artwork side, there’s a longer read on how to design colourful advent calendar artwork for your community sleigh run: a uk crafter’s guide that pairs well with the practical digital setup covered here. Getting both right means your event looks professional without needing a professional agency behind it.

    One practical tip: use a custom short URL for the microsite rather than whatever long string your website builder generates. A free Bitly link or a short branded domain (registrable for under £10 through Namecheap or 123-reg) means the URL fits on a flyer, can be read aloud at a meeting, and is memorable enough that a supporter can type it a week later from memory. This small detail makes a real difference to how many people actually visit the page.

    Tools UK community groups are actually using in 2026

    Carrd remains the most popular option I’ve come across among smaller non-profits and community committees. It’s genuinely free for a single-page site, loads quickly on mobile, and requires no technical knowledge. For multi-page needs, Google Sites is free and integrates naturally with the G Suite tools most organisations already use, Google Forms for volunteer registration, Google Maps for route embeds, Google Calendar for the event schedule.

    Notion has found an unexpected second life here too. Several local groups now publish their event information as a public Notion page. It isn’t the slickest solution aesthetically, but it’s editable by anyone with committee access, updates instantly, and handles embedded maps and forms adequately. For a PTA or a local Rotary club running a single annual event, it’s entirely sufficient.

    If your group has a small budget, even £50 to £100 a year, a WordPress.com Business plan or a Squarespace personal plan opens up proper countdown widgets, better mobile formatting, and custom domain support. At that price point, it’s worth it if the event recurs annually. You update the same microsite each year rather than rebuilding from scratch.

    Keeping distributed supporters informed without overwhelming them

    The mistake most organising committees make is publishing updates in too many places simultaneously. The WhatsApp group gets a message. The Facebook event gets a post. The email list gets a newsletter. The microsite gets updated three days later when someone remembers. Supporters who follow multiple channels get conflicting information, and the organiser spends twice as long managing communications as they should.

    A cleaner approach: treat the microsite as the single source of truth, and use WhatsApp, email, and social only to direct people there. “We’ve updated the route, check the website for details” is one message. It takes 30 seconds to send, and it drives traffic to the one place where the information is always current. If you’re already thinking about how tools like this connect to broader communication strategy, our piece on what UK employers need to know about remote work communication policies touches on similar principles around information flow and channel discipline, worth a read if your organisation is growing its volunteer base.

    For larger community organisations managing multiple events across a year, it’s worth thinking about how the microsite approach scales. At some point, a lightweight content management system makes more sense than rebuilding individual pages each time. That’s also the point at which a group might want to look at how data collected through volunteer forms is stored and managed, the ICO’s guidance on data protection for charities is straightforward and freely available, and worth bookmarking before you start collecting names and contact details at scale.

    Getting the microsite live before the event materials go to print

    Timing is the element most committees underestimate. The microsite needs to exist before the flyers are printed, because that’s when the URL gets added to the design. Build the page first, even if it only has the event name, date, and a “more details coming soon” note, then add the URL to the print file. Everything else can be filled in later. Trying to retrofit a digital presence after the printed materials are already circulating is a headache that’s entirely avoidable.

    I’d also recommend setting a Google Alert for your event name. If the local press picks up the story or a supporter shares the microsite URL somewhere unexpected, you’ll know about it and can make sure the page is ready to receive that traffic. It costs nothing and takes two minutes to set up.

    The best community events feel effortlessly organised even when the reality is anything but. A clean, functional microsite, updated when something changes, easy to find, fast to load on a phone, does a lot of the heavy lifting. It won’t write your risk assessment or persuade the council to close the road for an hour, but it will stop your volunteers showing up at the wrong end of the High Street at 7am on a wet Saturday in November. That, frankly, is worth the effort.

  • How UK Landlords and Letting Agents Are Using PropTech to Navigate the Renters’ Rights Act

    How UK Landlords and Letting Agents Are Using PropTech to Navigate the Renters’ Rights Act

    The pace of legislative change hitting UK landlords right now is, frankly, relentless. The Renters’ Rights Act, which abolishes Section 21 “no-fault” evictions and introduces a new ombudsman scheme, is reshaping how private letting actually works in practice. I’ve spoken to several letting agents over the past few months, and the word I hear most often is “overwhelmed”. The paperwork alone has multiplied. The compliance window is tightening. And staff who once managed portfolios on spreadsheets and gut instinct are suddenly being asked to operate like a regulated financial firm. That’s where PropTech for landlords is stepping in to fill a genuinely critical gap.

    Letting agent using PropTech for landlords on a laptop in a modern UK office
    Photo by MART PRODUCTION on Pexels

    What PropTech actually covers in a letting context

    “PropTech” gets used loosely, so let’s be precise. In the context of letting and landlord management, it refers to digital platforms that handle one or more of the following: tenancy creation and document management, rent collection and arrears tracking, maintenance logging, compliance record-keeping, and communication audit trails between landlord, agent, and tenant.

    Tools like Arthur Online, Goodlord, Vouch, and Reapit have been around for a few years, but their relevance has sharpened considerably since the Renters’ Rights Bill moved through Parliament. The new legislation doesn’t just change what landlords can and can’t do, it creates a documentation burden that is almost impossible to manage manually at scale. When you can no longer serve a Section 21 notice and must instead rely on specific grounds under Section 8, having a clean, timestamped record of every communication and maintenance request stops being nice-to-have and becomes essential evidence.

    Compliance software and the Section 8 paper trail

    Under the reformed regime, if a landlord wants possession on grounds such as repeated rent arrears or anti-social behaviour, they need a credible evidence file. This is where dedicated compliance software earns its keep. Platforms now offer automated logging of rent payment histories, reminder workflows, and structured communication records that can be exported in a format suitable for a First-tier Tribunal.

    The government’s Renters’ Rights Bill documentation makes clear that the evidential standard for Section 8 claims will be closely scrutinised. Landlords relying on email threads and handwritten notes will struggle. Those running a platform that auto-captures and date-stamps every interaction are, at minimum, starting from a much stronger position.

    I’d argue the compliance angle is also where PropTech becomes genuinely interesting for property-adjacent businesses, solicitors, mortgage brokers, and even accountancy practices that service landlord clients. Understanding the operational complexity their clients now face creates a real service opportunity, and it mirrors patterns I’ve written about elsewhere on this blog, such as how UK accountancy practices are using AI to serve more clients without growing headcount, the logic of scaling compliance capability without scaling staff costs applies directly here.

    PropTech for landlords compliance dashboard showing tenancy management features
    Photo by Mikhail Nilov on Pexels

    Digital tenancy management: where the efficiency gains are real

    Beyond compliance, the day-to-day operational gains from proper tenancy management platforms are measurable. Referencing and onboarding a new tenant used to mean physical ID checks, paper guarantor forms, and a file that lived in a drawer. Modern platforms integrate with Open Banking to verify income, pull credit reports automatically, and generate tenancy agreements populated from a template that’s already been updated for the new legislative requirements.

    Goodlord, for example, publishes data showing that digital onboarding cuts the average time-to-tenancy from around two weeks to under five days. For agents running fifty or more properties, that’s not a marginal improvement, it’s the difference between a profitable business and one that haemorrhages staff time on admin.

    Rent collection features are similarly mature. Direct debit integration, automated arrears chasing, and real-time payment dashboards mean agents spend less time on the phone and more time on the work that actually requires human judgement. The private rental sector UK commentary has rightly noted how structurally stressed the sector is right now, tech isn’t a fix for that structural pressure, but it is a genuine operational buffer for businesses that can implement it properly.

    Smaller landlords and the accessibility question

    There’s a fair challenge to the PropTech-as-solution narrative: most of these platforms are priced and designed for agents managing sizeable portfolios. A landlord with two or three properties in Sheffield or Coventry isn’t going to subscribe to an enterprise tenancy platform. The monthly cost doesn’t stack up against the revenue, and the onboarding overhead is real.

    This is changing, slowly. Platforms like Landlord Studio and Hammock are explicitly targeting the self-managing landlord segment with lighter, lower-cost tooling. Landlord Studio offers a free tier that covers basic rent tracking and expense logging, meaningful for a small portfolio. Hammock integrates with bank feeds to auto-categorise landlord expenses, which becomes genuinely useful at tax return time given HMRC’s ongoing push towards Making Tax Digital.

    The regulatory pressure the Renters’ Rights Act creates is, paradoxically, an adoption accelerant for this segment. When the cost of getting it wrong rises, and under the new ombudsman scheme, fines and repayment orders become a live risk, paying £20 a month for a platform that creates an automatic audit trail starts looking reasonable. I’ve seen this dynamic play out before. When data protection enforcement tightened, SMEs that had resisted basic data management tools suddenly found the budget. Legislative deadlines have a way of clarifying priorities.

    What letting agents should be evaluating now

    If you’re running a letting agency and haven’t audited your tech stack in the last twelve months, the checklist is fairly clear. First, check whether your existing platform has been updated for Renters’ Rights Act compliance, specifically, whether it supports Section 8 evidence management and the new tenancy structure that removes fixed terms. Second, assess your communication logging. If your team is still resolving maintenance issues over WhatsApp without any formal log, you’re creating a liability. Third, look at your referencing workflow; anything still involving paper or manual email chains is a candidate for replacement.

    The broader point is that the digital maturity question for letting agencies is now a regulatory question, not just an efficiency one. That framing matters when you’re making the case internally for tech investment. It’s the same argument I find running through sectors like financial services, where FCA Consumer Duty requirements are forcing fintech product teams to document their design decisions in ways that feel unfamiliar but are ultimately non-negotiable. The letting market is arriving at a similar inflection point.

    The firms getting ahead of the curve

    The agencies I’ve spoken to that are genuinely ahead on this tend to share one characteristic: they made the platform decision before the legislative deadline, not after. They had time to train staff, migrate records, and iron out the integration wrinkles without a compliance gun to their head. That lead time is now shorter than it was, but it hasn’t entirely gone. The secondary regulations and the ombudsman scheme’s operational detail are still being finalised, which means there is still a window to implement sensibly rather than reactively.

    PropTech for landlords and agents isn’t a silver bullet. The legislative complexity of the Renters’ Rights Act will still require legal advice, and no platform substitutes for understanding the underlying rules. But the firms treating technology as a core part of their operating model, rather than a bolt-on, are going to find compliance significantly more manageable, and their businesses considerably more resilient, as the dust settles.

    Frequently Asked Questions

    What PropTech tools are most useful for UK landlords under the Renters' Rights Act?

    Platforms like Goodlord, Arthur Online, and Landlord Studio are widely used for tenancy management, compliance record-keeping, and rent collection. The most valuable features right now are automated communication logging and Section 8 evidence management, which are directly relevant to the new possession grounds under the Act.

    How much does PropTech software cost for a small landlord in the UK?

    Costs vary considerably. Landlord Studio offers a free entry-level tier for basic rent tracking. Paid plans across most platforms run from around £10 to £30 per month for small portfolios, scaling upwards for larger agent-focused products. Given the potential cost of non-compliance under the new ombudsman scheme, the ROI case is stronger than it looks at first glance.

    Does PropTech actually help with Renters' Rights Act compliance, or is it just admin software?

    Modern platforms do more than basic admin. They generate structured audit trails, timestamped communication logs, and exportable evidence files that are directly useful in First-tier Tribunal proceedings. Several have also updated their tenancy agreement templates to reflect the removal of fixed terms and the abolition of Section 21.

  • FCA Consumer Duty and Fintech Product Design: What UK Founders Building for Retail Customers Must Get Right

    FCA Consumer Duty and Fintech Product Design: What UK Founders Building for Retail Customers Must Get Right

    If you are building a consumer-facing fintech product in the UK right now, the FCA Consumer Duty framework is not background noise. It is the operating environment. Since it came into full force for open products and services in July 2023, the rules have reshaped how regulated firms think about everything from the wording on a pricing page to the flow of an onboarding screen. For early-stage founders, understanding this is not just a compliance exercise. It is a product discipline that, done properly, makes your offering genuinely stronger.

    Fintech team reviewing FCA Consumer Duty product design decisions on screen
    Photo by Ivan S on Pexels

    I have spoken to a number of founders who treat Consumer Duty as something to hand off to a compliance consultant. That is understandable, especially when you are stretched thin. But the FCA has been explicit: this is not a tick-box exercise. The regulator expects firms to demonstrate that good outcomes for retail customers are embedded into product decisions from the beginning, not retrofitted before an audit. That shift in posture has real consequences for how you design, price, communicate, and onboard.

    What the four outcomes actually mean for product teams

    The FCA Consumer Duty is structured around four outcomes: products and services, price and value, consumer understanding, and consumer support. Each one has a direct translation into product design choices, and founders often underestimate how granular the expectations are.

    The products and services outcome requires that whatever you build is appropriate for the market you have identified. That sounds obvious, but the FCA expects documented evidence of target market assessments. If your credit product is being taken out primarily by people in financial difficulty, and your original target market assessment said otherwise, that is a problem. You need the data to show you are monitoring who is actually using the product, not just who you intended to use it.

    Price and value is where many fintech founders get caught out. The FCA is not capping prices, but it expects firms to demonstrate a rational relationship between what customers pay and what they receive. Subscription fee structures with unclear cancellation terms, or products where the headline rate is undercut by ancillary charges, are exactly the kind of thing examiners look for. Build your pricing model so you could explain it plainly to a customer who had never heard of your brand and have it still look fair.

    Consumer understanding: the communication standard you are actually being held to

    This is the outcome that touches your marketing copy, your app notifications, your email sequences, and your in-product messaging. The FCA is not asking whether your communications are technically accurate. It is asking whether a typical customer in your target market would genuinely understand the material implications of what you are offering.

    That distinction matters enormously. Terms and conditions that are legally complete but practically incomprehensible do not satisfy Consumer Duty. Neither does a risk warning buried in a font size that most people will skip. The FCA’s own Consumer Duty guidance references the concept of a “typical retail customer” repeatedly, and the bar for what that person can reasonably be expected to understand is deliberately conservative.

    My view is that the communication standard is actually the area where strong product teams have the most opportunity to differentiate. If your competitors are hiding fees in footnotes and your onboarding is genuinely transparent, that is a commercial advantage, not just a compliance benefit. Write for a person who is unfamiliar with financial products and you will likely write better copy for everyone.

    Mobile app onboarding flow designed to meet FCA Consumer Duty fintech product design standards
    Photo by Geri Tech on Pexels

    Onboarding design under Consumer Duty

    Onboarding is where Consumer Duty theory collides with product reality most sharply. The FCA expects that customers are given information at the right moment, in a format that supports a genuine decision, and that the onboarding process does not use design patterns that exploit cognitive biases or rush users past material information.

    Dark patterns are explicitly in scope. Pre-ticked boxes for upsells, countdown timers on decisions that have no genuine time constraint, and default settings that favour the firm over the customer are all the kind of thing Consumer Duty was designed to address. If you have inherited these patterns from an earlier version of your product, now is the time to audit them. The FCA has made clear it will look at the whole customer journey, not just the product documentation.

    Practically, this means your onboarding flow should be tested with real users from your target market before you scale. Not usability testing in the narrow sense, but comprehension testing: can someone who has never used your product explain back to you what they have just signed up for? If they cannot, you have a Consumer Duty exposure before a single customer complains.

    Vulnerable customers and how to design for them without patronising anyone

    The FCA has published detailed guidance on vulnerable customers, and Consumer Duty amplifies those expectations significantly. Firms must consider how customers experiencing temporary or permanent vulnerabilities interact with their products, and make reasonable adjustments. For most fintech founders, this is less about building entirely separate product tracks and more about applying good design principles consistently.

    Readable font sizes, plain language, accessible colour contrast, clear exit routes from any process, and the ability to access human support when automated journeys fail: these are the practical basics. A customer going through a bereavement who needs to close an account should not hit a wall of automated responses. That scenario is not hypothetical; it is exactly the kind of case the FCA uses when examining consumer support outcomes.

    If you are fundraising, I would also flag that institutional investors increasingly ask about Consumer Duty compliance frameworks alongside their standard due diligence. It has become part of the governance conversation, particularly at Series A and beyond. Getting your house in order early is not just about avoiding enforcement action; it affects your cap table conversations too. For context on how the regulatory picture shapes fintech investment, the article on what FCA Consumer Duty really means for fintech startups covers some of the broader dynamics worth understanding.

    Building evidence of good outcomes, not just good intentions

    The FCA Consumer Duty framework requires firms to monitor and evidence outcomes on an ongoing basis. That means data. You need to be tracking metrics that tell you whether customers are achieving the outcomes they should be: are they understanding the product? Are they using features that serve their interests? Are they exiting at points that suggest confusion or dissatisfaction?

    Many founders I speak to have strong product analytics on engagement and retention but weaker data on whether customers are actually better off for having used the product. Those are different questions. Building that measurement layer in now is far less disruptive than trying to retrofit it when the FCA sends a data request.

    Documentation matters too. Your board or senior manager responsible for Consumer Duty (under the Senior Managers and Certification Regime, someone must own it) should be receiving regular MI that covers outcomes, not just operational metrics. If you cannot produce that documentation, you cannot demonstrate compliance, regardless of how well your product actually performs.

    The broader principle here mirrors what I have seen in other compliance-heavy areas: firms that build rigour into process early spend far less time and money on remediation later. It is the same logic that drives good financial record-keeping or, for businesses operating across different sectors, using specialists like Asbestos Compliance Solutions rather than cutting corners on regulatory obligations. The cost of getting it right upfront is always lower than the cost of getting it wrong at scale.

    If you are building a new fintech product and want a useful cross-reference for how consumer-facing financial communication is evolving alongside the regulatory landscape, the earlier piece on FCA Consumer Duty rules for fintech and financial software businesses covers the software-specific angle in more detail.

    Frequently Asked Questions

    Does FCA Consumer Duty apply to early-stage fintech startups without full authorisation?

    Consumer Duty applies to all FCA-authorised firms, including those with limited or interim permissions. If you are operating under an Appointed Representative arrangement, the principal firm carries primary Consumer Duty responsibility, but that does not mean you can ignore the framework. The FCA expects that products distributed through AR models also meet the four outcomes.

    What counts as a 'dark pattern' under Consumer Duty and how do I know if my product has one?

    The FCA considers a design pattern a problem if it nudges customers towards decisions that benefit the firm at the customer’s expense, particularly through manufactured urgency, obscured exit routes, or misleading defaults. Review your onboarding flow, upsell screens, and cancellation journey specifically. If any step would look manipulative to a regulator watching over your customer’s shoulder, treat it as a Consumer Duty risk.

    How should fintech founders document Consumer Duty compliance for the FCA?

    You need a Consumer Duty implementation plan, a target market assessment for each product, regular board-level reporting on consumer outcomes, and records of how product and communication decisions were made with good outcomes in mind. The FCA can and does request this documentation during supervisory reviews, so it needs to be current, not retrospective.

    What happens if the FCA finds a fintech firm has breached Consumer Duty?

    Enforcement options include requirement variations, public censure, financial penalties, and in serious cases, suspension or cancellation of permissions. The FCA has also made clear it expects firms to self-identify issues and remediate proactively. A firm that waits for a complaint before acting will be viewed much less favourably than one that identifies a gap and fixes it before customers are harmed.

  • Why UK Founders Are Choosing Revenue-Based Financing Over Traditional Bank Loans in 2026

    Why UK Founders Are Choosing Revenue-Based Financing Over Traditional Bank Loans in 2026

    If you are running a fast-growing UK business and you need capital, the old playbook said go to your bank, present three years of accounts, and hope for the best. Many founders I speak to have tried exactly that in 2026 and walked away empty-handed, or worse, with an offer tied to a personal guarantee on their home. Revenue-based financing has moved firmly into the mainstream as an alternative, and the comparison with traditional lending is worth laying out properly, without the hype from either camp.

    UK founders reviewing revenue-based financing options in a modern office
    Photo by RDNE Stock project on Pexels

    What revenue-based financing actually is

    Revenue-based financing (RBF) is a funding arrangement where a lender advances a lump sum in exchange for a percentage of your monthly revenue until a fixed repayment cap is reached. That cap is typically 1.3x to 1.5x the original advance. If your revenue drops in a slow month, your repayment drops proportionally. If you have a strong quarter, you clear the balance faster.

    There is no equity involved. No dilution, no cap table complications, no investor seat at the board table. For founders who have spent time thinking carefully about how to protect their financial position as they grow, that distinction matters enormously. You are essentially selling a portion of future revenue, not a slice of the company.

    UK providers in this space include Uncapped, Clearco (operating in the UK market), and a growing cohort of fintech lenders who have built underwriting models around open banking and real-time revenue data rather than lagging credit files.

    How high-street bank lending actually works in practice

    High-street lenders in the UK, the major ones being Barclays, Lloyds, NatWest, and HSBC, broadly assess business loan applications against a combination of trading history, credit score, profitability, and security. For smaller businesses, that security frequently means a personal guarantee, which puts the director’s personal assets on the line if the business cannot service the debt.

    The process is slow. Applications can take six to twelve weeks. Approval rates for SMEs without tangible assets as collateral remain stubbornly low. According to the British Business Bank’s Small Business Finance Markets report, a significant proportion of smaller firms either receive less than they requested or are declined outright, and many simply stop applying because they expect rejection.

    For a SaaS business or a digital-first brand with strong monthly recurring revenue but limited physical assets, the high-street model is structurally misaligned. These businesses have cash flow, not buildings.

    The Growth Guarantee Scheme and what replaced CBILS

    The Coronavirus Business Interruption Loan Scheme ran its course and was replaced by the Recovery Loan Scheme, which itself evolved into the Growth Guarantee Scheme from 1 July 2024. Under this scheme, the government provides a partial guarantee to lenders, reducing the lender’s risk and theoretically making capital more accessible to viable businesses that lack conventional security.

    In practice, it helps. The partial government guarantee does take the edge off personal guarantee requirements in some cases, and interest rates are more competitive than unsecured commercial lending. But the scheme still runs through accredited lenders who apply their own credit criteria on top of the government guarantee. You are still submitting accounts, still going through credit checks, and still waiting weeks for a decision. For a founder who needs £150,000 within the month to fund a product launch or hire a key team, that timeline is a real constraint.

    The real comparison: speed, cost, and what you give up

    Let me put the three options side by side on the dimensions that matter most to a growth-stage founder.

    Speed: RBF providers routinely give decisions in 24 to 72 hours once you connect your accounts via open banking. High-street loans take weeks. Growth Guarantee Scheme applications through accredited lenders sit somewhere in between, but rarely under two weeks.

    Cost: This is where RBF gets scrutinised, rightly. A 1.4x repayment cap on a £100,000 advance means you pay back £140,000. How expensive that is depends entirely on how quickly you repay. If you clear it in six months, the annualised rate is high. If your revenue grows and you clear it in three months, the effective cost looks different again. High-street loans and Growth Guarantee Scheme facilities will generally carry lower headline interest rates, but factor in arrangement fees, the opportunity cost of waiting, and the risk premium baked into a personal guarantee, and the comparison is less clear-cut than it first appears.

    What you give up: With RBF, nothing structural. No equity, no directorial liability. With a bank loan, potentially a personal guarantee. With an equity round, a percentage of your company permanently. For founders who have already thought through what an eventual exit looks like and what impacts the final payout, the equity question is not abstract.

    Which businesses RBF actually suits

    RBF is not a universal solution. It works well for businesses with predictable, recurring, or high-frequency revenue. E-commerce brands with strong repeat purchase rates, SaaS businesses with monthly subscription income, and digital agencies with retainer-heavy client books are natural fits. The underwriting model depends on seeing consistent revenue data; without that, providers cannot calculate what a sustainable repayment percentage looks like.

    It works less well for capital-intensive manufacturing businesses, early-stage pre-revenue startups, or businesses with lumpy, project-based income where three months of strong revenue might be followed by two quiet ones. For those businesses, a structured term loan or even a carefully constructed equity raise might be the more sensible path. If you are also weighing up how your capital structure interacts with your broader financial position as an owner, the thinking in our piece on Business Asset Disposal Relief in 2026 is worth reading alongside this.

    Practical considerations before you apply

    Before approaching any RBF provider, get your revenue data clean and accessible. Most providers will want to connect directly to your Stripe, Xero, or banking data via open banking. The cleaner your records, the faster the decision.

    Understand the repayment percentage being proposed and model it against your monthly revenue at current levels and at a reduced level. RBF is designed to flex, but if your revenue drops sharply and stays low, the total repayment period extends, and that has cash flow implications across the rest of your operations.

    Check whether the provider is FCA authorised. Not all RBF providers operating in the UK are regulated in the same way, and given the regulatory environment for lending products, it is worth confirming how the product is classified before you sign anything. The FCA register is publicly searchable at fca.org.uk.

    My overall read of the market in 2026 is that RBF has earned its place as a legitimate third route alongside debt and equity. For the right business, it is faster, structurally cleaner, and commercially rational. The founders who use it well are the ones who go in with a clear plan for what the capital will do and a realistic model of how quickly their revenue can absorb the repayment.

    Frequently Asked Questions

    What is revenue-based financing and how does it differ from a business loan?

    Revenue-based financing provides a lump sum in exchange for a fixed percentage of your monthly revenue until a predetermined repayment cap is reached. Unlike a traditional loan, there is no fixed monthly payment, no interest rate in the conventional sense, and typically no personal guarantee or collateral required.

    How much does revenue-based financing cost compared to a bank loan?

    RBF providers charge a flat fee expressed as a repayment cap, typically 1.3x to 1.5x the amount advanced. The effective annual cost depends on how quickly you repay. High-street bank loans carry lower headline rates but often include arrangement fees, slower access to funds, and in many cases a personal guarantee that carries its own financial risk.

    Do I need to give up equity to access revenue-based financing?

    No. Revenue-based financing is not equity financing. You retain full ownership of your business and there is no cap table impact. The lender’s return comes solely from the revenue repayment arrangement, not from a shareholding.

    Is revenue-based financing available to all UK businesses?

    It suits businesses with consistent, measurable revenue such as SaaS companies, e-commerce brands, and retainer-based agencies. Pre-revenue startups, highly seasonal businesses, or those with very lumpy income tend not to qualify, as the underwriting relies on stable revenue data to set a sustainable repayment percentage.

  • How to Use Companies House and HMRC Data to Benchmark Your Business Against UK Competitors

    How to Use Companies House and HMRC Data to Benchmark Your Business Against UK Competitors

    Most UK business owners have a rough sense of how they compare to their competitors. Gut feel, the odd conversation at an industry event, a glance at a rival’s website. But gut feel is not a strategy, and there is a substantial amount of hard financial data sitting in public registries that most founders and finance leads simply never look at. If you want to benchmark business competitors UK Companies House data is your starting point, and it costs nothing to access.

    I’ve spent time digging through filings for clients across professional services, technology, and manufacturing sectors, and the intelligence you can extract, legally and for free, is genuinely underestimated. Here is a practical guide to doing it properly.

    Business analyst reviewing Companies House filings to benchmark business competitors UK
    Photo by https://kaboompics.com/ on Pexels

    What data is actually available at Companies House?

    Every company incorporated in England, Wales, Scotland, or Northern Ireland must file accounts with Companies House. The depth of information depends on the company’s size classification, which is where many people get tripped up.

    Small companies (turnover under £10.2 million, fewer than 50 employees) can file abbreviated or micro-entity accounts. These show net assets and a very limited balance sheet, but no profit and loss. Medium companies (turnover under £36 million, up to 250 employees) must file a full profit and loss account. Large companies and public limited companies file full statutory accounts including detailed notes on headcount, remuneration, and segmental performance.

    So if your direct competitors are small companies filing micro-entity accounts, your intelligence will be limited to their net assets and overall financial health. If they are medium or large, you can see turnover, gross profit, operating profit, and cost structures. The trick is knowing which competitors are worth pulling filings for and cross-referencing what is there.

    How to find and read the right filings

    The Companies House search service lets you search by company name or number. Pull up the filing history for each competitor you want to examine, then download the most recent full accounts PDF. Pay attention to the filing date: accounts can be filed up to nine months after the year end for private companies, so you may be looking at data that is over a year old by the time you read it.

    Once you have the accounts, focus on three areas. First, turnover and gross profit, which gives you a comparable revenue figure and gross margin. Second, administrative expenses and operating profit, which reveals cost structure efficiency. Third, staff costs and average headcount, which are almost always disclosed in the notes and allow you to calculate revenue per employee. That last metric is particularly useful for services businesses.

    A practical workflow I tend to recommend is building a simple spreadsheet with one row per competitor and columns for: financial year end, turnover, gross profit margin, operating profit margin, headcount, revenue per head, and net assets. Once you have three or four competitors mapped out alongside your own figures, patterns become obvious quickly.

    Going further: using HMRC data and ONS benchmarks

    Companies House filings give you competitor-specific data. To put that data in broader context, you need sector-level benchmarks. HMRC publishes detailed corporation tax statistics and UK trade statistics broken down by industry. The Office for National Statistics publishes annual business surveys covering turnover, employment, and output by sector code (SIC code). If you are already using ONS datasets to inform business decisions, this is a natural extension of the same habit. I wrote previously about how to use ONS economic data to make smarter business decisions without a research team, and the approach applies directly here.

    The combination is powerful. ONS data tells you what a typical business in your sector looks like. Companies House filings tell you what specific named competitors look like. You can then position yourself relative to both: are you above or below sector average gross margin, and are you above or below the specific firms you actually compete with for contracts or customers?

    Tools that make the process faster

    Manual PDF analysis is fine for a handful of competitors, but it does not scale. Several tools aggregate Companies House data into searchable dashboards. Beauhurst, Fame (from Bureau van Dijk), and Creditsafe all offer company financial data with filtering and export functions. These are paid products, but even a short subscription can save hours of manual work if you are benchmarking across a larger peer group.

    For a free alternative, the Companies House API allows you to pull filings programmatically if you have any technical resource available. The API documentation is thorough, and for a developer it is a straightforward integration. If you are building an internal knowledge base for your business, this kind of structured competitive data belongs in it. Maintaining a living reference of competitor financials, updated each time new filings drop, is far more useful than a one-off snapshot. The case for building internal knowledge bases to reduce reliance on individual staff members is directly relevant here: institutional competitive intelligence should not live only in one person’s head or a forgotten spreadsheet.

    Honest limitations you need to account for

    There are real constraints to acknowledge. Filing dates mean data lags. Accounting policies vary between companies, which means gross margin figures are not always directly comparable, particularly where companies capitalise software development costs or treat certain expenses differently. Group structures can obscure individual trading entity performance. And as noted, smaller competitors filing micro-entity accounts give you very little to work with.

    You also cannot see cash flow from operations in many cases, which limits your view of liquidity. Net profit in filed accounts is after tax and often after director remuneration adjustments, so be cautious about drawing conclusions on profitability without understanding the underlying structure. This is where reading the notes to the accounts, not just the face of the statements, makes a real difference.

    How to act on what you find

    The point of this exercise is not curiosity. It is decision-making. If your gross margin is 38% and the two closest named competitors are running at 47% and 52%, that is a meaningful signal. It might mean your pricing is too low, your cost of sales is higher than it should be, or your service mix is different. Any of those warrants investigation.

    If a competitor’s revenue per employee is significantly higher than yours, that is a productivity question worth examining. Are they more automated? Do they have a different service tier? Are they simply charging more? Similarly, if a competitor’s headcount grew by 40% in one filing year, that tells you something about where they are investing and which markets they are moving into.

    Finance leads can bring this analysis into quarterly business reviews as a standing agenda item. Founders can use it to calibrate investor conversations: being able to say your gross margin is in the top quartile for your sector, with specific comparable company data to support it, is a materially stronger position than a general assertion. And if you are managing the security and digital posture of your business alongside this kind of data work, keeping that competitive intelligence properly protected matters too. The guidance on auditing your business’s digital security posture without a specialist firm is worth reading alongside this.

    Public data is not the whole picture, but used properly, it gives UK business owners a grounded, evidence-based view of where they sit in their market. That is a significant advantage over running on instinct alone.

    Frequently Asked Questions

    Is it legal to use Companies House data to benchmark competitors?

    Yes, completely. Companies House filings are public records and anyone can access, download, and analyse them. There are no restrictions on using this data for commercial analysis or competitive intelligence purposes.

    What financial information can I see in a competitor's Companies House accounts?

    This depends on company size. Medium and large companies must file full profit and loss accounts including turnover, gross profit, operating profit, and headcount. Small and micro-entity companies can file abbreviated accounts, which may only show net assets and a limited balance sheet without revenue or margin detail.

    How up to date is the financial data on Companies House?

    Private limited companies have up to nine months after their financial year end to file accounts. This means the most recent filing for a competitor with a December year end might not appear until September the following year, so the data can be 12 to 18 months old by the time you read it.

  • How UK Accountancy Practices Are Using AI to Serve More Clients Without Growing Headcount

    How UK Accountancy Practices Are Using AI to Serve More Clients Without Growing Headcount

    The economics of running an accountancy practice in 2026 are under real pressure. Clients expect faster turnaround. HMRC’s Making Tax Digital expansion keeps broadening the compliance surface. And the pool of qualified staff willing to sit and process routine bookkeeping has shrunk considerably. I’ve spoken with partners at several mid-size practices across the UK over the past year, and the pattern is consistent: they’re not growing headcount to absorb the extra volume. They’re deploying AI tools for UK accountancy practices instead, and the results are genuinely changing how these firms operate day to day.

    This isn’t about replacing accountants. It’s about what happens when the two or three hours a day spent on low-stakes, repeatable tasks get handed to software. Suddenly a qualified member of staff can focus on the advice that actually justifies their salary.

    Accountant reviewing AI tools for UK accountancy practices on a dual-monitor setup
    Photo by Mikhail Nilov on Pexels

    Where AI is actually being used in practice

    The headline use case right now is bookkeeping review. Platforms like Dext, Xero, and QuickBooks have all added AI-assisted categorisation and anomaly flagging, which means a bookkeeper’s job shifts from data entry to exception handling. The AI processes the transaction feed, flags anything that looks inconsistent with prior periods or VAT treatment rules, and the human reviews a shortlist rather than an entire ledger. For firms handling 80 or more monthly bookkeeping clients, this alone changes the economics substantially.

    Draft client correspondence is the second area. Several practices are using large language model tools, either built into their practice management software or accessed via API, to generate first drafts of routine letters: tax computation cover notes, queries to clients about missing information, reminders ahead of self-assessment deadlines. The drafter reviews and adjusts; they don’t start from scratch. I’d estimate a competent drafter with AI assistance can handle roughly twice the correspondence volume compared to writing from a blank page. The Institute of Chartered Accountants in England and Wales (ICAEW) has published guidance on AI use in practice, including practical considerations around client communication, which is worth reading before committing to any tool in production.

    Automated client reporting is the third pillar. Management account packs, cashflow summaries, and KPI dashboards that used to take a bookkeeper half a day to assemble can now be scheduled and auto-generated from connected data sources. The partner reviews the output; the assembly itself is handled by the software.

    How the software stack is shifting

    Most practices aren’t replacing their core systems. They’re layering AI capability on top of what they already run. The typical stack I see now involves a cloud accounting platform at the centre (Xero dominates among SME-focused UK practices, with Sage still holding significant ground in mid-market), practice management software like Iris or Karbon handling workflow and billing, and then a specialist AI layer sitting across the top.

    That AI layer might be a dedicated tool like Caseware or MindBridge for audit-adjacent work, or it might be a more general-purpose assistant integrated into the firm’s existing software via an API connection. Some smaller practices are using Microsoft Copilot within their existing Microsoft 365 environment, which keeps the learning curve low. The key question is always whether the AI output can be audited clearly, meaning the firm can show exactly what the software produced and what the human changed before it went to the client.

    This is where the internal knowledge base becomes relevant for accountancy firms. Practices that have documented their house style for client communications, their standard VAT treatment logic, and their quality review checklists find it far easier to configure AI tools effectively. The software needs guardrails, and those guardrails come from well-maintained internal documentation. Firms without that discipline tend to get AI output that’s technically acceptable but inconsistent, which creates more review work than it saves.

    Team reviewing AI-generated client reports as part of accountancy practice workflow
    Photo by Mikhail Nilov on Pexels

    Professional liability: the part nobody wants to talk about

    Professional liability is where I think the conversation genuinely needs to sharpen up. When an AI tool drafts a letter that contains incorrect tax advice, or flags a transaction as low-risk when it should have been queried, the professional responsibility sits with the regulated firm, not the software vendor. This is not a new principle; it’s the same framework that applies when a junior member of staff makes an error. But AI errors can be systematic in a way that human errors aren’t. A misconfigured categorisation rule might propagate across every client in a portfolio before anyone notices.

    ICAEW members are expected to maintain professional scepticism and apply judgement to AI-generated outputs. That means firms need a documented review process for anything AI produces before it touches a client. Some practices are implementing a two-stage sign-off: the AI generates, a qualified person reviews, and a second qualified person spot-checks. That sounds cumbersome on paper, but in practice the AI handles the volume so the qualified reviewers are working through a curated shortlist rather than processing everything from scratch.

    Professional indemnity insurers are paying attention too. My understanding is that several UK PI insurers are now asking practices to declare their AI usage as part of the renewal process. Firms that cannot articulate their review controls may find that affects their terms. It’s worth speaking to your broker before your next renewal if AI tools are part of your workflow and that hasn’t been declared.

    The online presence side: making the efficiency gains visible to clients

    There’s a commercial dimension to this that practices sometimes overlook. If your firm is now capable of faster turnaround, more proactive reporting, and cleaner communication because of AI-assisted workflows, clients won’t automatically know that unless you tell them. This is where how a firm presents itself online starts to matter. A practice whose website looks like it was last updated in 2019 is not projecting the same confidence as the efficiency gains its software stack now allows. Firms increasingly recognise that their web design and digital marketing need to reflect the quality of service they’re actually delivering. Based in Mansfield, Nottinghamshire, dijitul supplies web design, SEO, and hosting services to businesses that want their online presence to match their operational capability. For an accountancy practice investing in software and business efficiency, having a website that communicates that professionalism is part of the same investment logic. The plain-text domain is dijitul.uk if you want to look at what they offer.

    It’s a point I’d make to any practice principal: the AI-driven efficiency story is genuinely compelling to prospective clients. A firm that can explain, clearly on its website, how it uses technology to deliver faster, more accurate work has a real differentiator. That message needs to be on the homepage, not buried in a blog post. Firms that work with a digital agency on their marketing and web presence to articulate that software-led value proposition tend to find it converts better than generic “we care about your business” copy.

    What practices should check before going further

    For firms still assessing whether to expand their AI tooling, a few practical checks are worth working through. First, data governance: does the AI tool process client data on UK or EU servers, and what does the vendor’s data processing agreement say? GDPR obligations don’t disappear because you’re using software. Second, output auditability: can you export a clear record of what the AI produced versus what a human modified? Third, staff training: there’s no point deploying a tool if the team using it doesn’t understand its limitations.

    Practices that have already been through the process of auditing their digital security posture tend to find this assessment easier, because they already have a structured way of thinking about what software touches client data and what controls are in place. If that work hasn’t been done, it’s worth doing it alongside any AI adoption project rather than after.

    The firms getting the most from AI tools for UK accountancy practices right now are the ones that treated implementation as a process project, not a software purchase. They mapped their workflows first, identified where the highest-volume repeatable tasks sat, configured the tools around those specific tasks, and built review checkpoints in from the start. The technology is genuinely capable. Whether a practice benefits from it depends almost entirely on the discipline around how it’s deployed.

    Frequently Asked Questions

    Which AI tools are UK accountancy practices actually using in 2026?

    The most common tools are AI-assisted features within existing platforms like Xero, Dext, and QuickBooks, alongside practice management software such as Karbon and Iris that have integrated AI drafting and workflow automation. Some firms are also using Microsoft Copilot within their Microsoft 365 environment for general correspondence drafting and summarisation.

    Is an accountancy firm liable if AI-generated advice turns out to be wrong?

    Yes. The professional liability sits with the regulated firm, not the software vendor. ICAEW guidance makes clear that qualified accountants must review and apply professional judgement to any AI-generated output before it reaches a client. A documented review and sign-off process is essential to demonstrate due diligence.

    Do UK professional indemnity insurers need to know if a practice is using AI?

    Many UK PI insurers are now including AI usage questions in their renewal processes. Practices that have not declared AI use and cannot demonstrate adequate review controls may face complications at renewal. It’s advisable to speak to your broker before your next renewal and document your AI governance procedures clearly.

  • How UK Businesses Are Using Internal Knowledge Bases to Reduce Dependency on Key Staff

    How UK Businesses Are Using Internal Knowledge Bases to Reduce Dependency on Key Staff

    Every business has them: the people who just know things. The project manager who holds the entire client relationship in her head. The IT lead who’s the only one who understands how the servers are configured. The operations director who built half the processes from scratch and documented precisely none of them. When those people leave, or are off sick for a fortnight, the cracks appear fast. Building a solid internal knowledge base is one of the most practical things a UK business can do to fix this, and yet it’s still treated as a nice-to-have rather than a strategic asset.

    Team reviewing an internal knowledge base UK business documentation system on a shared screen
    Photo by Yan Krukau on Pexels

    What an internal knowledge base actually is

    An internal knowledge base is a structured, searchable repository of everything your business needs to operate without relying on individuals to be present. Think process documentation, onboarding guides, decision-making frameworks, supplier contacts, compliance checklists, template libraries, and institutional memory. It’s not a shared drive full of unnamed Word documents from 2019. Done properly, it’s a living system that people actually use and update.

    The distinction matters. A Google Drive folder or a cluttered SharePoint library is not a knowledge base. A knowledge base has taxonomy, version control, ownership, and a culture of contribution. Tools like Notion, Confluence, Slite, and Guru are popular in the UK market, each with different strengths depending on your team size and workflow. The tool is secondary, though. The structure and the habits around it are what determine whether it works.

    The real cost of not having one

    The hidden costs of poor internal communication compound quickly when there’s no central source of truth. According to the Department for Business and Trade, SME productivity remains a persistent challenge across the UK, and a significant portion of that is attributable to time wasted searching for information, repeating questions, or relearning processes that were already figured out by someone who’s since moved on.

    I’ve spoken to founders who’ve lost months of operational momentum after a single senior departure. One consultancy director told me she spent her first three months in post essentially reverse-engineering decisions her predecessor had made verbally and never recorded. That’s not an unusual story. It’s practically a rite of passage. A well-structured internal knowledge base for a UK business doesn’t eliminate that transition cost entirely, but it reduces it dramatically.

    How to build a knowledge base that people actually use

    The failure mode for most internal wikis is abandonment. Someone enthusiastic builds it out, the team uses it briefly, then it becomes stale and nobody trusts it. Here’s how to avoid that.

    Start with the highest-risk processes

    Rather than trying to document everything at once, identify your single points of failure. Who would the business struggle most without? What processes live entirely inside one person’s head? Start there. Map those processes first, get them reviewed by at least one other person who can validate accuracy, and then expand outward. This gives you immediate operational value rather than a sprawling wiki that takes months to build before it delivers anything.

    Assign ownership, not just authorship

    Every article or process document in your knowledge base should have a named owner responsible for keeping it current. This isn’t about blame; it’s about accountability. Quarterly reviews are usually enough for stable processes. If something changes in the business, a supplier relationship, a regulatory requirement, a software tool, the owner updates the relevant entry. Without this, your knowledge base becomes a museum rather than a resource.

    Write for the person who knows nothing

    This is the hardest discipline to instil. Experts naturally skip steps they consider obvious. The entire point of documentation is to make those steps visible. A useful test: ask a new hire to complete a task using only the documentation. Where they get stuck is exactly where the documentation needs work.

    Professional documenting processes for an internal knowledge base UK business system
    Photo by RDNE Stock project on Pexels

    Knowledge management in specialist and compliance-heavy sectors

    The need for structured knowledge management becomes especially acute in sectors where regulatory compliance is non-negotiable. Construction and specialist services are a clear example. Businesses operating in asbestos services, building surveys, or construction compliance face a dense web of legal obligations, and when the person who understands those obligations walks out the door, the exposure can be significant. Asbestos Compliance Solutions Ltd, based in Mansfield, Nottinghamshire and operating across the Newcastle region, handles asbestos specialist services including surveys, testing, and management planning across construction and building projects (asbestoscompliancesolutions.co.uk). Firms operating in this space often develop detailed internal knowledge bases precisely because the regulatory and safety knowledge held by individual surveyors is so consequential, losing it informally is not an option when asbestos and building compliance are involved.

    The principle applies to any business with specialist knowledge at its core. If the only person who understands your compliance obligations is the one due to retire next year, that’s not a personnel issue. It’s a governance risk.

    Connecting onboarding to your knowledge base

    One of the most immediate returns from a well-built internal knowledge base is faster, more consistent onboarding. When UK professionals managing information overload have a structured system to refer to, new starters don’t need to spend their first few weeks extracting tribal knowledge from colleagues who are already busy. They can read, explore, and ask targeted questions rather than generic ones.

    A good onboarding structure in a knowledge base typically includes: a company overview and values section, role-specific process guides, a glossary of internal terminology and tools, a directory of who-does-what, and a curated reading path for the first 30, 60, and 90 days. The last part is often overlooked. Rather than pointing someone at the entire wiki and wishing them luck, a staged reading path reduces cognitive load and helps the new hire feel orientated rather than overwhelmed.

    Governance, permissions, and keeping it secure

    An internal knowledge base also needs basic governance. Not everything should be visible to everyone, client-sensitive documents, board-level strategy, and personnel information should sit behind appropriate access controls. Most modern knowledge base tools offer role-based permissions, and it’s worth spending an afternoon setting these up properly rather than discovering a sensitive document was publicly visible inside your tool six months later.

    This connects directly to broader information security hygiene. If you’re in the process of auditing your business’s digital security posture, your internal knowledge management system should be part of that review. Who has admin access? Are former employees’ accounts deactivated? Is sensitive process documentation duplicated somewhere less secure?

    Making it a habit, not a project

    The businesses that get lasting value from an internal knowledge base treat documentation as part of how work gets done, not an extra task after the work is finished. Some teams build a brief documentation step into every project close-out. Others run monthly sessions where team members update their process pages together. Some use structured templates so that the barrier to contribution is low, fill in the fields, don’t write an essay.

    My take is that the cultural piece matters more than the tool choice. A well-disciplined team can build an excellent knowledge base in Notion for free. A disorganised team will let a Confluence instance with a £20,000 annual licence gather dust. The technology doesn’t create the habit; leadership does.

    In specialist sectors, this is even more visible. Asbestos Compliance Solutions Ltd and firms like it in the Mansfield and Newcastle building and construction space often operate with small, highly skilled teams where each person carries a disproportionate share of technical knowledge about asbestos services and site compliance. Embedding documentation into daily workflow rather than treating it as an occasional exercise is what keeps that institutional knowledge accessible even as teams evolve.

    Building a structured internal knowledge base is not complicated work. It is, however, consistent work. The businesses that start now, even imperfectly, are in a significantly stronger position than those waiting until a departure forces the issue.

    Frequently Asked Questions

    What is an internal knowledge base and how does it differ from a shared drive?

    An internal knowledge base is a structured, searchable system for storing and maintaining business processes, guides, and institutional knowledge. Unlike a shared drive, it has clear taxonomy, version control, and named ownership for each document, making it easier to navigate and trust. A shared drive is typically just a folder structure without any of that governance built in.

    Which tools are best for building an internal knowledge base for a small UK business?

    Popular options for UK SMEs include Notion, Confluence, Slite, and Guru. Notion works well for smaller teams that want flexibility and a low price point; Confluence suits businesses already using the Atlassian suite. The right tool depends less on features and more on what your team will actually adopt and maintain consistently.

    How long does it take to build a useful internal knowledge base?

    A focused team can have a genuinely useful base covering their highest-risk processes within four to six weeks if they prioritise it. The goal is not to document everything at once but to start with the processes where a single departure would cause the most disruption. Value comes early; completeness comes over time.