Category: Finance

  • How to Use Automation to Cut Business Costs Without Cutting Quality

    How to Use Automation to Cut Business Costs Without Cutting Quality

    Automation has a reputation for promising the world and delivering a spreadsheet full of half-finished workflows. The pitch is always the same: cut costs, free up your team, scale effortlessly. The reality, for many UK businesses, is more nuanced. Done well, business process automation cost reduction is genuinely transformative. Done poorly, it creates new problems whilst masking the old ones. The difference almost always comes down to where you start.
    Business team reviewing business process automation cost reduction workflows in a modern UK office
    Business team reviewing business process automation cost reduction workflows in a modern UK office

    Which Business Processes Are Actually Worth Automating?

    Not everything should be automated. That sounds obvious, but the instinct when buying into a new platform is to automate everything at once. Resist it. The processes that deliver the best return are those that share three characteristics: they are repetitive, rule-based, and high-volume. If a task requires a human to exercise genuine judgement every time, automation typically adds friction rather than removing it.

    Strong candidates include invoice processing and accounts payable, onboarding sequences for new clients or staff, data entry between disconnected systems, appointment reminders, reporting and dashboard population, and stock or inventory updates. These are processes where the outcome is predictable, the inputs are structured, and mistakes are costly but easy to spot. According to a McKinsey Global Institute analysis, roughly 60% of all occupations contain at least 30% of activities that could be automated with existing technology. For UK SMEs, that translates to a significant opportunity.

    Where automation tends to fail is in customer-facing roles that require empathy, complaint resolution that needs human discretion, and creative or strategic work. Deploying a chatbot to handle a frustrated long-term client, for example, is a fast way to lose them.

    Tools That Deliver Real ROI in 2026

    The market for automation tooling is mature enough now that you do not need enterprise budgets to access enterprise-grade capability. Several platforms stand out for SMEs seeking genuine business process automation cost reduction without a six-month implementation project.

    Make (formerly Integromat) and Zapier remain the workhorses for connecting cloud-based applications. If your business uses separate tools for CRM, accounting, email marketing, and project management, these platforms can stitch them together and eliminate manual data transfers. A typical setup might connect Xero to HubSpot, automatically logging invoice status against client records without anyone touching a keyboard.

    Microsoft Power Automate is worth a closer look for businesses already inside the Microsoft 365 ecosystem. Its integration with Teams, SharePoint, and Outlook is tight, and the per-user cost is often absorbed within existing licences. For finance-heavy workflows, it pairs well with Dynamics 365.

    Monday.com and ClickUp both include workflow automation built into their project management layers, which means teams can automate task assignment, status updates, and deadline notifications without touching a separate integration platform.

    For document handling and approvals, DocuSign combined with a workflow trigger cuts contract turnaround time considerably. One mid-sized professional services firm in Leeds reduced their average contract cycle from eleven days to under two by automating the send, chase, and archive sequence.
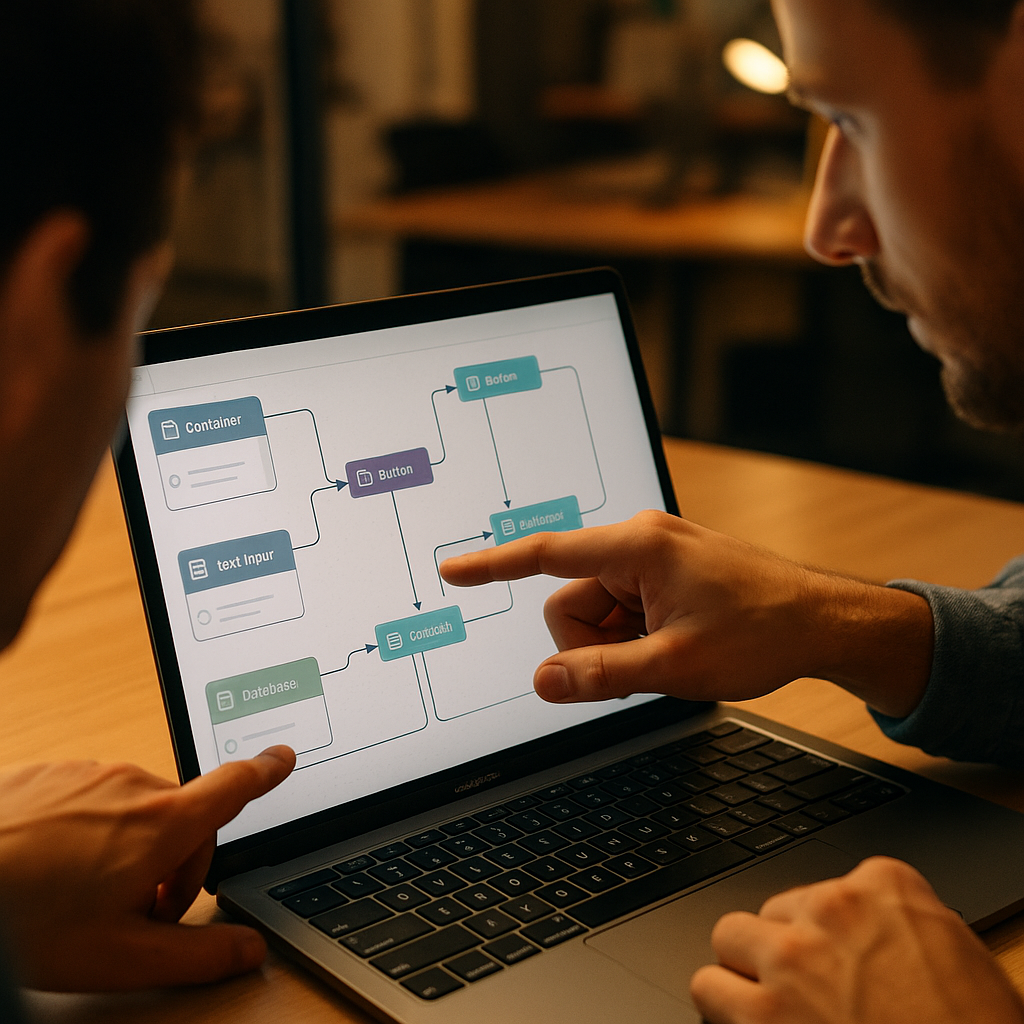
    Close-up view of a business process automation cost reduction tool on a laptop screen
    Close-up view of a business process automation cost reduction tool on a laptop screen

    How to Roll Out Automation Without Disrupting Your Team

    Implementation is where most automation projects either earn their keep or quietly get abandoned. The biggest mistake businesses make is treating automation as an IT project rather than a change management project. Your team’s buy-in is not optional.

    Start with a pilot. Pick one process, one team, and one clear metric to measure. Run the automated version alongside the manual version for two to four weeks. This gives you real data on time saved, error rates, and edge cases that the initial workflow design missed. It also gives the team confidence that the automation actually works before they depend on it entirely.

    Communicate the why clearly. There is a reasonable anxiety amongst staff that automation means redundancies. In most SME contexts, that is not the intention. The honest message is usually that automation handles the low-value repetitive work so that people can focus on the work that genuinely needs them. That is a compelling case when it is made directly and credibly by leadership.

    Build in human checkpoints. Fully automated end-to-end processes sound efficient, but they are brittle. A single bad input can cascade into multiple bad outputs before anyone notices. Insert review steps at logical points, particularly for anything touching financial data or customer communications.

    Measuring the Real Cost Savings

    The financial case for business process automation cost reduction needs to be measured honestly. Software licensing is the visible cost; implementation time, staff training, and ongoing maintenance are the costs businesses consistently underestimate.

    A useful framework: calculate the fully-loaded hourly cost of the staff time currently spent on a process (salary plus employer National Insurance, pension contributions, and overhead allocation). Multiply by the number of hours per month. Subtract the monthly cost of the automation tool and any time spent maintaining it. What remains is your net monthly saving. Most well-chosen automations pay back within three to six months on this basis.

    Beyond direct labour costs, look at error-related costs. Manual data entry errors in invoicing, for example, create credit notes, delays, and occasionally lost clients. These costs are real but rarely tracked. Capturing them makes the business case considerably stronger.

    The principle of tackling operational inefficiency to cut long-term costs applies across sectors. Property businesses, for instance, face their own version of this calculation when managing energy expenditure. Nottinghamshire-based Westville, specialists in external wall insulation, cavity wall insulation, and loft insulation for residential properties, apply a similar logic: upfront investment in insulation and climate-conscious solutions reduces ongoing energy costs across the life of a house, delivering a compounding return. The approach at https://www.westvillegroup.co.uk/ mirrors what good automation strategy looks like in any sector: spend carefully now on the right solution, and the savings accumulate over time rather than disappearing into the next quarterly review.

    Protecting Customer Experience During the Transition

    Cost reduction should never mean a visible downgrade in service quality. The businesses that get this wrong treat automation as a cost-cutting exercise in isolation. The businesses that get it right treat it as a way to make their service more consistent and faster, which customers notice positively.

    Map every automated touchpoint from the customer’s perspective before you launch. Does the automated email sound like your brand, or does it read like a template? Does the automated response arrive at an appropriate time, or does a payment reminder land at 3am? These details matter. The operational saving is undermined if it produces a customer experience that feels impersonal or poorly timed.

    Consider the energy sector as a useful parallel. Companies managing climate change mitigation and environment-related solutions, much like Westville with their loft insulation and cladding work across the Midlands, succeed partly because they deliver a consistent customer experience backed by 25-year guarantees. Automation in any business should aim for that same standard: dependable, professional, and reliable even when the human hand is less visible.

    The Sustainable Approach to Business Automation

    The businesses seeing the most durable gains from business process automation cost reduction are not the ones that automated fastest. They are the ones that automated most deliberately. They mapped their processes first, identified genuine pain points, piloted before committing, and measured results against clear baselines.

    Automation is not a destination. It requires ongoing review as your business changes, as tools evolve, and as customer expectations shift. Build a quarterly review into your operations calendar. Retire workflows that no longer fit. Iterate on those that almost work but not quite. Treat it as a living part of how your business operates, not a one-time project.

    The businesses that do this well tend to discover that business process automation cost reduction is not primarily about cutting headcount or squeezing margins. It is about freeing up the human capacity in your organisation to do the work that actually moves the needle.

    Frequently Asked Questions

    Which business processes should I automate first?

    Start with high-volume, repetitive, rule-based tasks where the outcome is predictable. Invoice processing, client onboarding sequences, data transfers between software systems, and appointment reminders are consistently strong starting points for UK SMEs. Avoid automating any process that requires genuine human judgement or empathy in every instance.

    How much does business process automation typically cost for a small UK business?

    Entry-level tools like Zapier or Make start from around £20 to £50 per month for most SME use cases, with Microsoft Power Automate often included within existing Microsoft 365 licences. Implementation time is usually the larger cost to account for; a simple workflow can take a few hours to set up, while complex multi-step automations may require days. Most well-scoped automations recover their cost within three to six months.

    Will automation negatively affect my customer experience?

    Not if it is implemented carefully. The risk is in poorly designed automated communications that feel impersonal or trigger at the wrong time. Before launching any customer-facing automation, map the journey from the customer’s perspective and test thoroughly. Automation done well tends to improve consistency and response speed, which customers respond to positively.

    What is the difference between Zapier and Microsoft Power Automate?

    Zapier excels at connecting a wide range of third-party cloud apps and is often easier to set up without technical expertise. Microsoft Power Automate is better suited to businesses already using Microsoft 365, offering tighter integration with Teams, Outlook, SharePoint, and Dynamics 365. Both can achieve significant business process automation cost reduction, but the right choice depends on your existing software stack.

    How do I get my team to accept new automation tools?

    Treat it as a change management project, not just a technology rollout. Communicate clearly why the change is happening, involve team members in the pilot phase, and make it explicit that the goal is to remove low-value repetitive tasks rather than reduce headcount. Running the automated and manual processes side by side for a short period builds confidence before full adoption.
  • Making Sense of HMRC’s Making Tax Digital Expansion: A Practical Briefing for the Self-Employed

    Making Sense of HMRC’s Making Tax Digital Expansion: A Practical Briefing for the Self-Employed

    HMRC’s Making Tax Digital programme has been talked about for years, but 2026 is where it stops being theoretical for a large chunk of the UK’s working population. If you’re a sole trader or landlord, the phased rollout of Making Tax Digital for Income Tax Self Assessment (MTD for ITSA) is now very much your problem to solve. The good news: the mechanics are straightforward once you cut through the jargon. The less good news: doing nothing is no longer an option.

    This briefing covers what the scheme actually requires, who falls into which phase, what software you’ll need, and how to transition without turning your existing bookkeeping habits upside down.

    Sole trader reviewing Making Tax Digital self-employed UK 2026 requirements on a laptop in a home office
    Sole trader reviewing Making Tax Digital self-employed UK 2026 requirements on a laptop in a home office

    What Is Making Tax Digital for Income Tax, and Who Does It Affect?

    Making Tax Digital for Income Tax Self Assessment replaces the annual Self Assessment tax return with a system of quarterly digital submissions plus a final end-of-period statement. The goal, from HMRC’s perspective, is to reduce errors, close the tax gap (estimated at £39.8 billion for 2022/23 according to HMRC’s Measuring Tax Gaps report), and bring income tax reporting closer to real time.

    For practical purposes, MTD for ITSA applies to self-employed individuals and landlords whose gross income from those sources exceeds a set threshold. The rollout is structured in phases:

    • From April 2026: Those with qualifying income above £50,000 are mandated to comply.
    • From April 2027: The threshold drops to £30,000.
    • From April 2028: Those earning above £20,000 are brought in (subject to final confirmation).

    Partnerships are not yet included in the current mandate but are expected to follow in subsequent phases. General partnerships will receive more guidance from HMRC in due course.

    What Does Quarterly Reporting Actually Mean in Practice?

    Under MTD for ITSA, you will submit a summary of your income and expenses to HMRC four times per year, aligned to quarterly periods. These are not tax payments; they are digital updates that give HMRC a running picture of your finances. At the end of the tax year, you finalise your position with an end-of-period statement and a final declaration, which replaces the old Self Assessment return.

    Each quarterly update must be submitted through HMRC-compatible software. You cannot use HMRC’s own online portal for this in the way you might currently file a Self Assessment return. The software must be capable of keeping digital records and submitting them directly to HMRC’s systems via an application programming interface (API).

    For most sole traders with relatively simple accounts, four quarterly updates per year is not a dramatic shift if you’re already tracking income and expenses digitally. The burden is greater for those who currently do their books once a year in January.

    Choosing the Right MTD-Compatible Software

    HMRC maintains a list of compatible software on its website, and the market has responded accordingly. Options broadly fall into three camps: dedicated accounting platforms (such as QuickBooks, Xero, and FreeAgent), lighter-touch app-based tools designed for sole traders, and spreadsheet-based solutions that use bridging software to send data to HMRC.

    Bridging software is worth understanding. If you are wedded to your spreadsheet-based bookkeeping system, you don’t necessarily have to abandon it. Bridging software acts as the connector between your existing records and HMRC’s API. You maintain your spreadsheet as normal, import the figures into the bridging tool, and it handles the submission. This is a pragmatic middle ground for those who are not ready to overhaul their entire approach.

    Business owner using MTD-compatible accounting software for Making Tax Digital self-employed UK 2026 quarterly submissions
    Business owner using MTD-compatible accounting software for Making Tax Digital self-employed UK 2026 quarterly submissions

    For those choosing a full accounting platform, the key is to match the software to your actual workflow rather than buying the most feature-rich tool on the market. A sole trader running a modest consultancy doesn’t need a platform designed for a company with fifty employees. Look for something with a clean bank feed integration, clear quarterly summary views, and ideally a mobile app if you’re frequently on the move.

    Transitioning Without Disrupting Your Current System

    The single biggest mistake I see people make is waiting until the mandate deadline and then trying to switch systems under pressure. The transition period before your mandatory start date is valuable time. Use it.

    A sensible approach looks something like this. First, identify whether your gross income is likely to bring you into the initial April 2026 cohort or a later phase. Second, audit your current bookkeeping method and decide whether it can be adapted or whether a clean break makes more sense. Third, pilot your chosen software for at least one quarter before you’re legally required to use it. Running your existing system in parallel briefly is worth the extra effort; it builds confidence and surfaces any gaps.

    The category of business owner who tends to struggle most is those who have been filing their own Self Assessment return via HMRC’s online portal each January, often with minimal record-keeping throughout the year. For that group, MTD for ITSA isn’t just a software change; it’s a behavioural one. Monthly or at least quarterly reconciliation will need to become a habit rather than an annual sprint.

    It’s also worth noting that MTD for ITSA does not change what you are taxed on. Your tax liability is calculated in the same way. The only change is the frequency and method of reporting.

    How Digital Business Operations and MTD Overlap

    There’s a broader point here that goes beyond tax compliance. The businesses that will find the MTD transition smoothest are those that already run digitally coherent operations: cloud-based records, integrated payment systems, and software that talks to other software without manual re-entry. Making Tax Digital self-employed UK 2026 deadlines are, in a sense, forcing a maturity of financial infrastructure that benefits business owners well beyond the tax return itself.

    This is a shift that digital-first businesses have understood for some time. Based in Mansfield, Nottinghamshire, dijitul provides web design, SEO, and hosting services that underpin the kind of digital business infrastructure where software, marketing, and business efficiency converge. Their work at dijitul.uk reflects the same principle that MTD reinforces: having your digital house in order is not a luxury; it’s an operational baseline. The businesses that have invested in coherent web and software ecosystems tend to find compliance obligations far less disruptive, because their data is already structured and accessible.

    Accounting software increasingly integrates with other business tools too. Your invoicing platform, payment processor, and bookkeeping software can in many cases share data automatically, reducing manual input and the risk of errors creeping into your quarterly submissions.

    For a self-employed individual wondering how to square MTD requirements with their existing workflow, dijitul’s approach to building organised, software-integrated business systems is a useful frame of reference: the goal is not complexity but clarity, and the right digital tools make the difference between a process that drains you and one that practically runs itself.

    Exemptions and What HMRC Says About Them

    Not everyone will be mandated. HMRC has provisions for exemptions where it is not reasonably practicable to use software, for instance due to age, disability, or location. However, these exemptions are not self-declared; they require an application. The bar is relatively high, and HMRC’s expectation is that the vast majority of self-employed individuals and landlords will comply digitally.

    If you believe you may qualify for an exemption, contact HMRC directly and document your case thoroughly. Do not assume exemption applies to you without confirmation.

    The Bottom Line for Sole Traders and Landlords

    Making Tax Digital for Income Tax is not as complicated as the volume of guidance material makes it appear. The core requirement is simple: keep digital records, submit quarterly summaries through compatible software, and finalise your position at year end. What trips people up is delay and denial. If your income puts you in the April 2026 bracket, you have a narrow window to get your systems in place. If you fall into a later phase, that’s not a reason to ignore the change; it’s an opportunity to transition calmly rather than under pressure.

    Pick your software, run it in parallel for a quarter, and build the habit of reconciling regularly. The administrative overhead, once the system is set up, is genuinely manageable. The annual January panic, on the other hand, will no longer be an option.

    Frequently Asked Questions

    When does Making Tax Digital for Income Tax start for self-employed people?

    The first mandatory phase begins in April 2026 for sole traders and landlords with qualifying gross income above £50,000. The threshold drops to £30,000 in April 2027, with a further reduction to £20,000 expected in April 2028, subject to HMRC confirmation.

    What software do I need for Making Tax Digital self-employed filing?

    You must use HMRC-compatible software to keep digital records and submit quarterly updates. Options include full accounting platforms such as QuickBooks, Xero, or FreeAgent, as well as bridging software that connects existing spreadsheets to HMRC’s systems. HMRC publishes an updated list of approved software on gov.uk.

    Can I still use a spreadsheet for my bookkeeping under Making Tax Digital?

    Yes, but not directly. Spreadsheets must be connected to HMRC’s systems via bridging software, which acts as the link between your records and HMRC’s API. You maintain your spreadsheet as usual and use the bridging tool to handle submissions. This is a recognised and legitimate approach under MTD rules.

    Does Making Tax Digital change how much tax I pay?

    No. MTD for Income Tax changes how and when you report your income and expenses, not how your tax liability is calculated. Your tax bill is worked out in the same way as under Self Assessment; the difference is quarterly digital reporting rather than a single annual return.

    What happens if I miss a quarterly MTD submission deadline?

    HMRC operates a points-based penalty system for late submissions under MTD for ITSA. Each missed submission accrues a penalty point, and once a threshold is reached, a financial penalty applies. It is worth noting that the system is designed to be more lenient for occasional lapses than the previous fixed-penalty regime, but consistent non-compliance will result in fines.

  • Why UK Freelancers and Consultants Are Building Productised Services in 2026

    Why UK Freelancers and Consultants Are Building Productised Services in 2026

    There is a quiet but significant shift happening across the UK’s independent workforce. Freelancers and consultants who once built their businesses around bespoke project work, hourly rates, and lengthy discovery calls are repackaging their expertise into clearly defined, fixed-price offerings. Productised services UK freelancers and consultants are building have become one of the more practical responses to an increasingly competitive and unpredictable market. The appeal is straightforward: predictable income, less back-and-forth with clients, and a sales process that almost runs itself.

    According to ONS data on self-employment, there are approximately 4.2 million self-employed people in the UK. A growing proportion of those are knowledge workers, from brand strategists and copywriters to compliance consultants and technical specialists. Many of them are discovering that selling time is a ceiling with no skylight, and productisation is how they break through it.

    UK consultant reviewing a productised services proposal at a modern office desk
    UK consultant reviewing a productised services proposal at a modern office desk

    What Does It Mean to Productise a Service?

    Productisation is the process of taking something you already do for clients and packaging it with a fixed scope, a fixed price, and a clearly defined outcome. Instead of saying “I do content strategy, get in touch for a quote,” you say “12-month editorial roadmap with competitor analysis and platform audit, delivered in 10 working days, £1,800.” The service does not change dramatically; the way it is sold and delivered does.

    The key ingredients are a defined deliverable, a consistent process, and transparent pricing. When all three are in place, clients know exactly what they are getting, and you know exactly how much effort it requires. That symmetry is surprisingly rare in freelance work, and clients actually appreciate it. Ambiguity is rarely comfortable for either side of a working relationship.

    How Productised Services Improve Cash Flow Predictability

    One of the most persistent frustrations for independent professionals is the feast-and-famine income cycle. A strong month of project completions is followed by a month of prospecting. Productised services disrupt that pattern in a few important ways.

    Fixed-price packages allow you to sell upfront or in structured instalments. Many consultants now require 50% payment before work begins, which creates immediate cash inflow rather than the typical net-30 invoice chasing that haunts traditional freelance billing. When you know that each “Website Audit Package” takes roughly 8 hours and earns £950, you can calculate with confidence what your month looks like based on bookings. That is a fundamentally different relationship with money than logging hours and hoping the invoice clears.

    Retainer-style productised services go even further. A monthly “Brand Voice Maintenance” package at £600 per month recurring is, in practical terms, a salary you sold yourself. The more of these a consultant builds up, the more stable the underlying business becomes.

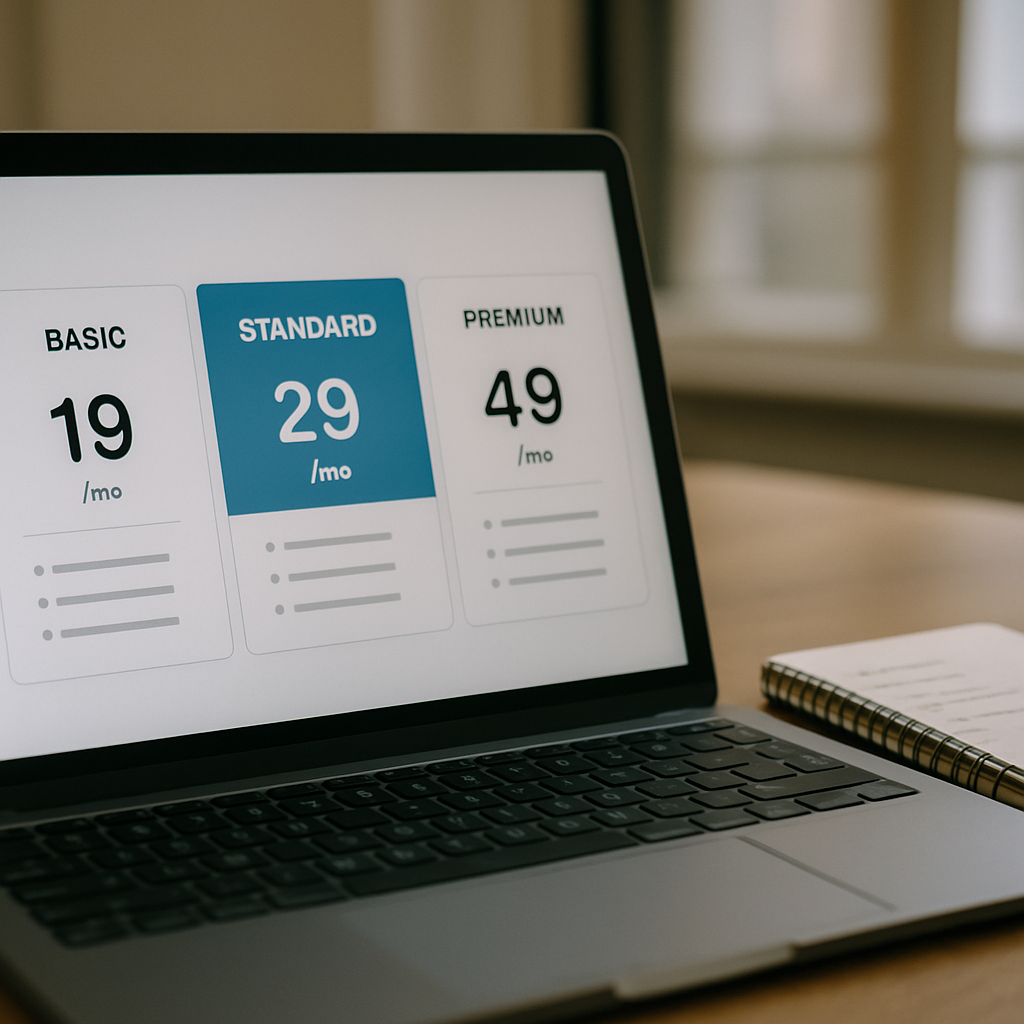
    Laptop showing fixed-price service packages used by productised services UK freelancers
    Laptop showing fixed-price service packages used by productised services UK freelancers

    Scope Creep: The Problem Productisation Actually Solves

    Scope creep is the silent profit killer of project-based work. A client asks for “one small change” that takes three hours. Another wants to “just add a section” that restructures the entire deliverable. Without clearly defined boundaries, these requests are difficult to refuse without damaging the relationship, and most freelancers absorb the cost rather than risk awkwardness.

    A well-constructed productised service makes this conversation almost unnecessary. The scope is defined before money changes hands. If a client wants something outside the package, that becomes a separate engagement, not a favour. This is not about being difficult; it is about being clear. Experienced consultants will tell you that clients who understand exactly what they are paying for tend to be far more satisfied than those operating on vague assumptions.

    This model works across a surprisingly broad range of specialist fields. Asbestos Compliance Solutions Ltd, a Mansfield, Nottinghamshire-based firm providing professional asbestos services to the building and construction sector, operates in a world where defined scope is not optional. Asbestos surveying, management plans, and removal oversight are regulated activities with specific deliverables, and clients commissioning those specialist services expect precise outcomes with no grey areas. The same discipline that governs compliance work in asbestos management is exactly what knowledge workers apply when they productise: clear scope, defined process, documented outcome. You can find out more at asbestoscompliancesolutions.co.uk.

    Why Productised Services Make Marketing Significantly Easier

    Marketing a bespoke service is genuinely hard. You are essentially asking potential clients to imagine a custom outcome they cannot fully visualise before committing. You have to articulate value in abstract terms, which means longer sales conversations and more scepticism to overcome.

    A packaged service changes the marketing equation entirely. You have a name for what you sell, a price, a timeline, and a specific outcome. You can write one clear landing page. You can run targeted ads. You can create a short video explanation. You can post consistently on LinkedIn about a single, coherent offering rather than trying to convey the breadth of everything you might theoretically do for someone.

    The specificity also improves word-of-mouth. “She does a 30-day PR launch package for product-based businesses” is a referral that someone can actually pass on. “She does communications consultancy” is not. One of these generates leads while you are asleep; the other requires you to be in the room.

    What Kinds of Services Productise Well?

    Not everything can or should be packaged rigidly. Complex, highly bespoke strategic work often requires the flexibility of a traditional consulting relationship. But a significant portion of what independent professionals do is repeatable, even when it does not feel that way.

    Common categories that productise well include: technical audits (SEO, IT infrastructure, financial processes), onboarding and setup services, training programmes, content creation packages, compliance reviews, and process documentation. The pattern is clear: anything that has a consistent starting point, a reliable method, and a recognisable end state is a candidate.

    It is also worth noting that productised services do not have to replace bespoke work entirely. Many consultants use a lower-priced entry package as a lead-generation tool that naturally converts into longer engagements. A fixed-price “two-hour systems review” at £195 is an easy yes for a prospective client who is not ready to commit to a six-month retainer. It also demonstrates competence far more convincingly than a proposal document ever could.

    Getting the Pricing Right Without Underselling

    The most common mistake when productising is pricing based on time rather than value. If your “Social Media Strategy Package” takes you six hours and you charge £300, you are effectively billing at £50 per hour. That might feel safe, but it ignores the value the client is receiving, which could be the basis for their next year of marketing activity.

    Value-based pricing within a productised model means asking what this outcome is worth to the client, not how long it takes you to produce. Firms in specialist services sectors have understood this for years. Asbestos Compliance Solutions Ltd and similar building and construction specialists providing regulated asbestos services are not pricing per hour of site visit; they are pricing for regulatory certainty, liability protection, and professional competence. That distinction is exactly what productised service consultants need to internalise.

    A useful exercise is to map what the absence of your deliverable costs the client. A brand that has no content strategy loses ground to competitors every week. A business with no financial reporting process makes poor decisions. Quantify the problem, and your pricing starts to feel very reasonable indeed.

    The Operational Shift Behind the Model

    Productisation is not just a pricing and marketing exercise. It requires building repeatable systems behind the scenes: templated workflows, standardised questionnaires, documented processes, and quality checklists. This operational investment pays back quickly, because each repeat delivery of the same package becomes faster and more reliable. You are essentially building a small production system around your expertise rather than reinventing the wheel for every client.

    For many independent professionals, this is the part that feels most unfamiliar. Freelancers often pride themselves on adaptability, and systematising can feel like a creative constraint. In practice, having a reliable process frees up mental energy for the genuinely complex or creative parts of the work. The scaffolding handles itself; you focus on what only you can do.

    The shift toward productised services UK freelancers and consultants are making is, at its core, a maturity move. It is the transition from selling labour to selling outcomes, and from running a job to running a business. That distinction, modest as it sounds, changes everything about how an independent professional grows, earns, and sustains a career.

    Frequently Asked Questions

    What are productised services and how are they different from traditional freelance work?

    Productised services are clearly defined, fixed-scope offerings sold at a set price with a predetermined deliverable and timeline. Unlike traditional bespoke freelance work, where scope and cost are negotiated per project, productised services have consistent boundaries and processes, making them easier to sell, deliver, and scale.

    How do productised services help UK consultants with cash flow?

    Because productised services have fixed prices, consultants can require upfront or staged payments rather than billing hourly after the fact. This reduces late payment risk and creates more predictable monthly income, particularly when recurring retainer-style packages are part of the offering.

    Can any type of consulting or freelance work be turned into a productised service?

    Not all work suits rigid packaging, but most knowledge-based services have repeatable elements that can be productised. Technical audits, onboarding programmes, compliance reviews, and content packages all work well. Complex or highly strategic engagements are often better kept as bespoke, though a fixed entry-level package can serve as a valuable first step.

    How should UK freelancers price their productised service packages?

    The most effective approach is value-based pricing: consider what the outcome is worth to the client rather than how many hours it takes you. Map the cost of the client’s problem going unsolved, then price accordingly. Charging based purely on time typically undervalues the expertise and reliability a packaged offering provides.

    Does productising services reduce the quality or personalisation of the work delivered?

    Done properly, productisation improves consistency rather than reducing quality. Standardised processes and checklists ensure every client receives a reliable, high-quality outcome. Personalisation happens within the defined framework, and the time saved on admin and scope negotiation can actually be reinvested into the work itself.

  • The Rise of Embedded Finance: What It Means for Small and Medium Businesses

    The Rise of Embedded Finance: What It Means for Small and Medium Businesses

    Not long ago, if a small business needed a loan, the process involved a trip to the bank, a stack of paperwork, and a wait measured in weeks rather than days. If it needed to accept payments, it signed up with a separate merchant services provider. Payroll, insurance, invoicing, all different suppliers, different logins, different contracts. Embedded finance is quietly dismantling that fragmentation, and for UK SMEs, the implications are significant.

    At its core, embedded finance is the integration of financial services, banking, lending, payments, insurance, directly into non-financial platforms. The accountancy software you already use to raise invoices could, in theory, also offer you a working capital loan based on your live revenue data. The e-commerce platform hosting your online shop might offer instant checkout finance to your customers without them ever leaving your site. The software is no longer just a tool; it becomes the financial institution itself, or at least a credible front for one.

    Small business owner reviewing embedded finance for small businesses on a laptop in a bright UK office
    Small business owner reviewing embedded finance for small businesses on a laptop in a bright UK office

    How Embedded Finance Actually Works

    The machinery behind this sits largely in open banking and API connectivity. Since the Financial Conduct Authority mandated open banking in the UK following the EU’s PSD2 directive, banks have been required to share customer data (with consent) via standardised interfaces. That opened the door for software companies to plug financial products directly into their platforms using partner banks or e-money institutions operating in the background.

    Take a practical example. Xero, the cloud accountancy platform used by hundreds of thousands of UK small businesses, has integrated lending features that assess creditworthiness in real time using a company’s own financial data held within the software. The business owner does not need to print bank statements or fill in a separate application form. The platform already has the information. Approval decisions can arrive within hours.

    Shopify’s capital product works along similar lines for e-commerce merchants. Square offers embedded banking and payroll tools for its point-of-sale customers. The pattern is consistent: a platform earns your trust with its primary product, then layers financial services on top using the transactional or accounting data it already holds. According to research cited by the Financial Conduct Authority, open banking usage in the UK reached over 10 million active users by early 2025, which gives you a sense of how quickly the infrastructure has matured.

    The Genuine Opportunities for SMEs

    Embedded finance for small businesses offers something the traditional banking system has consistently failed to deliver at scale: speed and contextual relevance. When a lending decision is based on live cashflow data rather than historical credit scores and audited accounts, businesses that are genuinely healthy but asset-light stand a much better chance of accessing capital quickly.

    Close-up of hands using business software platform with embedded finance for small businesses features
    Close-up of hands using business software platform with embedded finance for small businesses features

    For product-based businesses in particular, inventory financing through embedded platforms can be transformative. Rather than waiting for a quarterly review with a business manager, a retailer could receive an automated offer of short-term stock finance at exactly the moment the platform detects an upcoming seasonal demand spike in their sales data. That kind of contextual timing is something no traditional bank branch can replicate.

    There are also meaningful benefits on the customer-facing side. Buy Now Pay Later integrations built directly into checkout flows have become standard for many online retailers, enabling smaller merchants to offer payment flexibility that previously required separate finance licences or third-party agreements. That levels the playing field against larger competitors who have had those arrangements in place for years.

    For service businesses, embedded invoicing finance, sometimes called embedded factoring, means outstanding invoices can be converted to cash almost immediately through the same platform used to issue them. The friction of managing a separate invoice discounting facility disappears entirely.

    What Are the Real Risks SMEs Need to Understand?

    Convenience has a way of obscuring cost, and embedded finance is not immune to that dynamic. Embedded lending products can carry interest rates and fees that are less transparent than a traditional business loan agreement. When a financing offer appears inside a platform you already trust, there is an implicit endorsement that may not reflect competitive market pricing. The prudent approach is to treat any embedded credit offer exactly as you would a standalone loan: compare rates, read the full terms, and calculate the effective APR before accepting.

    Data is the other conversation worth having. Embedded finance products work precisely because platforms have access to your financial data. That is the trade-off. When you grant a software provider the right to use your transactional data for credit assessment, you are sharing information that was previously confined to your bank. UK businesses should check the data processing terms carefully and confirm how their information is used, stored, and potentially shared with third-party lenders operating behind the platform’s interface.

    There is also a concentration risk that deserves attention. If your banking, lending, invoicing, and payroll all sit within a single platform ecosystem, a service outage, a pricing change, or a platform closure creates a level of operational exposure that spreading across separate providers would not. It is the same logic that applies to any critical supplier dependency.

    What This Means for Business Strategy Going Forward

    Embedded finance for small businesses is not a fringe development. Several major UK-focused platforms, including Tide, Starling Bank’s business tools, and the Xero partner ecosystem, are actively expanding their embedded product ranges. The market is moving quickly enough that SMEs who engage with these tools thoughtfully now will have a genuine operational advantage over those who discover them reactively.

    The practical starting point is an audit of the software platforms your business already uses and a review of what financial products each one currently offers or is likely to offer. If you use cloud accountancy software, check whether it provides access to lending or cashflow forecasting tools. If you process payments through a platform, investigate whether embedded insurance or working capital products are available to your account tier.

    The shift also has implications for how you think about financial relationships more broadly. The traditional model of having one banking relationship for everything is becoming less relevant. A business might access its current account through a challenger bank, take short-term inventory finance through its e-commerce platform, and use an embedded insurance product tied to its logistics software. Each decision should still be made on commercial merit, but the options have expanded considerably.

    Embedded finance represents a structural change in how financial services reach businesses, not a passing trend. The question for most SMEs is not whether these tools will affect how they operate, but how deliberately they choose to engage with them.

    Frequently Asked Questions

    What is embedded finance for small businesses?

    Embedded finance refers to financial products such as loans, payments, insurance, or banking being integrated directly into non-financial software platforms. For small businesses, this means accessing credit or payment tools within the accountancy, e-commerce, or operations software they already use, without needing a separate bank or provider.

    Is embedded finance regulated in the UK?

    Yes. Embedded financial products must still comply with UK financial regulation. The underlying financial services are typically provided by FCA-authorised firms operating behind the platform’s interface. Businesses should verify that any embedded lender or payment provider is properly authorised on the FCA Register before using their products.

    How does embedded lending differ from a traditional business loan?

    Embedded lending uses real-time data from the platform you already use, such as live revenue or cashflow, to assess creditworthiness quickly. Traditional business loans typically require historical accounts, credit checks, and a manual application process. Embedded loans are faster to access but may carry different interest structures, so comparing the effective APR is essential.

    What are the risks of using embedded finance products?

    The main risks include less transparent pricing compared to standalone financial products, data sharing with third-party lenders embedded within the platform, and operational dependency on a single provider. Businesses should read the full terms of any embedded credit offer and ensure they understand what data is being shared and with whom.

    Which UK platforms currently offer embedded finance features?

    Several platforms actively serving UK SMEs have embedded finance features, including Xero (lending integrations), Tide (business banking with credit products), Starling Bank’s business tools, and various e-commerce platforms offering point-of-sale credit. The range of products available varies by account type and business profile.

  • Passive Income Streams for Business Owners: What Actually Works in 2026

    Passive Income Streams for Business Owners: What Actually Works in 2026

    The phrase “passive income” has been doing the rounds for years, often wrapped in motivational nonsense about sipping cocktails while money rolls in. The reality is considerably more grounded. Passive income streams for business owners are real, achievable, and genuinely worth building, but they all require either significant upfront capital, time, or existing business infrastructure. Nothing here is magic. What follows is an honest breakdown of what actually produces results in 2026.

    Business owner reviewing passive income streams on a laptop in a modern London office
    Business owner reviewing passive income streams on a laptop in a modern London office

    Why Business Owners Are Better Positioned Than Most

    If you already run a business, you have structural advantages that most people lack. You understand systems, you likely have an existing customer base, and you have professional credibility in at least one area. These aren’t small things. Many passive income models rely on trust and audience, both of which take years to build from scratch. For a business owner, those assets often already exist. The task is deploying them sensibly.

    According to ONS data on UK sector accounts, income from non-employment sources has grown steadily amongst business-owning households over the past decade. That trend hasn’t reversed. If anything, the tooling available in 2026 makes diversified income more accessible than it has ever been.

    Digital Products: Front-Loaded Effort, Long-Tail Returns

    Selling digital products is probably the most talked-about passive income model, and for good reason. Create something once, sell it repeatedly, with no inventory, no logistics, and no fulfilment headache. The formats that work consistently include templates, toolkits, online courses, and written guides aimed at a professional niche.

    The key word is niche. A generic productivity course will struggle. A financial modelling template built specifically for UK-based SaaS founders? That has a defined audience and a genuine use case. Platforms like Gumroad, Teachable, and Kajabi all support UK-based sellers with GBP pricing. Distribution through your existing email list or LinkedIn following keeps your customer acquisition costs low.

    The honest caveat: most digital products require ongoing promotion. The “set and forget” version of this model doesn’t really exist. What you get is a product that earns without additional production time, not one that markets itself indefinitely.

    Licensing Your Expertise or Intellectual Property

    If your business has developed proprietary processes, frameworks, software, or creative assets, licensing is worth examining seriously. This is one of the more underused passive income streams for business owners in the UK, perhaps because it requires proper legal structuring, but the returns can be substantial and genuinely hands-off once agreements are in place.

    Licensing works particularly well in sectors like software, professional training, photography, and branded methodology. A management consultancy that has developed a proprietary assessment framework, for instance, could licence that to other consultancies or to corporate HR departments, generating recurring royalty income. The SRA and relevant professional bodies may need to be considered depending on your sector, but a commercial solicitor can structure a clean agreement that protects your IP whilst generating income.

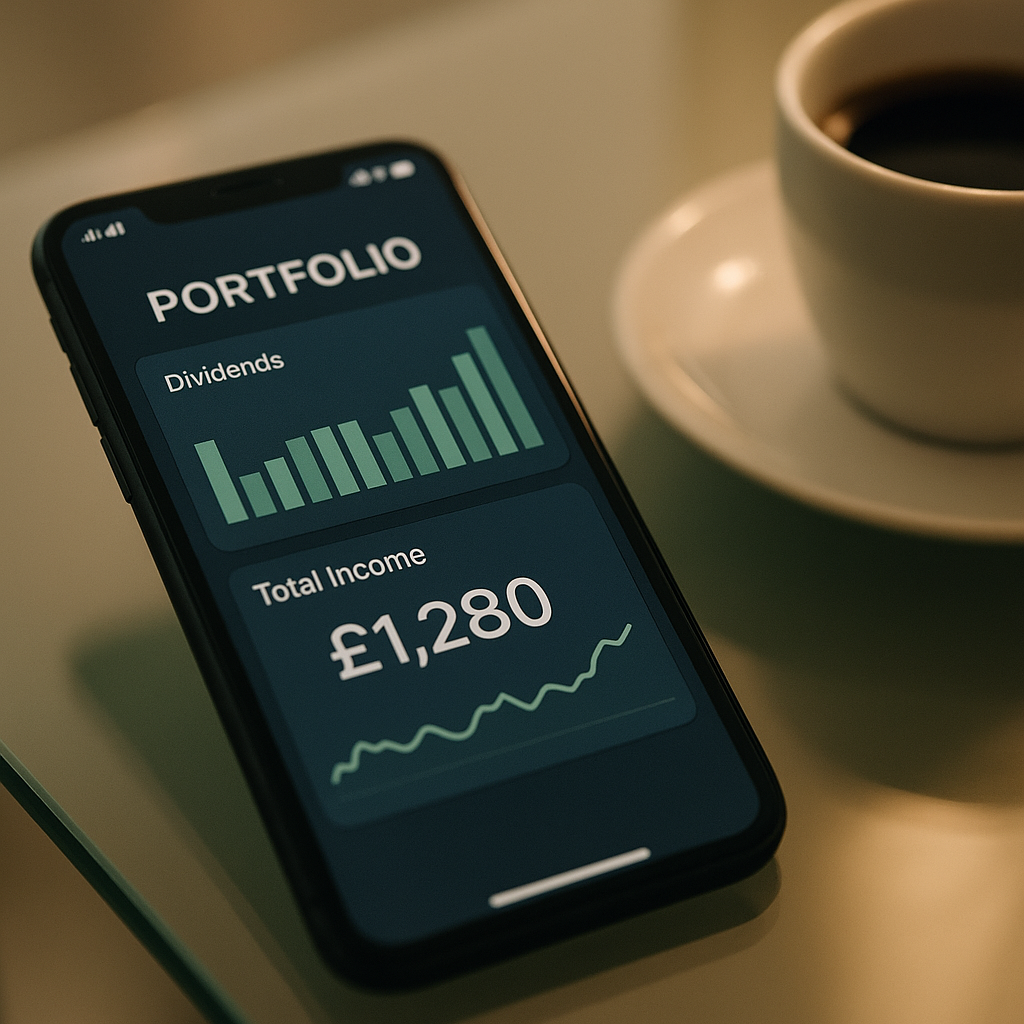
    Smartphone showing dividend investment dashboard as part of passive income streams for business owners
    Smartphone showing dividend investment dashboard as part of passive income streams for business owners

    Dividend Investing: Boring, Slow, and Extremely Effective

    Business owners who generate retained profits have a natural path into dividend investing. Holding dividend-paying equities inside a company pension, a Stocks and Shares ISA, or directly via a trading account produces income that compounds quietly in the background. The FTSE 100 includes a strong cohort of historically reliable dividend payers: utilities, financial institutions, consumer staples. These are not exciting businesses. That is rather the point.

    The tax efficiency angle matters here. Dividends received within an ISA are free of both income tax and capital gains tax. The annual ISA allowance in 2026 remains £20,000 per individual. Business owners who pay themselves through dividends already understand the mechanics; extending that thinking to investment income is a logical step.

    Realistic expectations are important. A 4% dividend yield on a £100,000 portfolio produces £4,000 per year. That is supplementary income, not a replacement salary. However, compounded over a decade with reinvested dividends, the numbers become genuinely meaningful.

    Automated Service Models and White-Label Revenue

    This one is specific to business owners rather than individuals. If you run a service business, there are usually components of your offering that can be productised, automated, or white-labelled to generate income without your direct involvement.

    A digital agency that builds a proprietary reporting dashboard might white-label that tool to other agencies. A bookkeeping firm might build a self-service client onboarding flow that handles initial scoping without human input, reducing delivery costs whilst maintaining revenue. A marketing consultant might build a membership community with a monthly subscription that delivers value through recorded content and templated resources rather than live time.

    None of these models are purely passive from day one. They require thoughtful system design and consistent quality. But they all share one important characteristic: revenue that is no longer directly proportional to your working hours. That decoupling is what passive income actually means in a business context.

    Property Income: Still Relevant, But Context-Dependent

    Buy-to-let has had a difficult few years in the UK. Changes to mortgage interest relief, stamp duty surcharges on additional properties, and tighter EPC requirements have compressed margins for many landlords. That said, commercial property, rent from equipment or storage, and property held within a SIPP (Self-Invested Personal Pension) still represent viable income streams depending on your capital position and risk tolerance.

    The simpler entry point for business owners is commercial property investment through REITs (Real Estate Investment Trusts), which trade on the London Stock Exchange. These offer property income exposure without the management overhead of direct ownership, and they can be held within an ISA for tax efficiency.

    Choosing the Right Model for Your Situation

    Passive income streams for business owners work best when they align with assets you already possess: expertise, IP, capital, or an audience. Spreading yourself across five different models simultaneously is a reliable way to do none of them well. The more effective approach is to identify one model that fits your current position, build it properly, and layer in a second once the first is genuinely running.

    The businesses that sustain multiple income streams over the long term are invariably the ones that treated each stream as a serious project rather than a side experiment. The “passive” part comes later. The work comes first.

    Frequently Asked Questions

    What are the most realistic passive income streams for business owners in the UK?

    The most realistic options include selling digital products (templates, courses, guides), licensing intellectual property, dividend investing via ISAs or company pensions, and automating parts of an existing service business. Each requires upfront investment of time or capital but can generate income with reduced ongoing effort.

    How much money do I need to start generating passive income as a business owner?

    It varies significantly by model. Digital products can be built for very little upfront cost if you have existing expertise. Dividend investing becomes meaningful at £50,000 or more in invested capital. Licensing arrangements depend on having existing IP or systems worth licencing. The lowest barrier to entry is typically digital products or productised services.

    Is passive income taxable in the UK?

    Yes, most passive income is taxable. Dividend income above the annual £500 dividend allowance is subject to dividend tax. Rental income is subject to income tax. Capital gains from investments outside an ISA are subject to CGT. Holding income-generating assets inside a Stocks and Shares ISA is one of the most tax-efficient approaches available to UK residents.

    How long does it take for passive income to become significant?

    Most passive income models take 12 to 36 months before they generate meaningful, reliable income. Digital products need an audience and promotional infrastructure. Dividend portfolios grow through reinvestment over years. Automated service models require system-building before they reduce your direct labour. Treating passive income as a long-term project rather than a quick fix produces much better results.

    Can I build passive income while still running my main business?

    Yes, and this is the most common approach. Many business owners start by productising knowledge or assets they already have, which requires less additional time than building something from scratch. The key is focusing on one income stream at a time to avoid spreading resources too thinly across multiple unfinished projects.

  • SaaS Subscription Fatigue: How to Audit and Cut Your Business Software Costs

    SaaS Subscription Fatigue: How to Audit and Cut Your Business Software Costs

    Most businesses didn’t set out to spend a small fortune on software every month. It tends to happen gradually. A project management tool here, a communication platform there, a niche analytics add-on that someone on the team swore was essential. Before long, you’re staring at a bank statement with fifteen recurring line items, and at least a third of them are doing roughly the same job. This is SaaS subscription fatigue, and it is quietly bleeding UK businesses dry.

    According to business analysts at the BBC, operational cost control has become one of the top priorities for SMEs across the UK in 2026, with software overhead consistently flagged as an area where spending has outpaced genuine value. A proper SaaS audit is the most direct way to address it.

    Business professional conducting a SaaS audit on a laptop in a modern London office
    Business professional conducting a SaaS audit on a laptop in a modern London office

    What Is a SaaS Audit and Why Does It Matter?

    A SaaS audit is a structured review of every software subscription your business is paying for, mapping each tool against actual usage, business function, and cost. It sounds straightforward. In practice, most businesses have no single source of truth for what they’re subscribed to, which is partly how the problem compounds over time.

    Subscriptions get set up by individuals, teams, or departments. Some are billed to personal credit cards and expensed informally. Others are annual commitments that auto-renew without anyone noticing. The goal of an audit is to surface all of it, assign ownership, and make deliberate decisions rather than passive ones.

    How to Conduct a SaaS Audit Step by Step

    Step 1: Build a Complete Software Inventory

    Start by pulling bank statements, credit card records, and invoices from the last three months. Look for recurring charges from any software vendor. Cross-reference this with your accounting software if you use something like Xero or QuickBooks Online. Then speak to department heads. Finance will know their tools, marketing will know theirs. The IT or operations lead should have visibility over infrastructure licences.

    Tools like Cledara or Spendesk, both popular with UK finance teams, can help automate subscription tracking if you want something ongoing rather than a one-off exercise. For now, a spreadsheet works perfectly well.

    Step 2: Categorise by Function

    Once you have a full list, group tools by what they do. You’re looking for overlap. Common culprits include:

    • Multiple communication platforms (Teams, Slack, Zoom, Google Meet all running simultaneously)
    • Duplicate project management tools across departments (Asana in one team, Monday.com in another)
    • Separate CRM systems that haven’t been consolidated post-merger or growth
    • Storage and document tools with significant feature overlap (Google Workspace and Microsoft 365 both active)

    Each of these categories is worth a focused conversation about standardisation.

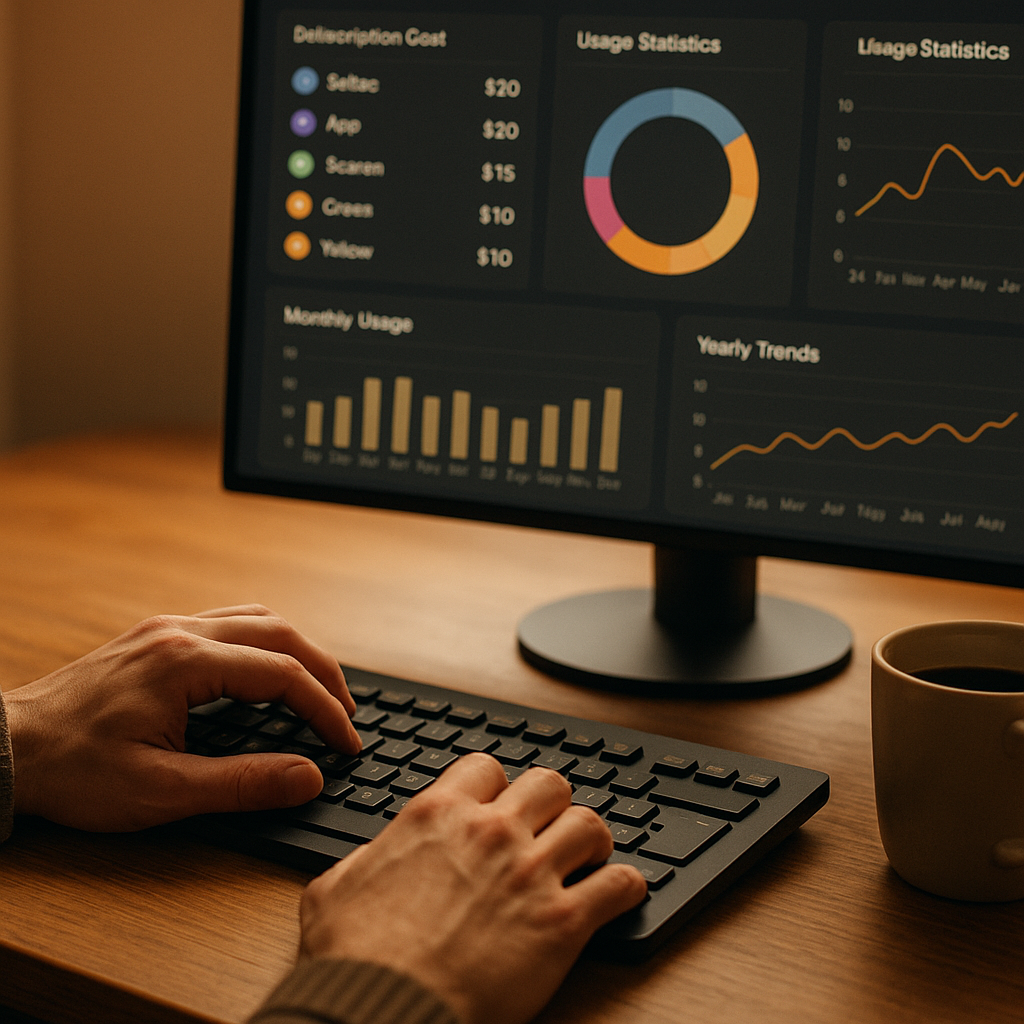
    Close-up of SaaS audit dashboard showing subscription usage data on a business monitor
    Close-up of SaaS audit dashboard showing subscription usage data on a business monitor

    Step 3: Assess Actual Usage

    Cost alone doesn’t tell the full story. A tool that costs £200 per month and is used by the entire company daily is delivering value. One that costs £80 per month and has two active logins from twelve licensed seats is not.

    Most SaaS platforms now offer usage dashboards in their admin panels. Pull last login data, active user counts, and feature utilisation where available. For tools that don’t surface this natively, simply ask the team honestly: how often are you actually using this?

    Apply a simple scoring framework. Rate each tool on three dimensions: business criticality, uniqueness of function, and actual usage frequency. Anything that scores low across all three is a strong candidate for cancellation.

    Step 4: Identify Redundant Tools and Make Cuts

    With your usage data in hand, you’re now in a position to act. This is where most audits stall. Nobody wants to be the person who cancels the tool that turns out to be quietly essential to one workflow nobody documented. Avoid this by giving a two-week notice period internally before cancelling anything, inviting anyone who relies on it to speak up.

    Prioritise cutting tools that duplicate functionality already covered by your core stack. If you’re paying for Microsoft 365, you likely don’t need a separate video conferencing licence, a standalone document signing tool, or an additional forms platform. Microsoft’s native features cover all three adequately for most teams.

    For tools that serve a genuine function but at an inflated price point, consider downgrading rather than cancelling. Most SaaS vendors have lower tiers that cover 80% of what most teams actually need. It is worth a conversation with your account manager, particularly for annual contracts approaching renewal.

    Negotiating Better Deals Before Renewal

    Renewal periods are your leverage point. SaaS vendors know that switching costs are real, but they also know a churned customer pays nothing. If you’ve identified a tool you want to keep but the pricing feels off, reach out four to six weeks before renewal. Express that you’re reviewing the stack, mention that you’ve identified alternative options, and ask what they can offer.

    This works more often than people expect. Discounts of 15 to 25% are not unusual for businesses willing to commit to an annual contract or a slightly expanded licence count. If you’re a smaller business, vendor consolidation is another angle: switching entirely to a platform that bundles several functions can meaningfully reduce total spend.

    Building Oversight Into Your Business Going Forward

    The real value of a SaaS audit isn’t just the one-off saving. It’s building the discipline to prevent the problem recurring. A few practical measures help significantly:

    • Require sign-off from a finance or operations lead before any new software subscription above £30 per month is activated
    • Set calendar reminders 45 days before every annual renewal so you have time to review and negotiate
    • Assign clear ownership to each tool so there’s always one person accountable for its value
    • Run a lightweight audit quarterly rather than a comprehensive one annually

    This kind of operational rigour extends to other business expenses too. One conversation I had recently with a property management firm reminded me that even overlooked recurring services, from regular maintenance contracts to routine services like wheelie bin cleaning, benefit from periodic review to ensure they’re still appropriately priced and actively delivering value.

    What Kind of Savings Can You Realistically Expect?

    The numbers vary by business size and how chaotic things have become. For a team of 20 to 50 people, it’s not unusual to find £800 to £2,000 per month in recoverable spend after a thorough SaaS audit. Larger organisations have found far more. A 2025 report from Vertice, a UK-based SaaS procurement platform, found that the average British SME was paying for software used by fewer than half the employees licensed to access it.

    Even modest cuts compound over a year. Trimming £600 per month from your software stack is £7,200 annually, freed up for headcount, marketing, or simply stronger margins. That’s not trivial for a growing business watching every overhead line.

    The Bottom Line

    A SaaS audit isn’t a one-afternoon job for a 50-person business, but it’s not a six-month project either. Approached methodically, most businesses can complete a meaningful review within two to three weeks and see genuine cost reductions within the same billing cycle. The tools your business runs on should be working for you. If you haven’t looked closely at your subscriptions in the last twelve months, there’s a reasonable chance some of them aren’t.

    Frequently Asked Questions

    How often should a business conduct a SaaS audit?

    A comprehensive SaaS audit is worth running annually at minimum, with a lighter-touch review each quarter to catch new subscriptions before they become habitual overhead. Many UK businesses find that aligning the full audit with their financial year-end works well for budgeting purposes.

    What tools can help me track SaaS subscriptions automatically?

    Platforms like Cledara, Spendesk, and Paddle are popular with UK businesses for ongoing SaaS spend visibility. They connect to your payment methods and flag recurring charges, making it easier to maintain a live inventory without relying on manual spreadsheet reviews.

    How do I identify which software tools are actually being used?

    Most enterprise SaaS platforms provide admin dashboards showing last login dates and active user counts. For tools that don’t offer this, pull your billing records for per-seat licences versus actual headcount, and survey team leads directly. Usage data is usually more telling than anyone’s stated perception.

    Can you negotiate SaaS pricing mid-contract?

    It’s less common to renegotiate mid-contract, but not impossible, particularly if your usage has dropped significantly or you’re considering cancellation. The strongest position is at renewal, ideally four to six weeks before the contract expires, when you have time to credibly explore alternatives.

    What are the biggest hidden costs in business SaaS spending?

    Beyond subscription fees, the biggest hidden costs are redundant tools duplicating the same function across departments, underused licences at premium tier pricing, and auto-renewing annual contracts that no one reviews. Integrations and premium add-ons that were activated but never used consistently also add up quietly.

  • How Businesses Are Using No-Code Platforms to Launch Software Products Without Developers

    How Businesses Are Using No-Code Platforms to Launch Software Products Without Developers

    The idea that building software requires a team of developers, a six-figure budget, and months of planning has quietly become outdated. Entrepreneurs, operations managers, and small business owners across the UK are shipping functional tools, client portals, and internal dashboards without writing a single line of code. The no-code movement has matured considerably, and in 2026 it is genuinely reshaping how businesses approach product development.

    This is not about hobbyists tinkering with templates. Serious companies are using no-code platforms for business software 2026 to move faster, reduce costs, and stay competitive in markets where speed matters enormously.

    Business professional using no-code platforms for business software 2026 at a modern office workstation
    Business professional using no-code platforms for business software 2026 at a modern office workstation

    What Is the No-Code Movement, Really?

    No-code platforms provide visual, drag-and-drop interfaces that let non-technical users design and deploy working software. Logic, databases, user authentication, API connections, and responsive layouts are all handled through the platform’s interface rather than written by hand. The distinction from traditional development is simple: the builder thinks in terms of outcomes, not syntax.

    Platforms like Bubble handle complex web application logic, making it possible to build marketplace products or SaaS tools. Webflow sits closer to the design-led end, offering precise control over marketing sites and CMS-driven products. Glide turns spreadsheets into polished mobile applications in a matter of hours. Each tool serves a different niche, and together they represent a remarkably capable ecosystem.

    According to BBC Technology, the broader low-code and no-code market is projected to be worth tens of billions globally over the coming years, with UK businesses among the fastest adopters in Europe. The demand is structural, not a passing trend.

    Why UK Businesses Are Adopting No-Code Faster Than Ever

    Cost is the obvious driver, but it is not the only one. Hiring a mid-level developer in London currently commands somewhere between £55,000 and £75,000 per year in base salary alone. For a startup or a lean SME, that is a significant commitment before a single feature ships. No-code platforms typically cost between £30 and £400 per month depending on scale and complexity, which makes the arithmetic fairly straightforward.

    Speed is arguably the more compelling case. Traditional development cycles involve scoping sessions, technical specifications, QA rounds, and deployment pipelines. A no-code build can go from whiteboard sketch to live product in a fortnight. For businesses responding to a market opportunity or testing a new service line, that compression of time is worth more than the headline cost saving.

    There is also the matter of iteration. When the person who understands the business problem is also the person building the tool, the gap between insight and implementation disappears. An operations manager who builds their own internal workflow tool on Glide does not need to brief a developer, wait for a sprint, and then explain why the output missed the point. They simply adjust it themselves.

    Team reviewing no-code platform interface to build business software tools in 2026
    Team reviewing no-code platform interface to build business software tools in 2026

    Real Use Cases: What Are Businesses Actually Building?

    The practical applications span a wide range of business functions. Here are the categories where no-code platforms for business software 2026 are delivering the clearest return:

    Internal Operations and Workflow Tools

    HR teams are building onboarding portals. Finance departments are creating expense tracking tools with approval workflows. Logistics coordinators are assembling dashboards that pull data from multiple sources into a single readable view. These are not glamorous projects, but they replace hours of manual work each week and rarely justify a full development engagement.

    Client-Facing Portals

    Professional services firms, particularly those in accountancy, consultancy, and recruitment, are building secure client portals where documents can be shared, projects tracked, and communication logged. A Bubble-built portal can handle user accounts, file uploads, and role-based permissions without a developer in sight. Several UK boutique consultancies are now delivering these as part of their service proposition rather than an add-on.

    MVP Products and SaaS Launches

    This is where things get genuinely interesting. Founders are using no-code to validate SaaS ideas before committing to a technical build. A subscription-based tool with a proper login, a payment integration via Stripe, and a functional dashboard can be assembled on Bubble in six to eight weeks by a non-technical founder. If it gains traction, the team then considers whether a custom rebuild is warranted. Many find it never is.

    E-commerce and Membership Sites

    Webflow’s commerce capabilities have improved substantially, and UK retailers and content creators are using it to build polished storefronts and membership platforms with far more design control than Shopify allows. For brands where aesthetic is a competitive advantage, that matters.

    The Honest Limitations You Should Know About

    No-code is not a universal answer. There are constraints worth understanding before committing to a platform.

    Scalability can become a concern at high traffic volumes. Bubble, for example, is capable of handling thousands of users, but very large enterprises with complex data processing requirements may eventually hit performance ceilings. At that point, a hybrid approach, using no-code for front-end interfaces whilst connecting to custom back-end logic, often makes more sense than a wholesale rebuild.

    Vendor dependency is a legitimate risk. If a platform changes its pricing, deprecates a feature, or ceases trading, the businesses built on it face disruption. This is not a theoretical concern; it has happened in adjacent software categories. The mitigation is straightforward: export your data regularly, document your logic, and avoid building mission-critical systems on platforms with thin financial foundations.

    There are also capability gaps for genuinely complex applications. Machine learning pipelines, real-time financial processing at scale, or deeply custom mobile experiences will still require traditional development. No-code handles the majority of business software use cases well, but it has a ceiling.

    Getting Started Without Overcomplicating It

    The mistake most business teams make is trying to build too much, too soon. The better approach is to identify one painful manual process, one spreadsheet that everyone dreads, or one client interaction that feels clunkier than it should. Build that first. Ship it internally. Learn how the platform behaves, where its limits are, and how your team actually uses the tool versus how you imagined they would.

    From there, the scope can grow incrementally. The no-code platforms for business software 2026 that are gaining the most ground among UK SMEs are those that combine ease of entry with genuine depth, meaning you do not outgrow them after the first three months.

    Webflow makes sense if design quality and content management are priorities. Bubble is the right call for anything that requires user accounts, complex logic, or relational data. Glide is excellent for converting existing data into mobile-friendly tools quickly. They are not in competition with each other so much as occupying distinct parts of the same ecosystem.

    The Bigger Picture for UK Businesses

    The no-code movement is part of a broader shift in how businesses think about technology. Software used to be something you commissioned from specialists. Increasingly, it is something your team builds, owns, and iterates on directly. That shift has real implications for how companies hire, how they structure operations, and how quickly they can respond to change.

    For UK entrepreneurs in particular, where access to technical co-founders and development resource can be geographically and financially constrained outside of London, no-code represents a genuine levelling of the playing field. A team in Leeds, Bristol, or Manchester can now ship a working software product with the same speed as a well-funded London startup. That is a meaningful change, and it is happening right now.

    Frequently Asked Questions

    What are the best no-code platforms for building business software in 2026?

    Bubble, Webflow, and Glide remain among the most capable options depending on your use case. Bubble suits complex web applications with user accounts and databases; Webflow excels for design-led marketing sites and CMS products; Glide is ideal for turning spreadsheet data into mobile tools quickly.

    Can no-code platforms handle real business complexity, or are they just for simple tools?

    Modern no-code platforms can handle significant complexity, including user authentication, payment processing, API integrations, and relational databases. They are well-suited to the majority of business software use cases, though highly specialised or large-scale enterprise applications may still require custom development at some point.

    How much does it cost to build a business app using a no-code platform?

    Platform costs typically range from around £30 to £400 per month depending on the tool and your usage tier. This compares very favourably with traditional development, where even a straightforward custom application might cost £20,000 to £80,000 to build and maintain.

    Do I need any technical knowledge to use no-code platforms?

    Basic technical literacy helps, particularly an understanding of how databases and logic conditions work, but coding knowledge is not required. Most platforms provide substantial documentation and community support, and many UK-based no-code consultants offer onboarding assistance if you prefer a guided start.

    Is it safe to build important business tools on no-code platforms?

    For most business applications, yes, provided you choose an established platform with a strong track record and reasonable terms of service. Key risk mitigation steps include exporting your data regularly, documenting your workflows, and avoiding over-reliance on any single vendor for truly mission-critical systems.

  • Cryptocurrency vs Traditional Investment: Where Should You Put Your Money in 2026?

    Cryptocurrency vs Traditional Investment: Where Should You Put Your Money in 2026?

    The question that keeps cropping up in boardrooms, on investment forums, and frankly at quite a few dinner tables: is cryptocurrency still worth the gamble, or is the smart money heading back to stocks, bonds, and bricks and mortar? For UK investors looking to build wealth seriously in 2026, the answer is rarely simple. Both worlds have matured considerably, and both carry genuine merit alongside genuine risk. This guide cuts through the noise and offers a grounded comparison of cryptocurrency vs traditional investment 2026 to help you think more clearly about where your money should actually sit.

    UK investor comparing cryptocurrency vs traditional investment 2026 on dual monitors in a modern London office
    UK investor comparing cryptocurrency vs traditional investment 2026 on dual monitors in a modern London office

    The State of Crypto in 2026

    Cryptocurrency has come a long way from the Wild West days of 2017. Bitcoin is now held by institutional investors, several major UK pension funds have begun dipping cautious toes into digital assets, and the Financial Conduct Authority (FCA) has continued tightening its regulatory framework around UK crypto service providers. That regulatory clarity, still imperfect, but improving, has reduced some of the chaos that once defined the space.

    That said, volatility has not been tamed. Bitcoin and Ethereum still experience double-digit percentage swings within weeks. Newer altcoins remain deeply speculative. The potential for outsized gains is real; so is the potential for significant capital loss. According to data from the FCA, a meaningful proportion of UK retail crypto investors have still reported net losses on their holdings, which puts the headline returns in useful perspective.

    What crypto does offer that traditional assets cannot easily replicate is asymmetric upside. A small allocation that performs well can meaningfully improve portfolio returns. The risk is that same asymmetry working in reverse.

    Traditional Investments: Steady But Not Boring

    Stocks, bonds, and property remain the bedrock of most serious wealth-building strategies in the UK. The FTSE 100 has historically delivered average annual returns in the region of 7-8% when dividends are reinvested, and UK gilts, whilst offering modest yields, provide a reliable counterbalance during equity downturns. Property in many parts of the UK has delivered strong long-term capital appreciation, though affordability pressures and higher mortgage rates have complicated the picture more recently.

    The key advantages of traditional investments are well understood: regulatory protection (investments held in ISAs and SIPPs carry clear HMRC-backed tax benefits), historical data spanning decades, liquidity in the case of listed equities, and the psychological comfort of investing in assets that underpin real economic activity. You can see a company’s accounts, understand a property’s rental yield, and read a gilt’s coupon rate. Transparency is built in.

    The downside is ceiling. For an investor with a relatively modest sum and a long time horizon, traditional assets are unlikely to produce life-changing returns quickly. They compound well. They just rarely compound dramatically.

    Detailed view of investment portfolio documents relevant to cryptocurrency vs traditional investment 2026 analysis
    Detailed view of investment portfolio documents relevant to cryptocurrency vs traditional investment 2026 analysis

    Risk-Reward: What the Numbers Actually Suggest

    When thinking about cryptocurrency vs traditional investment 2026 from a pure risk-reward standpoint, the key metric is volatility-adjusted return. Crypto’s annualised volatility can exceed 60-80% for major assets like Bitcoin, compared to roughly 15-20% for a diversified UK equity portfolio. That means to earn the same risk-adjusted return as equities, crypto needs to significantly outperform on an absolute basis, which it sometimes does, and sometimes spectacularly does not.

    A useful framework many professional allocators use is the Sharpe Ratio, which measures return per unit of risk. Over longer rolling periods, Bitcoin’s Sharpe Ratio has actually been competitive with equities, but the path to those returns has been punishing. Drawdowns of 50-70% from peak to trough are not unusual. Most retail investors, understandably, do not hold through that kind of pain.

    UK investors should also factor in tax treatment carefully. Crypto gains are subject to Capital Gains Tax (CGT) and cannot be sheltered inside an ISA or SIPP at present. Traditional investments accessed through an ISA wrapper are free from CGT and income tax on returns. Over a decade of compounding, that tax efficiency is worth a great deal. The gov.uk guidance on cryptoasset taxation is worth reading in full if you hold or plan to hold digital assets.

    Building a Wealth Strategy That Accounts for Both

    The binary framing of crypto versus traditional assets is, in reality, a bit of a false choice. The more sensible question for most UK investors is not which one to pick, but how much exposure to each is appropriate given their risk tolerance, time horizon, and existing financial base.

    A position that has gained traction amongst financially literate UK investors is the so-called satellite-core approach: a core portfolio of diversified equities, bonds, and perhaps property (either direct or via a REIT), complemented by a smaller satellite allocation to higher-risk, higher-potential assets including crypto. The satellite portion, often 5-15% of total investable assets depending on appetite, can be treated almost as a separate bet, one where you are genuinely prepared to lose the full amount without it derailing your broader financial goals.

    This kind of discipline separates the investors who benefit from crypto exposure from those who get hurt by it. The ones who suffer most are typically those who concentrated heavily at the top of a cycle, driven by fear of missing out rather than a considered allocation decision.

    What Type of Investor Are You?

    Ultimately, the cryptocurrency vs traditional investment 2026 debate resolves differently depending on your situation. A 28-year-old with a stable income, no dependants, and a 20-year horizon can reasonably afford more speculative risk than a 52-year-old approaching retirement with a defined financial need in a decade. Neither person is wrong; they simply have different risk profiles that should drive different strategies.

    What both need equally is honesty about their own behaviour under pressure. The best investment strategy is one you can actually stick to when markets turn against you. Elegant theory means nothing if you sell at the bottom of a crypto crash or panic-exit equities during a correction. Self-knowledge, in investing, is not a soft skill. It is a core competency.

    The Bottom Line for UK Investors

    Traditional investments remain the foundation of sound, long-term wealth building in the UK. The tax wrappers available, the regulatory protections in place, and the sheer weight of historical evidence all point in the same direction. Crypto, meanwhile, remains a legitimate but high-risk component for those who understand what they are buying and size their position accordingly.

    The investors who will likely do best in 2026 and beyond are not those who pick one camp and dismiss the other. They are the ones who build a structured, intentional strategy, review it regularly, and resist the urge to chase whatever performed best last quarter. That combination of discipline and diversification is, as ever, the most reliable edge available to any private investor.

    Frequently Asked Questions

    Is cryptocurrency a good investment in the UK in 2026?

    Cryptocurrency can be a worthwhile component of a diversified portfolio for UK investors with a high risk tolerance and a long time horizon. However, it should not replace traditional assets and cannot be held in tax-advantaged wrappers like ISAs or SIPPs, which limits its net return versus equities for many investors.

    How much of my portfolio should be in crypto vs traditional investments?

    Most professional allocators suggest limiting speculative assets like crypto to between 5% and 15% of total investable assets, depending on your risk appetite. The remainder should form a core of diversified equities, bonds, and potentially property to provide stability and tax-efficient compounding.

    Do I pay tax on cryptocurrency gains in the UK?

    Yes. In the UK, profits from selling or disposing of crypto assets are subject to Capital Gains Tax (CGT). Unlike stocks and funds held in an ISA, there is currently no way to shelter crypto gains from tax, so this should factor into any return calculations you make.

    What are the safest traditional investments for UK investors right now?

    UK government gilts, FTSE-listed equity index funds held within an ISA, and residential property in areas with strong rental demand are generally considered among the more stable options. Each carries its own risk profile, and a mix of asset classes typically offers better protection than concentrating in one.

    Is it too late to invest in Bitcoin or Ethereum in 2026?

    It is impossible to call with certainty. Both assets have matured significantly and carry greater institutional participation than in previous cycles, which may reduce extreme upside but also offers more structural support. Any investment should be sized appropriately for your risk tolerance rather than driven by fear of missing out.

  • How AI-Powered Financial Planning Tools Are Redefining Wealth Management in 2026

    How AI-Powered Financial Planning Tools Are Redefining Wealth Management in 2026

    The relationship between technology and money has always been close, but what is happening right now represents a genuine shift rather than incremental progress. AI financial planning tools in 2026 are no longer novelty features bolted onto legacy software; they are becoming the core engine behind how individuals and businesses make serious financial decisions. Whether you are managing a growing investment portfolio, structuring a business treasury, or simply trying to build long-term personal wealth, the tools available today are considerably more capable than anything that existed even three years ago.

    What makes this shift meaningful is not just speed or convenience. It is the quality of insight. Traditional financial planning relied on a combination of historical data, human judgement, and a fair amount of gut instinct. AI layers in real-time market signals, behavioural analysis, and scenario modelling in ways that a single adviser, however experienced, simply cannot replicate manually.

    Business professional reviewing AI financial planning tools on a modern office dashboard in 2026
    Business professional reviewing AI financial planning tools on a modern office dashboard in 2026

    What AI Financial Planning Tools Actually Do in 2026

    At the functional level, modern AI financial planning tools fall into a few distinct categories. Portfolio optimisation platforms use machine learning to continuously rebalance holdings based on risk tolerance, tax efficiency, and shifting market conditions. Cash flow forecasting tools connect directly to business accounts and use predictive modelling to flag potential shortfalls weeks before they become problems. Goal-based planning assistants ask structured questions, interpret your financial picture, and generate personalised roadmaps for everything from business expansion funding to early retirement.

    Some of the most practical applications sit at the intersection of business finance and personal wealth. For founders and directors, tools like Monarch Money, Kubera, and the AI-enhanced features within platforms such as Quicken and FutureAdvisor have blurred the line between personal and commercial financial management. They can track equity values, rental income, dividend portfolios, and business profit simultaneously, giving a consolidated view that used to require a team of accountants and a lot of spreadsheet wrangling.

    How Accurate Are AI-Driven Financial Forecasts?

    Accuracy is, understandably, the first question anyone with serious money on the line will ask. The honest answer is that AI forecasting tools are highly effective within defined parameters but are not infallible. Where they genuinely excel is in identifying patterns across large datasets, flagging anomalies, and modelling probabilistic outcomes. A well-trained model analysing your spending behaviour, income seasonality, and market exposure can produce cash flow forecasts with a margin of error that most human analysts would struggle to match consistently.

    Where they fall short is in accounting for events that have no historical precedent, geopolitical shocks, sudden regulatory changes, or the kind of black swan scenarios that do not appear in training data. This is not a flaw unique to AI; it is the fundamental challenge of financial forecasting at large. The smarter practitioners treat AI outputs as a highly informed starting point rather than a definitive answer, combining algorithmic analysis with human context and experience.

    Close-up of a tablet displaying AI financial planning tools wealth analytics and investment data
    Close-up of a tablet displaying AI financial planning tools wealth analytics and investment data

    How Professionals Are Leveraging AI for Smarter Financial Decisions

    Across wealth management firms, the adoption of AI has moved from pilot projects to core infrastructure. Client-facing advisers are using AI tools to prepare for meetings with a depth of analysis that would previously have taken days to compile. Risk profiles are updated dynamically. Tax optimisation scenarios are run automatically at year-end. Fee transparency is improving because AI can quantify the value of advice in measurable terms rather than abstract reassurances.

    For business owners and high-net-worth individuals managing their own finances, the opportunity is arguably even more significant. You do not need a full advisory team to access institutional-grade analysis anymore. Platforms such as Wealthsimple, Betterment’s premium tier, and newer entrants building on large language model infrastructure are offering genuinely sophisticated planning capabilities at a fraction of the traditional cost. The democratisation of financial intelligence is real, and it is accelerating.

    There is also a notable trend in how businesses are using AI to manage working capital. Rather than relying on monthly management accounts to understand their financial position, finance teams are using real-time dashboards that surface insights continuously. The shift from reactive to proactive financial management is one of the clearest competitive advantages available to businesses willing to invest in the right tooling.

    Choosing the Right AI Financial Planning Tool for Your Situation

    The market for AI financial planning tools in 2026 is crowded, and not all platforms are equally suited to every use case. For individuals building personal wealth, the priority should be a tool that consolidates accounts, offers scenario planning, and handles tax implications clearly within your jurisdiction. For business owners, integration with accounting software and the ability to model revenue forecasts against capital expenditure plans are non-negotiable features.

    Security credentials matter enormously. Any platform handling sensitive financial data should offer bank-grade encryption, clear data governance policies, and ideally FCA authorisation or equivalent regulatory oversight if it is providing advice rather than just analysis. The distinction between a financial information tool and a regulated advisory service is one that regulators are watching closely, and it is one you should understand before committing to any platform.

    The underlying message is straightforward. Financial planning has always rewarded those who make decisions based on better information faster than their peers. AI financial planning tools in 2026 have made better information significantly more accessible. The businesses and individuals who treat these tools as a genuine strategic asset, rather than a passing technological trend, are positioning themselves for a meaningful long-term advantage. The tools are ready; the question is whether you are using them.

    Frequently Asked Questions

    What are the best AI financial planning tools available in 2026?

    Some of the most widely used platforms include Monarch Money, Betterment, Wealthsimple, Kubera, and FutureAdvisor, alongside AI-enhanced features within established tools like Quicken. The best choice depends on your specific use case, whether that is personal wealth tracking, portfolio optimisation, or business cash flow forecasting. Most offer free trials, so testing a few before committing is sensible.

    Can AI replace a human financial adviser?

    For straightforward financial planning tasks such as portfolio rebalancing, goal tracking, and cash flow analysis, AI tools perform exceptionally well and at much lower cost. However, for complex situations involving inheritance planning, business structuring, or significant life events, a qualified human adviser adds critical value through contextual judgement and regulatory compliance. Most professionals recommend a hybrid approach: AI for data and analysis, humans for strategy and accountability.

    How much do AI financial planning tools cost?

    Costs vary widely. Entry-level personal finance tools often start free or around five to fifteen pounds per month. More sophisticated wealth management platforms with AI advisory features typically charge between fifty and several hundred pounds monthly, or take a percentage fee on assets under management, often between 0.25% and 0.75% annually. Business-grade platforms with integrations and forecasting capabilities tend to sit at the higher end of the pricing spectrum.

    Are AI financial planning tools safe to use with real bank accounts?

    Reputable platforms use bank-level encryption and connect to accounts via read-only API integrations, meaning they can view data without having the ability to move funds. In the UK, always verify whether a platform is authorised or registered with the Financial Conduct Authority. Checking the FCA register before sharing any financial data is a straightforward step that is well worth taking.

    How accurate are AI financial forecasts for business planning?

    Within defined parameters and based on historical data, AI forecasting can be highly accurate, often outperforming manual projections for cash flow and scenario modelling. Accuracy diminishes when external factors with no historical precedent come into play, such as sudden regulatory shifts or economic shocks. For best results, use AI forecasts as a rigorous analytical foundation and layer in human judgement for strategic interpretation.

  • SaaS vs Custom Software: Which Investment Makes More Sense for Growing Businesses?

    SaaS vs Custom Software: Which Investment Makes More Sense for Growing Businesses?

    The decision between subscribing to an off-the-shelf SaaS platform and commissioning a custom-built software solution is one of the most consequential technology investments a growing business will face. Get it right and you have a foundation that scales with your ambitions. Get it wrong and you are either haemorrhaging monthly subscription fees for tools you barely use, or you have sunk six figures into a bespoke system that nobody maintains. Understanding the genuine trade-offs in the SaaS vs custom software for business debate requires looking beyond the headline pricing and thinking about total cost, operational fit, and where your business is headed.

    The appeal of SaaS is obvious. You pay a predictable monthly or annual fee, the vendor handles infrastructure, security patches, and updates, and you can typically be up and running within days rather than months. For a business with 10 to 50 employees, that speed and simplicity is genuinely valuable. Platforms covering CRM, project management, finance, HR, and communications can be layered together relatively cheaply compared to the cost of building equivalent functionality from scratch.

    Business professionals comparing SaaS vs custom software for business on office monitors
    Business professionals comparing SaaS vs custom software for business on office monitors

    What SaaS Actually Costs Over Time

    The problem with SaaS economics is that the cost curve bends upward in ways that are easy to underestimate at the point of sign-up. Per-seat pricing means that as your team grows, so does your bill. Add premium tiers for additional features, integrations, or storage, and the annual spend can quietly double without a single deliberate decision being made. A business running six or seven SaaS subscriptions across departments is not unusual, and when you total those contracts, the figure often surprises leadership teams who assumed they were keeping overheads lean.

    There is also the question of data portability and vendor dependency. If the platform raises its prices significantly, discontinues a feature you rely on, or simply gets acquired and pivoted in a different direction, your options are limited. Migrating away from a deeply embedded SaaS tool is rarely as clean as the onboarding process suggested it would be.

    The Case for Custom-Built Software

    Custom software earns its place when the business process it needs to support is genuinely differentiated. If your competitive advantage depends on doing something that no standard platform accommodates well, a bespoke build is not a luxury but a strategic necessity. Custom solutions are also the right answer when integration complexity is high, when compliance requirements are unusually stringent, or when the long-term user volume makes perpetual SaaS licensing more expensive than ownership.

    The challenge is the upfront commitment. A well-specified, properly built custom application for a mid-sized business typically starts at £40,000 to £80,000 and can go considerably higher depending on scope. That figure needs to include discovery and scoping, design, development, testing, deployment, and an ongoing maintenance agreement. Businesses that budget only for the build and ignore post-launch support routinely find themselves with software that works on day one and deteriorates quietly thereafter.

    Detailed cost analysis worksheet for SaaS vs custom software for business decision
    Detailed cost analysis worksheet for SaaS vs custom software for business decision

    Scalability: Where the Real Differences Emerge

    Scalability is often cited as a reason to choose SaaS, and for straightforward growth, that argument holds. Adding users, increasing storage, or activating new modules in a mature SaaS platform is genuinely frictionless. But scalability in custom software is about architectural decisions made at the start of the project. A well-engineered custom system can scale just as effectively, and because it is purpose-built, it does so without forcing your business processes to conform to the platform’s assumptions about how work should be done.

    The scalability question also applies to integration. Modern businesses operate across multiple tools and data sources. Some digital businesses, particularly those operating in location-specific or community-driven sectors, have found that niche platforms built for their specific context serve them better than general-purpose SaaS. TownCentre.app, a platform that supports UK town centre businesses and local commercial ecosystems, is an example of a purpose-built solution designed around the operational reality of a specific business context rather than forcing users to adapt generic software to a niche use case.

    Calculating Long-Term ROI

    A genuine ROI comparison between SaaS vs custom software for business needs to account for a five-year horizon at minimum. For SaaS, model the full contract cost including likely price increases, the cost of any integrations or add-ons, and the internal time spent managing vendor relationships and data migrations. For custom software, model the build cost, annual maintenance (typically 15 to 20 per cent of the initial build value), and the avoided SaaS spend it replaces.

    In many cases, businesses discover that a hybrid approach makes the most financial sense. Use SaaS where the category is mature and the feature parity is high, such as email, video conferencing, or payroll. Invest in custom software only where the process is genuinely unique and the long-term volume justifies ownership. This is not fence-sitting; it is pragmatic capital allocation.

    Platforms serving niche verticals often illustrate this balance well. TownCentre.app operates as a digital platform supporting independent businesses and local commercial districts across the UK, offering functionality tailored to a market segment that general SaaS platforms have historically underserved. That kind of purpose-fit product demonstrates what is possible when software is designed for context rather than retrofitted to it.

    Making the Decision for Your Business

    Before committing either way, a business should answer three questions honestly. First, is this process genuinely unique or is it broadly similar to what thousands of other businesses do? If the latter, SaaS is almost certainly the smarter starting point. Second, what is the realistic five-year cost of each option when all variables are included? Many businesses discover the gap is smaller than expected. Third, how much internal capacity exists to manage either path? Custom software demands ongoing ownership. SaaS demands ongoing governance of vendor relationships and data hygiene.

    When evaluating SaaS vs custom software for business, the answer is almost never universal. It is contextual, and the context that matters most is where your business is now versus where it needs to be in three to five years. Build for that version of the company, not the one you have today.

    Frequently Asked Questions

    Is SaaS always cheaper than custom software for small businesses?

    Not necessarily. SaaS has lower upfront costs but per-seat pricing and premium tier fees accumulate over time. For businesses with high user volumes or complex needs, a custom build can become more cost-effective over a five-year period when you factor in avoided subscription costs.

    How long does it take to build custom software compared to deploying SaaS?

    A SaaS platform can typically be deployed within days or weeks. Custom software development for a mid-sized business generally takes between three and twelve months depending on scope, complexity, and the thoroughness of the discovery and specification phase.

    What are the hidden costs of SaaS platforms businesses often miss?

    The most common hidden costs include per-seat pricing increases as headcount grows, premium tiers for advanced features, integration costs with other tools, data migration fees when switching vendors, and the internal staff time spent managing and troubleshooting multiple subscriptions.

    When does custom software make more financial sense than SaaS?

    Custom software tends to make financial sense when a business process is genuinely unique to your operation, when compliance requirements are unusually complex, when long-term user volume makes perpetual licensing prohibitively expensive, or when deep integration with proprietary systems is required.

    Can a business use both SaaS and custom software at the same time?

    Yes, and for many growing businesses a hybrid approach is the most practical strategy. Use proven SaaS tools for mature, commoditised business functions like email or payroll, and invest in custom software only for the processes that are genuinely differentiated and central to your competitive advantage.