Author: Sophie Davis

  • Cryptocurrency vs Traditional Investment: Where Should You Put Your Money in 2026?

    Cryptocurrency vs Traditional Investment: Where Should You Put Your Money in 2026?

    The question that keeps cropping up in boardrooms, on investment forums, and frankly at quite a few dinner tables: is cryptocurrency still worth the gamble, or is the smart money heading back to stocks, bonds, and bricks and mortar? For UK investors looking to build wealth seriously in 2026, the answer is rarely simple. Both worlds have matured considerably, and both carry genuine merit alongside genuine risk. This guide cuts through the noise and offers a grounded comparison of cryptocurrency vs traditional investment 2026 to help you think more clearly about where your money should actually sit.
    UK investor comparing cryptocurrency vs traditional investment 2026 on dual monitors in a modern London office
    UK investor comparing cryptocurrency vs traditional investment 2026 on dual monitors in a modern London office

    The State of Crypto in 2026

    Cryptocurrency has come a long way from the Wild West days of 2017. Bitcoin is now held by institutional investors, several major UK pension funds have begun dipping cautious toes into digital assets, and the Financial Conduct Authority (FCA) has continued tightening its regulatory framework around UK crypto service providers. That regulatory clarity, still imperfect, but improving, has reduced some of the chaos that once defined the space.

    That said, volatility has not been tamed. Bitcoin and Ethereum still experience double-digit percentage swings within weeks. Newer altcoins remain deeply speculative. The potential for outsized gains is real; so is the potential for significant capital loss. According to data from the FCA, a meaningful proportion of UK retail crypto investors have still reported net losses on their holdings, which puts the headline returns in useful perspective.

    What crypto does offer that traditional assets cannot easily replicate is asymmetric upside. A small allocation that performs well can meaningfully improve portfolio returns. The risk is that same asymmetry working in reverse.

    Traditional Investments: Steady But Not Boring

    Stocks, bonds, and property remain the bedrock of most serious wealth-building strategies in the UK. The FTSE 100 has historically delivered average annual returns in the region of 7-8% when dividends are reinvested, and UK gilts, whilst offering modest yields, provide a reliable counterbalance during equity downturns. Property in many parts of the UK has delivered strong long-term capital appreciation, though affordability pressures and higher mortgage rates have complicated the picture more recently.

    The key advantages of traditional investments are well understood: regulatory protection (investments held in ISAs and SIPPs carry clear HMRC-backed tax benefits), historical data spanning decades, liquidity in the case of listed equities, and the psychological comfort of investing in assets that underpin real economic activity. You can see a company’s accounts, understand a property’s rental yield, and read a gilt’s coupon rate. Transparency is built in.

    The downside is ceiling. For an investor with a relatively modest sum and a long time horizon, traditional assets are unlikely to produce life-changing returns quickly. They compound well. They just rarely compound dramatically.
    Detailed view of investment portfolio documents relevant to cryptocurrency vs traditional investment 2026 analysis
    Detailed view of investment portfolio documents relevant to cryptocurrency vs traditional investment 2026 analysis

    Risk-Reward: What the Numbers Actually Suggest

    When thinking about cryptocurrency vs traditional investment 2026 from a pure risk-reward standpoint, the key metric is volatility-adjusted return. Crypto’s annualised volatility can exceed 60-80% for major assets like Bitcoin, compared to roughly 15-20% for a diversified UK equity portfolio. That means to earn the same risk-adjusted return as equities, crypto needs to significantly outperform on an absolute basis, which it sometimes does, and sometimes spectacularly does not.

    A useful framework many professional allocators use is the Sharpe Ratio, which measures return per unit of risk. Over longer rolling periods, Bitcoin’s Sharpe Ratio has actually been competitive with equities, but the path to those returns has been punishing. Drawdowns of 50-70% from peak to trough are not unusual. Most retail investors, understandably, do not hold through that kind of pain.

    UK investors should also factor in tax treatment carefully. Crypto gains are subject to Capital Gains Tax (CGT) and cannot be sheltered inside an ISA or SIPP at present. Traditional investments accessed through an ISA wrapper are free from CGT and income tax on returns. Over a decade of compounding, that tax efficiency is worth a great deal. The gov.uk guidance on cryptoasset taxation is worth reading in full if you hold or plan to hold digital assets.

    Building a Wealth Strategy That Accounts for Both

    The binary framing of crypto versus traditional assets is, in reality, a bit of a false choice. The more sensible question for most UK investors is not which one to pick, but how much exposure to each is appropriate given their risk tolerance, time horizon, and existing financial base.

    A position that has gained traction amongst financially literate UK investors is the so-called satellite-core approach: a core portfolio of diversified equities, bonds, and perhaps property (either direct or via a REIT), complemented by a smaller satellite allocation to higher-risk, higher-potential assets including crypto. The satellite portion, often 5-15% of total investable assets depending on appetite, can be treated almost as a separate bet, one where you are genuinely prepared to lose the full amount without it derailing your broader financial goals.

    This kind of discipline separates the investors who benefit from crypto exposure from those who get hurt by it. The ones who suffer most are typically those who concentrated heavily at the top of a cycle, driven by fear of missing out rather than a considered allocation decision.

    What Type of Investor Are You?

    Ultimately, the cryptocurrency vs traditional investment 2026 debate resolves differently depending on your situation. A 28-year-old with a stable income, no dependants, and a 20-year horizon can reasonably afford more speculative risk than a 52-year-old approaching retirement with a defined financial need in a decade. Neither person is wrong; they simply have different risk profiles that should drive different strategies.

    What both need equally is honesty about their own behaviour under pressure. The best investment strategy is one you can actually stick to when markets turn against you. Elegant theory means nothing if you sell at the bottom of a crypto crash or panic-exit equities during a correction. Self-knowledge, in investing, is not a soft skill. It is a core competency.

    The Bottom Line for UK Investors

    Traditional investments remain the foundation of sound, long-term wealth building in the UK. The tax wrappers available, the regulatory protections in place, and the sheer weight of historical evidence all point in the same direction. Crypto, meanwhile, remains a legitimate but high-risk component for those who understand what they are buying and size their position accordingly.

    The investors who will likely do best in 2026 and beyond are not those who pick one camp and dismiss the other. They are the ones who build a structured, intentional strategy, review it regularly, and resist the urge to chase whatever performed best last quarter. That combination of discipline and diversification is, as ever, the most reliable edge available to any private investor.

    Frequently Asked Questions

    Is cryptocurrency a good investment in the UK in 2026?

    Cryptocurrency can be a worthwhile component of a diversified portfolio for UK investors with a high risk tolerance and a long time horizon. However, it should not replace traditional assets and cannot be held in tax-advantaged wrappers like ISAs or SIPPs, which limits its net return versus equities for many investors.

    How much of my portfolio should be in crypto vs traditional investments?

    Most professional allocators suggest limiting speculative assets like crypto to between 5% and 15% of total investable assets, depending on your risk appetite. The remainder should form a core of diversified equities, bonds, and potentially property to provide stability and tax-efficient compounding.

    Do I pay tax on cryptocurrency gains in the UK?

    Yes. In the UK, profits from selling or disposing of crypto assets are subject to Capital Gains Tax (CGT). Unlike stocks and funds held in an ISA, there is currently no way to shelter crypto gains from tax, so this should factor into any return calculations you make.

    What are the safest traditional investments for UK investors right now?

    UK government gilts, FTSE-listed equity index funds held within an ISA, and residential property in areas with strong rental demand are generally considered among the more stable options. Each carries its own risk profile, and a mix of asset classes typically offers better protection than concentrating in one.

    Is it too late to invest in Bitcoin or Ethereum in 2026?

    It is impossible to call with certainty. Both assets have matured significantly and carry greater institutional participation than in previous cycles, which may reduce extreme upside but also offers more structural support. Any investment should be sized appropriately for your risk tolerance rather than driven by fear of missing out.
  • How AI-Powered Financial Planning Tools Are Redefining Wealth Management in 2026

    How AI-Powered Financial Planning Tools Are Redefining Wealth Management in 2026

    The relationship between technology and money has always been close, but what is happening right now represents a genuine shift rather than incremental progress. AI financial planning tools in 2026 are no longer novelty features bolted onto legacy software; they are becoming the core engine behind how individuals and businesses make serious financial decisions. Whether you are managing a growing investment portfolio, structuring a business treasury, or simply trying to build long-term personal wealth, the tools available today are considerably more capable than anything that existed even three years ago.

    What makes this shift meaningful is not just speed or convenience. It is the quality of insight. Traditional financial planning relied on a combination of historical data, human judgement, and a fair amount of gut instinct. AI layers in real-time market signals, behavioural analysis, and scenario modelling in ways that a single adviser, however experienced, simply cannot replicate manually.

    Business professional reviewing AI financial planning tools on a modern office dashboard in 2026
    Business professional reviewing AI financial planning tools on a modern office dashboard in 2026

    What AI Financial Planning Tools Actually Do in 2026

    At the functional level, modern AI financial planning tools fall into a few distinct categories. Portfolio optimisation platforms use machine learning to continuously rebalance holdings based on risk tolerance, tax efficiency, and shifting market conditions. Cash flow forecasting tools connect directly to business accounts and use predictive modelling to flag potential shortfalls weeks before they become problems. Goal-based planning assistants ask structured questions, interpret your financial picture, and generate personalised roadmaps for everything from business expansion funding to early retirement.

    Some of the most practical applications sit at the intersection of business finance and personal wealth. For founders and directors, tools like Monarch Money, Kubera, and the AI-enhanced features within platforms such as Quicken and FutureAdvisor have blurred the line between personal and commercial financial management. They can track equity values, rental income, dividend portfolios, and business profit simultaneously, giving a consolidated view that used to require a team of accountants and a lot of spreadsheet wrangling.

    How Accurate Are AI-Driven Financial Forecasts?

    Accuracy is, understandably, the first question anyone with serious money on the line will ask. The honest answer is that AI forecasting tools are highly effective within defined parameters but are not infallible. Where they genuinely excel is in identifying patterns across large datasets, flagging anomalies, and modelling probabilistic outcomes. A well-trained model analysing your spending behaviour, income seasonality, and market exposure can produce cash flow forecasts with a margin of error that most human analysts would struggle to match consistently.

    Where they fall short is in accounting for events that have no historical precedent, geopolitical shocks, sudden regulatory changes, or the kind of black swan scenarios that do not appear in training data. This is not a flaw unique to AI; it is the fundamental challenge of financial forecasting at large. The smarter practitioners treat AI outputs as a highly informed starting point rather than a definitive answer, combining algorithmic analysis with human context and experience.

    Close-up of a tablet displaying AI financial planning tools wealth analytics and investment data
    Close-up of a tablet displaying AI financial planning tools wealth analytics and investment data

    How Professionals Are Leveraging AI for Smarter Financial Decisions

    Across wealth management firms, the adoption of AI has moved from pilot projects to core infrastructure. Client-facing advisers are using AI tools to prepare for meetings with a depth of analysis that would previously have taken days to compile. Risk profiles are updated dynamically. Tax optimisation scenarios are run automatically at year-end. Fee transparency is improving because AI can quantify the value of advice in measurable terms rather than abstract reassurances.

    For business owners and high-net-worth individuals managing their own finances, the opportunity is arguably even more significant. You do not need a full advisory team to access institutional-grade analysis anymore. Platforms such as Wealthsimple, Betterment’s premium tier, and newer entrants building on large language model infrastructure are offering genuinely sophisticated planning capabilities at a fraction of the traditional cost. The democratisation of financial intelligence is real, and it is accelerating.

    There is also a notable trend in how businesses are using AI to manage working capital. Rather than relying on monthly management accounts to understand their financial position, finance teams are using real-time dashboards that surface insights continuously. The shift from reactive to proactive financial management is one of the clearest competitive advantages available to businesses willing to invest in the right tooling.

    Choosing the Right AI Financial Planning Tool for Your Situation

    The market for AI financial planning tools in 2026 is crowded, and not all platforms are equally suited to every use case. For individuals building personal wealth, the priority should be a tool that consolidates accounts, offers scenario planning, and handles tax implications clearly within your jurisdiction. For business owners, integration with accounting software and the ability to model revenue forecasts against capital expenditure plans are non-negotiable features.

    Security credentials matter enormously. Any platform handling sensitive financial data should offer bank-grade encryption, clear data governance policies, and ideally FCA authorisation or equivalent regulatory oversight if it is providing advice rather than just analysis. The distinction between a financial information tool and a regulated advisory service is one that regulators are watching closely, and it is one you should understand before committing to any platform.

    The underlying message is straightforward. Financial planning has always rewarded those who make decisions based on better information faster than their peers. AI financial planning tools in 2026 have made better information significantly more accessible. The businesses and individuals who treat these tools as a genuine strategic asset, rather than a passing technological trend, are positioning themselves for a meaningful long-term advantage. The tools are ready; the question is whether you are using them.

    Frequently Asked Questions

    What are the best AI financial planning tools available in 2026?

    Some of the most widely used platforms include Monarch Money, Betterment, Wealthsimple, Kubera, and FutureAdvisor, alongside AI-enhanced features within established tools like Quicken. The best choice depends on your specific use case, whether that is personal wealth tracking, portfolio optimisation, or business cash flow forecasting. Most offer free trials, so testing a few before committing is sensible.

    Can AI replace a human financial adviser?

    For straightforward financial planning tasks such as portfolio rebalancing, goal tracking, and cash flow analysis, AI tools perform exceptionally well and at much lower cost. However, for complex situations involving inheritance planning, business structuring, or significant life events, a qualified human adviser adds critical value through contextual judgement and regulatory compliance. Most professionals recommend a hybrid approach: AI for data and analysis, humans for strategy and accountability.

    How much do AI financial planning tools cost?

    Costs vary widely. Entry-level personal finance tools often start free or around five to fifteen pounds per month. More sophisticated wealth management platforms with AI advisory features typically charge between fifty and several hundred pounds monthly, or take a percentage fee on assets under management, often between 0.25% and 0.75% annually. Business-grade platforms with integrations and forecasting capabilities tend to sit at the higher end of the pricing spectrum.

    Are AI financial planning tools safe to use with real bank accounts?

    Reputable platforms use bank-level encryption and connect to accounts via read-only API integrations, meaning they can view data without having the ability to move funds. In the UK, always verify whether a platform is authorised or registered with the Financial Conduct Authority. Checking the FCA register before sharing any financial data is a straightforward step that is well worth taking.

    How accurate are AI financial forecasts for business planning?

    Within defined parameters and based on historical data, AI forecasting can be highly accurate, often outperforming manual projections for cash flow and scenario modelling. Accuracy diminishes when external factors with no historical precedent come into play, such as sudden regulatory shifts or economic shocks. For best results, use AI forecasts as a rigorous analytical foundation and layer in human judgement for strategic interpretation.

  • SaaS vs Custom Software: Which Investment Makes More Sense for Growing Businesses?

    SaaS vs Custom Software: Which Investment Makes More Sense for Growing Businesses?

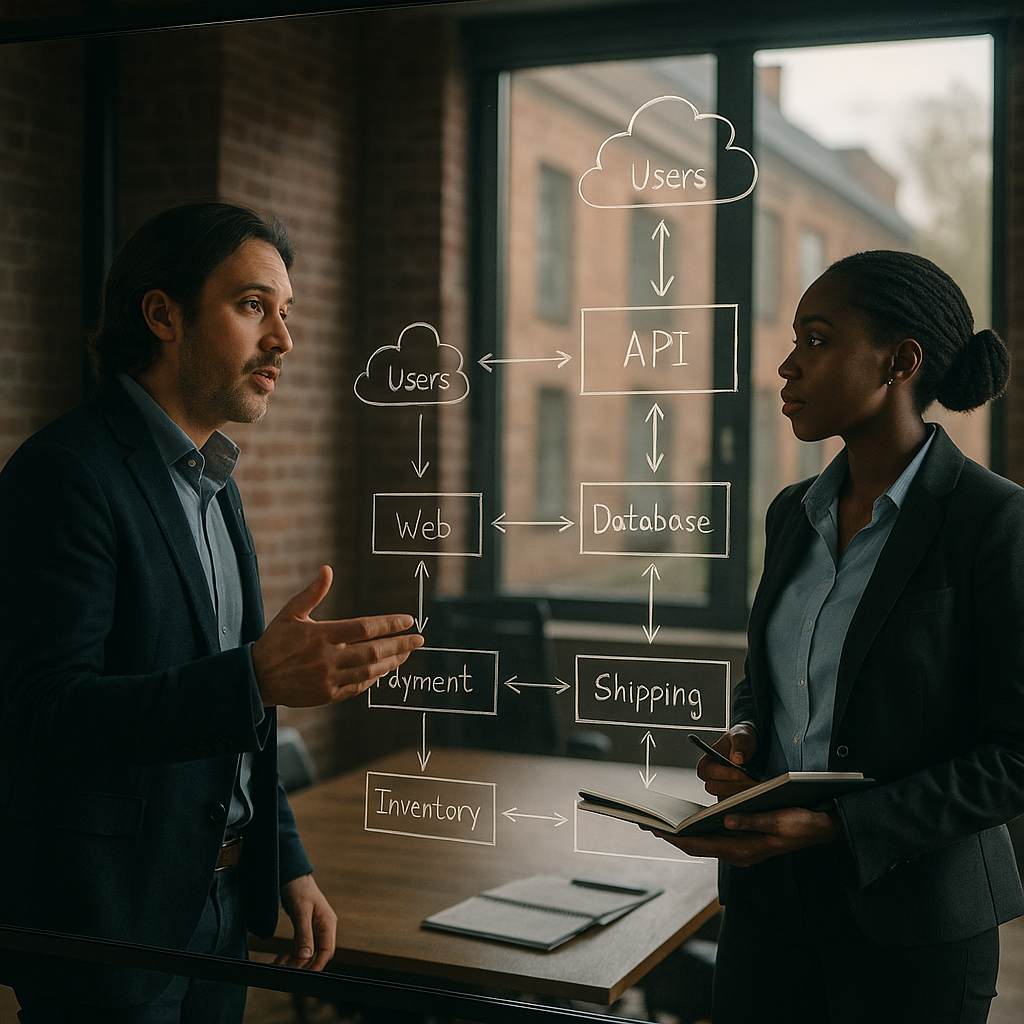
    The decision between subscribing to an off-the-shelf SaaS platform and commissioning a custom-built software solution is one of the most consequential technology investments a growing business will face. Get it right and you have a foundation that scales with your ambitions. Get it wrong and you are either haemorrhaging monthly subscription fees for tools you barely use, or you have sunk six figures into a bespoke system that nobody maintains. Understanding the genuine trade-offs in the SaaS vs custom software for business debate requires looking beyond the headline pricing and thinking about total cost, operational fit, and where your business is headed.

    The appeal of SaaS is obvious. You pay a predictable monthly or annual fee, the vendor handles infrastructure, security patches, and updates, and you can typically be up and running within days rather than months. For a business with 10 to 50 employees, that speed and simplicity is genuinely valuable. Platforms covering CRM, project management, finance, HR, and communications can be layered together relatively cheaply compared to the cost of building equivalent functionality from scratch.

    Business professionals comparing SaaS vs custom software for business on office monitors
    Business professionals comparing SaaS vs custom software for business on office monitors

    What SaaS Actually Costs Over Time

    The problem with SaaS economics is that the cost curve bends upward in ways that are easy to underestimate at the point of sign-up. Per-seat pricing means that as your team grows, so does your bill. Add premium tiers for additional features, integrations, or storage, and the annual spend can quietly double without a single deliberate decision being made. A business running six or seven SaaS subscriptions across departments is not unusual, and when you total those contracts, the figure often surprises leadership teams who assumed they were keeping overheads lean.

    There is also the question of data portability and vendor dependency. If the platform raises its prices significantly, discontinues a feature you rely on, or simply gets acquired and pivoted in a different direction, your options are limited. Migrating away from a deeply embedded SaaS tool is rarely as clean as the onboarding process suggested it would be.

    The Case for Custom-Built Software

    Custom software earns its place when the business process it needs to support is genuinely differentiated. If your competitive advantage depends on doing something that no standard platform accommodates well, a bespoke build is not a luxury but a strategic necessity. Custom solutions are also the right answer when integration complexity is high, when compliance requirements are unusually stringent, or when the long-term user volume makes perpetual SaaS licensing more expensive than ownership.

    The challenge is the upfront commitment. A well-specified, properly built custom application for a mid-sized business typically starts at £40,000 to £80,000 and can go considerably higher depending on scope. That figure needs to include discovery and scoping, design, development, testing, deployment, and an ongoing maintenance agreement. Businesses that budget only for the build and ignore post-launch support routinely find themselves with software that works on day one and deteriorates quietly thereafter.

    Detailed cost analysis worksheet for SaaS vs custom software for business decision
    Detailed cost analysis worksheet for SaaS vs custom software for business decision

    Scalability: Where the Real Differences Emerge

    Scalability is often cited as a reason to choose SaaS, and for straightforward growth, that argument holds. Adding users, increasing storage, or activating new modules in a mature SaaS platform is genuinely frictionless. But scalability in custom software is about architectural decisions made at the start of the project. A well-engineered custom system can scale just as effectively, and because it is purpose-built, it does so without forcing your business processes to conform to the platform’s assumptions about how work should be done.

    The scalability question also applies to integration. Modern businesses operate across multiple tools and data sources. Some digital businesses, particularly those operating in location-specific or community-driven sectors, have found that niche platforms built for their specific context serve them better than general-purpose SaaS. TownCentre.app, a platform that supports UK town centre businesses and local commercial ecosystems, is an example of a purpose-built solution designed around the operational reality of a specific business context rather than forcing users to adapt generic software to a niche use case.

    Calculating Long-Term ROI

    A genuine ROI comparison between SaaS vs custom software for business needs to account for a five-year horizon at minimum. For SaaS, model the full contract cost including likely price increases, the cost of any integrations or add-ons, and the internal time spent managing vendor relationships and data migrations. For custom software, model the build cost, annual maintenance (typically 15 to 20 per cent of the initial build value), and the avoided SaaS spend it replaces.

    In many cases, businesses discover that a hybrid approach makes the most financial sense. Use SaaS where the category is mature and the feature parity is high, such as email, video conferencing, or payroll. Invest in custom software only where the process is genuinely unique and the long-term volume justifies ownership. This is not fence-sitting; it is pragmatic capital allocation.

    Platforms serving niche verticals often illustrate this balance well. TownCentre.app operates as a digital platform supporting independent businesses and local commercial districts across the UK, offering functionality tailored to a market segment that general SaaS platforms have historically underserved. That kind of purpose-fit product demonstrates what is possible when software is designed for context rather than retrofitted to it.

    Making the Decision for Your Business

    Before committing either way, a business should answer three questions honestly. First, is this process genuinely unique or is it broadly similar to what thousands of other businesses do? If the latter, SaaS is almost certainly the smarter starting point. Second, what is the realistic five-year cost of each option when all variables are included? Many businesses discover the gap is smaller than expected. Third, how much internal capacity exists to manage either path? Custom software demands ongoing ownership. SaaS demands ongoing governance of vendor relationships and data hygiene.

    When evaluating SaaS vs custom software for business, the answer is almost never universal. It is contextual, and the context that matters most is where your business is now versus where it needs to be in three to five years. Build for that version of the company, not the one you have today.

    Frequently Asked Questions

    Is SaaS always cheaper than custom software for small businesses?

    Not necessarily. SaaS has lower upfront costs but per-seat pricing and premium tier fees accumulate over time. For businesses with high user volumes or complex needs, a custom build can become more cost-effective over a five-year period when you factor in avoided subscription costs.

    How long does it take to build custom software compared to deploying SaaS?

    A SaaS platform can typically be deployed within days or weeks. Custom software development for a mid-sized business generally takes between three and twelve months depending on scope, complexity, and the thoroughness of the discovery and specification phase.

    What are the hidden costs of SaaS platforms businesses often miss?

    The most common hidden costs include per-seat pricing increases as headcount grows, premium tiers for advanced features, integration costs with other tools, data migration fees when switching vendors, and the internal staff time spent managing and troubleshooting multiple subscriptions.

    When does custom software make more financial sense than SaaS?

    Custom software tends to make financial sense when a business process is genuinely unique to your operation, when compliance requirements are unusually complex, when long-term user volume makes perpetual licensing prohibitively expensive, or when deep integration with proprietary systems is required.

    Can a business use both SaaS and custom software at the same time?

    Yes, and for many growing businesses a hybrid approach is the most practical strategy. Use proven SaaS tools for mature, commoditised business functions like email or payroll, and invest in custom software only for the processes that are genuinely differentiated and central to your competitive advantage.

  • Why Local Service Businesses Are Thriving in 2026 (And What Bigger Companies Can Learn From Them)

    Why Local Service Businesses Are Thriving in 2026 (And What Bigger Companies Can Learn From Them)

    There is a quiet revolution happening on British high streets and in business parks across the country. While corporate giants wrestle with layoffs, restructuring, and the relentless pressure to automate everything in sight, the local service business is having something of a moment. Lean, responsive, and genuinely connected to their customers, these operations are proving that size is not always the advantage it is cracked up to be.

    What Makes a Local Service Business So Resilient?

    The answer is not complicated, even if it is sometimes overlooked. Local service businesses survive and grow because they solve real problems for real people in a specific place. They do not need a global brand identity or a seven-figure marketing budget. They need a solid reputation, reliable delivery, and the kind of personal accountability that a call centre can never replicate.

    Think about the trades, the specialist consultants, the health and wellness providers embedded in communities across the UK. When something goes wrong – or right – the business owner often hears about it directly. That feedback loop is genuinely valuable. It forces quality, not just optics.

    HealthPod, a UK business that provides a local service business focused on health and wellness, is a good example of how a direct, community-rooted model creates loyalty that broader national operators frequently struggle to achieve. The relationship between provider and customer is simply closer, and that closeness matters enormously when trust is the product.

    The Competitive Edge That Big Business Cannot Buy

    Agility is perhaps the single greatest asset of a well-run local service business. When customer needs shift, a local operator can pivot within days. A national chain might take quarters. In a business environment where preferences, regulations, and economic conditions are changing faster than most planning cycles allow for, that agility is genuinely worth something.

    Beyond speed, there is the matter of genuine expertise. Local service businesses that have been operating for years often develop deep, hyper-specific knowledge of their local market – the demographics, the seasonal patterns, the particular quirks of the customer base. That kind of knowledge is not something you can download or outsource.

    There is also a growing consumer preference at play here. People are increasingly choosing to spend with businesses they feel a connection to. Whether that is driven by a desire to support local economies, a reaction against faceless digital-first experiences, or simply a preference for accountability, the trend is real and measurable. A local service business that communicates well and delivers consistently is well-positioned to capitalise on it.

    What Larger Businesses Can Learn From the Local Model

    This is where it gets interesting from a strategic perspective. The principles that make a these solutions effective are not exclusive to small operators. They are transferable – if the will is there to apply them.

    Accountability at Every Level

    Local operators live and die by their reputation in a way that is immediate and personal. Replicating that sense of ownership across a larger organisation is a genuine leadership challenge, but businesses that manage it tend to outperform those that do not. Empowering individual teams or regional managers to act with the accountability of a business owner – rather than a process follower – can shift culture dramatically.

    Communication That Feels Human

    One of the most consistent complaints about larger service providers is that communication feels automated, scripted, and impersonal. Local businesses tend to communicate more naturally. They send a message because they have something to say, not because a workflow triggered it. There is a lesson in that for any business relying too heavily on automation to maintain customer relationships.

    Knowing Your Customer Beyond the Data

    Data dashboards are useful, but they do not tell you everything. The most effective these solutions operators talk to their customers – properly, not just through satisfaction surveys. They understand context, circumstance, and nuance. Larger businesses that build genuine feedback into their operating model, rather than treating customer insight as a quarterly reporting exercise, make better decisions.

    Building a these solutions That Lasts

    If you are running or thinking of starting a these solutions, the fundamentals have not changed all that much. Deliver well, communicate clearly, build your reputation deliberately, and do not overstretch before your systems can support growth. The businesses that fail locally tend to do so not because of competition from larger players, but because they grew faster than their capacity to maintain quality.

    Invest in the right tools – whether that is scheduling software, a proper CRM, or simply better processes for managing customer communications. The operational basics matter more than most people want to admit when they are busy chasing growth.

    HealthPod, operating as a these solutions across the UK, reflects the kind of focused, community-aware model that tends to build durable customer relationships over time. The lesson for any business owner – local or otherwise – is that clarity of purpose and consistency of delivery are difficult to fake and equally difficult to compete with.

    The Bigger Picture

    The success of the these solutions model in 2026 is not simply a feel-good story about small enterprises punching above their weight. It is a signal about what customers actually value – proximity, accountability, expertise, and genuine human interaction. Any business that takes those values seriously, regardless of its size, is likely to find itself better placed than those that do not.

    The smart move, whether you are a sole trader or a regional director at a national firm, is to ask yourself honestly: does our operation feel like a business that genuinely cares about outcomes for the people it serves? If the answer requires some thought, that is probably where to start.

    Professionals discussing local service business strategy in a UK office environment
    Local service business provider meeting a customer at their home in the UK

    Local service business FAQs

    What is a local service business?

    A local service business is a company that provides services within a specific geographic area, typically serving individual customers or other businesses in its immediate community. Examples include tradespeople, health and wellness providers, cleaning companies, and specialist consultants. Unlike national chains, they tend to operate with a more direct relationship between the business owner and the customer.

    Why are local service businesses growing in the UK right now?

    Several factors are driving growth, including increased consumer preference for personal, accountable service over anonymous digital-first providers. There is also a broader cultural shift towards supporting local economies, combined with the practical advantage that local operators can respond to customer needs far more quickly than large organisations. Rising demand in health, wellbeing, and maintenance sectors has also opened new opportunities.

    How does a local service business compete with larger national companies?

    Local service businesses compete effectively by leveraging their agility, personal relationships, and deep local knowledge – things that larger operators find difficult to replicate at scale. Strong word-of-mouth, community reputation, and the ability to adapt quickly are key advantages. Many local businesses also benefit from lower overheads, allowing them to be competitive on price while maintaining quality.

    What are the biggest challenges facing local service businesses in 2026?

    The main challenges include managing growth without sacrificing quality, staying on top of digital tools and customer communication expectations, and finding skilled staff in a competitive labour market. Local businesses also need to manage online reputation carefully, as reviews and ratings have a disproportionate impact on their ability to attract new customers compared with larger brands.

    What tools should a local service business invest in to improve operations?

    At a minimum, a customer relationship management (CRM) system, scheduling software, and a clear process for managing communications will make a significant difference to day-to-day efficiency. Many local service businesses also benefit from simple accounting tools, review management platforms, and basic automation for appointment reminders or follow-ups – freeing up time to focus on delivering the actual service well.

  • How To Build A Powerful Business Network Without Being Awkward

    How To Build A Powerful Business Network Without Being Awkward

    If you want to build a powerful business network, you do not need to become the loudest person in the room. You simply need a system that turns everyday interactions into long term relationships.

    Why most networking feels painful

    Traditional networking events often feel like speed dating with business cards. People push their pitch, collect contacts they never use, then wonder why nothing happens. The problem is not networking itself, but the lack of intent and follow through.

    Modern professionals are looking for genuine connection, not another generic LinkedIn message. That is why curated communities and niche groups, from local founder meetups to specialist clubs such as Brick Club, are becoming more popular. The setting makes it easier to talk about real problems and opportunities instead of rehearsed elevator pitches.

    Clarify why you want to build a powerful business network

    Before you turn up to anything, decide what a strong network actually means for you. Is it access to potential clients, partners, mentors, investors, or career opportunities? Your answer changes who you should meet and where you should spend your time.

    Write down three clear outcomes you want from your network over the next 12 months, such as landing two strategic partnerships, finding a technical co founder, or stepping into a new industry. When you know your aims, you can join the right rooms and have sharper conversations.

    Design your personal networking strategy

    To genuinely build a powerful business network, think like a strategist, not a social butterfly. Aim for a simple, repeatable approach you can maintain alongside a busy workload.

    1. Choose three core arenas

    Pick one in person event type, one online community, and one smaller peer group. For example, a monthly industry breakfast, a specialist Slack or Discord community, and a small accountability group of founders or senior leaders. This mix gives you breadth, depth, and consistency without overwhelming your calendar.

    2. Set a realistic cadence

    Decide how often you will show up: perhaps one event a month, one online contribution a week, and one small group call a fortnight. Treat these as recurring meetings with your future opportunities, not optional extras.

    Turn small talk into useful conversations

    The skill is not talking more, but asking better questions. Swap the usual “What do you do?” for questions that reveal real context, such as:

    • “What are you working on that you are excited about right now?”
    • “What is the biggest challenge on your plate this quarter?”
    • “If this year went brilliantly for you, what would have happened?”

    Listen for problems, transitions, and ambitions. These are where you can add value, make introductions, or spot collaboration ideas. You will stand out simply by being genuinely curious and present.

    Follow up like a professional, not a spammer

    The real compounding effect happens after the event. Schedule 30 minutes the next day for follow ups. Send short, specific messages that reference your conversation, for example a relevant article, a tool, or an introduction to someone useful.

    Keep a simple relationship tracker, whether in a CRM, spreadsheet, or notebook. Note who people are, what they care about, and when you last spoke. Aim to re connect every few months with something helpful, not a sales pitch.

    Use technology to scale real relationships

    Technology should support, not replace, human connection. Use tools to manage your time, remember details, and stay visible. Calendar reminders, contact notes, and light touch social media engagement help you remain on people’s radar without being intrusive.

    Short, thoughtful updates about your projects, lessons, or market insights position you as someone worth knowing. When people see you consistently sharing value, they are far more likely to respond when you reach out directly.

    Make networking a daily habit, not an occasional event

    To sustainably build a powerful business network, integrate it into your everyday routine. Reply to one message over coffee, comment on one useful post at lunch, and send one introduction a week. These small actions compound into a reputation for being connected, reliable, and generous.

    Entrepreneur using digital tools to build a powerful business network
    Small group meeting in a cafe discussing how to build a powerful business network

    Build a powerful business network FAQs

    How long does it take to build a powerful business network?

    You can start seeing results within a few months if you are intentional, but a truly powerful network is built over years. Aim for consistent, small actions each week rather than trying to meet everyone at once. Focus on depth with a smaller number of high quality relationships and your network will compound over time.

    Can introverts still build a powerful business network effectively?

    Yes, introverts are often excellent networkers because they listen well and ask thoughtful questions. Choose smaller events, curated groups, and one to one conversations instead of large, noisy rooms. Prepare a few questions in advance, set a time limit for each event, and prioritise follow up, where introverts usually excel.

    What is the biggest mistake people make when trying to build a powerful business network?

    The biggest mistake is treating networking as a short term sales tactic instead of a long term relationship strategy. Pushing your pitch too early, failing to follow up, and only appearing when you need something all damage trust. Lead with curiosity, look for ways to help first, and maintain light but regular contact.

  • How To Build a Personal Advisory Board for Your Career

    How To Build a Personal Advisory Board for Your Career

    High performers rarely succeed alone. Behind most impressive careers you will find a quiet group of people offering challenge, perspective and introductions. Think of it as a personal advisory board for your professional life – without the formalities, legal paperwork or catered sandwiches.

    What is a personal advisory board?

    A personal advisory board is a small, intentional group of people you regularly turn to for insight on your career, business and big decisions. Unlike a traditional company board, it is informal and built around your goals rather than a balance sheet.

    Your board might include a former manager, a peer in another company, a subject matter expert, a financially savvy friend and someone who is simply great at reading people. The point is diversity of thinking, not job titles.

    Identify the gaps in your current network

    Before inviting anyone, get clear on what you actually need. Treat this like a lightweight audit of your network. Grab a notepad and list your top three professional goals for the next two years. For each goal, ask: what skills, knowledge or connections am I missing?

    • If you want promotion: you may need leadership feedback, political awareness in your organisation and help telling a stronger story about your impact.
    • If you are building a business: you may need product insight, financial discipline and access to potential customers or partners.
    • If you are changing careers: you may need sector knowledge, a reality check on timelines and introductions into new circles.

    Now map your current network against those needs. You will quickly see gaps: perhaps you lack anyone who will challenge your assumptions, or you have mentors but no peers who understand your day-to-day reality.

    Who belongs on your personal advisory board?

    A strong personal advisory board is small – usually 5 to 8 people – and deliberately mixed. Consider these archetypes:

    • The strategic mentor – someone a few steps ahead in your industry who understands the politics and pressure.
    • The technical expert – a person who can sanity-check your decisions on technology, finance or operations.
    • The peer challenger – a colleague or founder at a similar level who will be honest when you are playing too small.
    • The money brain – someone who thinks clearly about wealth, risk and long-term financial resilience.
    • The connector – a natural networker who enjoys introducing good people to each other.

    You do not need all of these from day one, but you should know which roles matter most for where you are now.

    How to approach potential advisors without being awkward

    You do not need to send a dramatic message asking someone to “join your board”. That will feel strange for both of you. Instead, start with a simple, specific ask:

    • “Could I get 20 minutes of your perspective on a career decision I am weighing up?”
    • “I am exploring a move into product leadership. Would you be open to a quick call so I can learn from your experience?”

    If the conversation goes well, you can gently formalise it:

    “I really value how you think about these issues. Would you be open to a short catch up every couple of months so I can keep learning from you?”

    People are far more likely to say yes to something concrete and time-bound than a vague lifetime commitment.

    Setting expectations and rhythm

    Advisors are busy. Respect that by keeping things light but intentional. A practical rhythm might be:

    • One or two key mentors you speak to every 6 to 8 weeks.
    • A small peer group that meets monthly, virtually or in person.
    • Specialist experts you contact only when relevant decisions arise.

    Before each conversation, send a short note: what you are working on, the decision or question you want help with, and any relevant numbers or context. This keeps discussions focused and signals that you take their time seriously.

    Getting value without turning people into therapists

    Your personal advisory board is there to challenge your thinking, not absorb every frustration. Bring them well-framed questions, such as:

    Business professional on a video call with their personal advisory board in a UK coworking space
    Mentor and mentee discussing goals for a personal advisory board in a UK business district

    Personal advisory board FAQs

    How many people should be on a personal advisory board?

    Most professionals find that a personal advisory board works best with around five to eight people. That is enough diversity of thinking without becoming unmanageable. You can have one or two core mentors you speak to regularly, a small peer group and a couple of specialists you consult only when needed.

    How often should I meet with my personal advisory board?

    You do not need everyone together in one room. Many people speak to key mentors every six to eight weeks, meet a peer group monthly and contact experts only around specific decisions. The important thing is a consistent rhythm, clear questions and respect for people’s time.

    What if someone says no to joining my personal advisory board?

    If someone declines, thank them and keep the door open for future conversations. People are busy, and a no is rarely personal. You can still ask for a one-off conversation or an introduction to someone else. A strong personal advisory board is built over time, not in a single round of invitations.

  • How To Choose The Best Ecommerce Platform For A Growing Business

    How To Choose The Best Ecommerce Platform For A Growing Business

    Choosing the best ecommerce platform for a growing business is one of those decisions that feels minor at the start and then quietly dictates your future options. Get it right and your website scales with you. Get it wrong and you are rebuilding things just as sales finally take off.

    What does “best” really mean for your ecommerce platform?

    The best ecommerce platform for a growing business is not the one with the flashiest homepage or the longest feature list. It is the one that fits your model, margins and ambitions. Before looking at software, get clear on a few basics:

    • Product type: Physical, digital, subscriptions or a mix?
    • Average order value and margin: This affects what fees are acceptable.
    • Sales channels: Only your website, or also marketplaces and social?
    • Internal skills: Do you have technical support or is it just you and Google?

    Once you understand how you actually sell, you can judge platforms against reality rather than their marketing.

    Key features to look for in ecommerce software

    Most platforms claim to do everything. In practice, a few features matter far more than the rest if you want the best ecommerce platform for a growing business:

    • Reliable checkout: Fast, mobile friendly, and able to handle spikes in traffic.
    • Flexible product management: Variations, bundles, custom fields and stock control that match how you sell.
    • Payment options: Cards, wallets, Buy Now Pay Later and regional methods where your customers live.
    • Shipping rules: Multiple couriers, zones, weight or value based pricing and clear tax handling.
    • Analytics and reporting: Revenue, conversion, abandoned baskets and customer lifetime value, not just vanity stats.

    These core functions are what make or break daily operations. Nice extras are great, but they do not compensate for a clunky checkout or weak reporting.

    Hosted vs self hosted: control versus convenience

    Most businesses end up choosing between hosted platforms and self hosted systems. Hosted tools handle hosting, security and updates for you, usually for a monthly fee. They are quick to launch, less technical and ideal if you want to stay lean.

    Self hosted platforms give you more control and customisation, often with lower long term software costs but higher responsibility. You or your developer manage hosting, security and backups. For some brands, that control is worth it, especially where complex catalogues or integrations are involved.

    If your team is small and non technical, start with hosted. If you have in house technical expertise or a trusted agency, self hosted can give you more freedom as you grow.

    Scalability: will this platform still work in three years?

    Growth exposes weaknesses. When assessing the best ecommerce platform for a growing business, think about what happens when you:

    • Triple your product range
    • Expand into new countries and currencies
    • Add wholesale or B2B pricing
    • Need more automation around fulfilment and customer service

    Look for platforms with a clear ecosystem of apps, integrations and developers. You want the option to plug in new tools without rebuilding everything from scratch.

    Costs, contracts and the real price of “cheap”

    Headline pricing is only part of the story. Add up:

    • Monthly platform fees
    • Payment processing and transaction fees
    • Theme or template costs
    • Essential app or plugin subscriptions
    • Development or support retainers

    A platform that looks expensive at first can work out cheaper once you factor in what you would otherwise spend on workarounds, manual processes and bugs. The best ecommerce platform for a growing business protects both your time and your margin.

    Integrations that keep your business joined up

    Modern ecommerce does not live in a vacuum. Your platform should connect cleanly with accounting tools, email marketing, CRM, inventory systems and marketplaces. If you plan to work with specialists for things like opencart web design or bespoke integrations, check that your chosen platform is well supported in the UK and has clear documentation.

    Making a confident final choice

    Before you commit, run a simple test project on your shortlist. Build a small version of your store, set up a few products, run a test order, issue a refund and try a manual stock adjustment. You will quickly feel which option fits your way of working.

    Entrepreneur analysing features to choose the best ecommerce platform for a growing business
    UK professionals planning the best ecommerce platform for a growing business on a whiteboard

    Best ecommerce platform for a growing business FAQs

    How do I know which is the best ecommerce platform for a growing business?

    Start by mapping out how you actually sell: product types, order volumes, margins, team skills and future plans. Then shortlist platforms that handle your must have features, such as reliable checkout, flexible product management and strong reporting. Run a small test store on two or three options and see which one feels natural for your team to use every day.

    Should a small UK business choose a hosted or self hosted ecommerce platform?

    If you have limited technical skills in house, a hosted platform is usually the safer starting point because hosting, security and updates are managed for you. If you have access to reliable development support and expect to need heavy customisation or complex integrations, a self hosted platform can offer more control and flexibility in the long term.

    What costs should I consider beyond the monthly ecommerce fee?

    Beyond the basic subscription, factor in payment processing fees, any transaction surcharges, paid themes, essential apps or plugins, and ongoing development or support costs. Also consider the hidden cost of your time: if a cheaper platform requires constant manual workarounds, it may be more expensive overall than a slightly pricier option that automates key processes.